Amended Self Assessment Tax Return UK – Tax Return Amendment & Correction Service
Leave your details and our team will get back to you shortly.
Need to Correct a Self Assessment Tax Return?
If you have already submitted your Self Assessment tax return and later discover an error, missing income, an incorrect expense claim or information that was not available when you filed, the return may need to be amended.
Audit Consulting Group provides professional support with amended Self Assessment tax returns for UK taxpayers. We review the return already submitted, establish what needs to change, recalculate the tax position where required and prepare the appropriate correction for HMRC.
An amendment does not necessarily mean that you are due a tax refund. Correcting a return may reduce your tax liability, increase the amount due or simply correct information without creating a significant change in tax. The priority is to establish the correct position and support the amendment with appropriate records.
What Our Self Assessment Amendment Service Includes
The amount of work involved depends on what is wrong with the original return and whether the standard amendment deadline is still open. Our tax return amendment service can include:
- reviewing the Self Assessment return already submitted;
- identifying incorrect, incomplete or omitted information;
- reviewing supporting tax and financial records;
- checking relevant income, expenses and tax reliefs;
- recalculating the tax position where required;
- preparing the amended Self Assessment tax return;
- submitting the amendment to HMRC where appropriate;
- reviewing the effect on tax due, potential repayments and payments on account;
- helping with HMRC correspondence connected with the correction where this falls within the agreed scope;
- reviewing the available route where the normal amendment deadline has already passed.
Before anything is submitted, we explain what is being changed and why. This is particularly useful where the amendment materially changes taxable income, tax due or a potential repayment.
What Is an Amended Self Assessment Tax Return?
 An amended Self Assessment tax return is a correction to a return that has already been submitted to HMRC. A tax amendment may be needed because figures were entered incorrectly, information was omitted, estimated figures were used or relevant documents arrived after the original return was filed.
Common reasons for amending a tax return include omitted income, missed or incorrectly claimed business expenses, errors in rental income or property costs, incorrect dividend figures, foreign income that was not included, pension or Gift Aid information recorded incorrectly, and estimated figures that need to be replaced with final amounts.
Depending on the correction, an amended tax return can result in additional tax to pay, a lower tax liability or a potential repayment from HMRC.
Can You Amend a Self Assessment Tax Return After Submission?
Yes. HMRC allows a taxpayer to change a Self Assessment tax return after it has been submitted, subject to the applicable amendment deadline.
If you filed online, you normally need to wait 72 hours after filing before updating the return online. If commercial software was used, the amendment may need to be made through that software or another appropriate filing route.
For paper returns, corrected pages can be sent to HMRC and should be clearly marked as an amendment, with the taxpayer’s name and Unique Taxpayer Reference included. An authorised tax agent can also prepare and submit an amendment on a client’s behalf where the relevant filing route and deadline allow it.
Self Assessment Tax Return Amendment Deadline
In most cases, you can correct a Self Assessment tax return within 12 months of the statutory filing deadline.
For example, a Self Assessment return for the 2024/25 tax year normally has a filing deadline of 31 January 2026. The standard deadline for amending that return would therefore usually be 31 January 2027.
The position can differ where HMRC issued a notice to file late, so the relevant deadline should be checked rather than assumed.
If the standard amendment period has expired, an incorrect tax position may still need to be addressed. The route depends on whether tax was underpaid or overpaid, the reason for the error and the tax year involved.
How Far Back Can You Amend a Tax Return in the UK?
There is an important distinction between amending a return within the normal amendment window and correcting a tax position after that window has closed.
Once the normal amendment period has passed, you may need to contact HMRC in writing rather than simply submitting another amended return. If income was omitted and too little tax was paid, HMRC should be notified so the position can be corrected.
Where tax has been overpaid because of a qualifying mistake, an overpayment relief claim may sometimes be available. The normal time limit is four years after the end of the relevant tax year. Overpayment relief has specific conditions and exclusions, so an older return should be reviewed before assuming that a repayment can still be claimed.
Self Assessment Amendment Deadlines and Time Limits
| Situation | Time Limit | What You Can Normally Do | Key Point |
|---|---|---|---|
| Standard Self Assessment amendment | 12 months after the statutory filing deadline | Amend the submitted Self Assessment tax return | This is the normal amendment window for correcting a return already filed with HMRC. |
| 2024/25 Self Assessment return | Usually until 31 January 2027 | Submit an amendment to the 2024/25 return | The normal filing deadline is 31 January 2026, giving a standard amendment deadline of 31 January 2027. |
| Online return just submitted | Wait 72 hours (3 days) | Then make the correction through the appropriate online filing route | HMRC normally requires a 72-hour wait after online filing before the return can be updated. |
| Standard amendment deadline has passed | More than 12 months after the statutory filing deadline | Write to HMRC or consider another appropriate correction route | You cannot normally rely on the standard amendment process once the amendment window has closed. |
| Potential overpayment relief claim | Up to 4 years after the end of the relevant tax year | Consider an overpayment relief claim where the qualifying conditions are met | Overpayment relief is a separate claim and is not simply a late amended tax return. |
| Income omitted from an older return | After the normal amendment window | Notify HMRC in writing | The route differs from an overpayment relief claim because the correction may result in additional tax being due. |
Amending a Tax Return vs Overpayment Relief
 Amending the Self Assessment Return
 Amending the Self Assessment Return
If the normal amendment window is still open, the original return can generally be corrected. The revised figures then become part of the Self Assessment position for that year.
Overpayment Relief
If the amendment deadline has passed and a qualifying mistake resulted in too much tax being paid, it may be necessary to consider an overpayment relief claim instead. This is a separate claim and must meet HMRC’s requirements; it is not simply an amendment to the old return.
Previously Undeclared Income
If an older return omitted income and the normal amendment window has closed, the appropriate action is different again. HMRC should be notified of the underpayment rather than treating the matter as an overpayment relief claim.
This distinction is why older tax return corrections often require more review than a straightforward amendment made shortly after filing.
How to Amend a Self Assessment Tax Return
Amending an Online Self Assessment Return
For eligible online returns, the taxpayer can normally sign in to their HMRC account, select the relevant tax year, make the necessary corrections and submit the updated return. If the original return was filed online, the normal 72-hour wait after submission should be taken into account.
Amending a Paper Self Assessment Return
A paper return can be corrected by sending the relevant amended pages to HMRC. The pages should be marked as an amendment and include the taxpayer’s name and UTR.
Using a Tax Agent
If the amendment involves several changes, uncertain tax treatment, rental income, foreign income, business expenses, dividends or an older tax year, professional review may be appropriate before anything is resubmitted.
Changing the number is only the final step. The revised figure first needs to be supported by the records and treated correctly for the relevant tax year.
What Information Do You Need to Amend a Tax Return?
To amend a Self Assessment tax return correctly, you need records that support the proposed correction. Depending on the issue, these may include:
- a copy of the submitted Self Assessment return and the relevant tax year;
- your Unique Taxpayer Reference;
- P60 or P45 forms and dividend vouchers;
- rental income and property expense records;
- business invoices, expense receipts and bank statements;
- pension contribution or Gift Aid records;
- foreign income and foreign tax documentation;
- relevant HMRC correspondence;
- the documents or information that led you to identify the original error.
It is also useful to explain what you believe is wrong with the original return. We can then compare that explanation with the submitted figures and supporting evidence.
Common Self Assessment Corrections
Self Assessment corrections range from straightforward data-entry errors to changes that affect several parts of the tax calculation. We commonly review omitted self-employment income, missed business expenses, rental income and property costs, dividend figures, foreign income, pension contributions, tax reliefs and estimated figures that no longer match the final records.
Not every difference means the original return is wrong. Before making a change, the underlying tax treatment and evidence should be checked.
Record-Keeping and Evidence for an Amended Tax Return
An amendment should be based on accurate and supportable information. Changing a return without checking the underlying records can replace one problem with another.
Depending on your circumstances, HMRC may expect records supporting income, expenses, reliefs and other Self Assessment figures to be retained for the relevant statutory period. Good documentation also matters if HMRC later asks how an amended figure was calculated.
For that reason, we review the available evidence alongside the tax treatment rather than focusing only on the final number entered on the return.
What Happens After You Amend Your Tax Return?
Your Tax Liability Decreases
If the correction reduces the amount of tax due and tax has already been overpaid, you may be able to claim a repayment from HMRC.
Your Tax Liability Increases
If the amendment shows that additional tax should have been paid, HMRC will update the Self Assessment position. Interest may also arise where tax should have been paid earlier.
The Return Changes Without a Significant Refund or Additional Liability
Some amendments correct reporting without creating a large financial difference. Accuracy still matters, particularly where the original figures do not match the underlying records.
For an eligible return amended online, the updated bill can normally be viewed once the amendment has been processed through the online account. The account statement will then reflect the difference from the previous calculation, including relevant interest where applicable.
What Can Change After an Amended Self Assessment Tax Return?
| Amendment Outcome | Possible Effect | Timing / Figure | What to Check |
|---|---|---|---|
| Tax liability decreases | You may have paid too much tax and a repayment may become available | Updated online bill can normally be viewed straight away | Check the revised calculation and whether the amendment creates an actual overpayment. |
| Tax liability increases | Additional tax may become payable | Updated online bill can normally be viewed straight away | Check the additional amount due, payment deadline and whether interest applies. |
| Online account statement updates | The statement shows the difference between the previous and amended calculation | Normally within 3 days | Review whether you owe more or less tax and any interest shown on the account. |
| Payments on account change | The amendment may increase or reduce future payments on account | Depends on the revised Self Assessment calculation | Check both the amended liability and the effect on upcoming payments on account. |
| No significant financial change | The amendment may correct reporting without creating a material repayment or additional liability | No fixed monetary amount | Ensure the amended figures now agree with the supporting records. |
| Amendment made after the normal deadline | A different HMRC correction route may be required | Standard amendment window: 12 months after the statutory filing deadline | Establish whether the issue concerns underpaid tax, overpaid tax or another type of correction. |
Amended Tax Return Refunds
An amended tax return refund is possible where the correction reduces the taxpayer’s liability and creates an overpayment. This can happen, for example, where allowable expenses were omitted, income was overreported or relevant tax treatment was applied incorrectly.
A repayment should not be assumed before the return and supporting records have been reviewed. An amendment can equally reveal additional tax due, so our starting point is the correct tax position rather than a target refund amount.
What If You Owe More Tax After Amending?
If a tax return amendment increases the liability, the updated Self Assessment position may include additional tax and, depending on the timing, interest. The correction can also affect payments on account where the amended figures change the amount on which those payments are based.
The amendment and the payment position should be reviewed together, but they are not the same task. Correcting the return establishes the revised liability; any additional amount due then needs to be dealt with according to the relevant payment position and HMRC requirements.
Penalties, Interest and HMRC Enquiries
Submitting an amended return does not automatically mean that HMRC will charge a penalty or open an enquiry.
The treatment of an inaccurate return depends on the circumstances, including how the error arose. A mistake made despite taking reasonable care is not treated in the same way as an inaccuracy caused carelessly or deliberately.
Where an error resulted in too little tax being paid, the circumstances and timing of the correction may be relevant to the penalty position. Any potential penalty needs to be considered separately from the mechanical process of changing the return.
HMRC can also ask for supporting information about amended figures. Significant corrections should therefore be based on clear calculations and appropriate records rather than being made simply to change the final tax outcome.
Important Considerations Before Amending Your Tax Return
Before submitting a tax amendment, check whether the original figure is actually incorrect, whether the amendment deadline is still open, which tax year the income or expense belongs to and whether evidence supports the proposed change.
It is also worth considering whether the correction affects another part of the calculation, including payments on account, and whether an older-year correction requires a route other than a normal amendment.
How Much Does It Cost to Amend a Self Assessment Tax Return?
The cost of filing an amended tax return depends on the work required. A correction involving one clearly identified figure with complete records is different from reconstructing income and expenses, reviewing several income sources or correcting multiple tax years.
Factors that can affect an amended tax return cost include the complexity of the original return, the number and type of corrections, the quality of the records, the tax years involved and whether additional calculations or HMRC correspondence are required. Self-employment, rental, dividend and foreign income issues can also increase the amount of review needed.
A straightforward amendment can often be scoped once we have seen the submitted return, the proposed correction and the supporting records. Where the issue is more complex, we first establish what needs to be reviewed so the scope is clear before substantive work begins.
How Audit Consulting Group Amends Your Tax Return
Our process separates the review of the original return from the actual amendment. This avoids changing figures before the reason for the difference has been established.
1. Review the Submitted Return
We review the Self Assessment return already filed and identify the figures or sections that may require correction.
2. Check the Supporting Information
We compare the original return with the relevant records, such as income documents, bank statements, invoices, expense records, dividend vouchers or property information.
3. Recalculate the Tax Position
Where the correction affects tax, we recalculate the relevant position using the information available and the rules applicable to that tax year.
4. Explain the Proposed Amendment
We explain what needs to change and the expected effect on the Self Assessment position before the amendment is submitted.
5. Prepare and Submit the Amendment
Once approved, the amended return or other appropriate correction can be prepared and submitted to HMRC within the agreed scope.
6. Review the Updated Position
Where required, we can help review the resulting HMRC calculation, additional liability, repayment position or related correspondence.
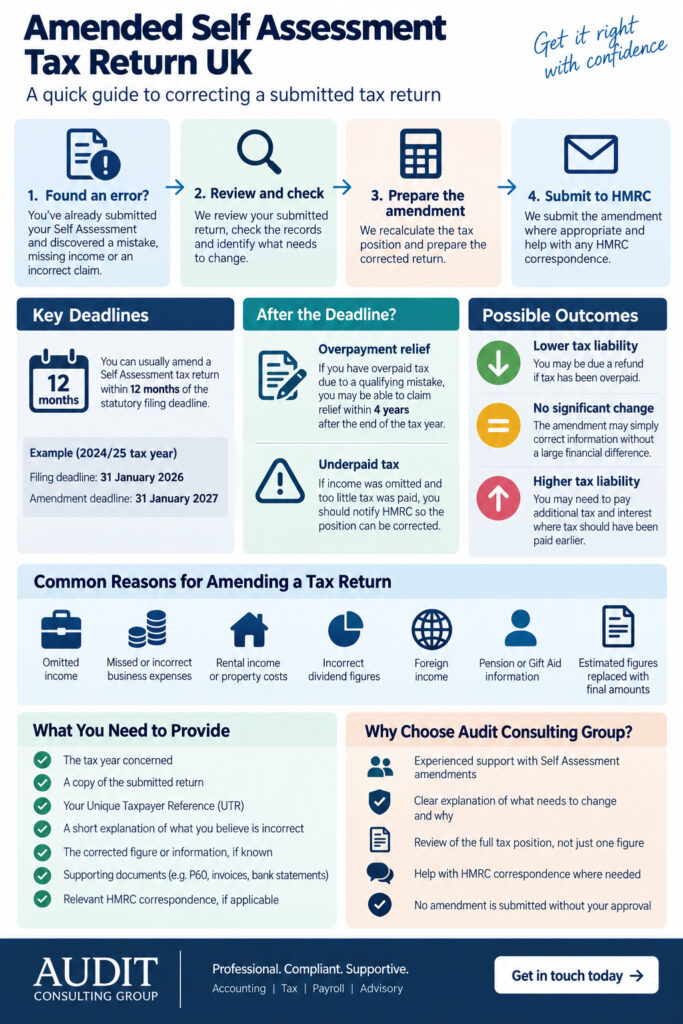
What We Need From You
The best starting point is your UTR, the tax year concerned, a copy of the submitted return and a short explanation of the error you have identified.
We may also need the original tax calculation, corrected information, supporting financial records and relevant HMRC correspondence. If you are not certain what caused the problem, send the original return and the records that raised the concern. The first task is then to establish whether an amendment is actually required.
Practical Self Assessment Amendment Scenarios
The examples below illustrate common amendment situations. They are not client case studies, and the tax outcome in a real case depends on the taxpayer’s records and circumstances.
Self-Employed Individual Who Missed Business Expenses
A freelancer submits a return with business income correctly reported but later discovers that legitimate business expenses were omitted. The work would involve comparing the expense records with the original return, checking which costs relate to the relevant tax year and recalculating the self-employment profit before preparing the amendment.
The practical outcome is a corrected taxable profit figure supported by the business records. Whether that creates a repayment depends on the individual’s overall tax calculation.
Landlord With Incorrect Property Figures
A landlord includes rental income but later identifies that some property costs or finance-cost information was not reflected correctly. The original property pages and supporting records need to be reviewed before the calculation is changed.
The resulting amendment should align the property figures with the available records and the tax treatment applicable to the relevant costs, rather than simply deducting every property expense from rental income.
Company Director With Incorrect Dividend Information
A director files a Self Assessment return using provisional information and later receives final dividend documentation showing different figures. The submitted return can be compared with the final vouchers and other relevant records before the dividend figures and personal tax calculation are corrected.
The practical outcome is a Self Assessment position that reflects the final dividend information rather than the provisional figures originally used.
Who We Help With Self Assessment Corrections
We assist self-employed individuals, freelancers, contractors, CIS subcontractors, landlords, company directors, people receiving dividends, individuals with foreign income and taxpayers with multiple sources of income.
We also help where estimated figures were used or an error was discovered only after submission. A single omitted figure may be straightforward; an amendment involving several income sources or an older tax year usually requires more review.
What Taxpayers Often Underestimate About Amended Returns
An amended Self Assessment return is not simply a replacement form. Changing one figure can affect other parts of the tax calculation, including taxable profit, reliefs, tax bands, payments on account and the final amount payable or repayable.
Another common misunderstanding is that every amendment reducing tax should automatically generate a refund. HMRC may need to process the correction, review the account or ask for additional information before any repayment is made.
The safest starting point is the evidence and the correct tax treatment, not the desired financial outcome.
Why Choose Audit Consulting Group for a Tax Return Amendment?
Amended returns require a different review from preparing a new Self Assessment return from the beginning. We need to understand what was originally reported, what has changed and whether the proposed correction affects other parts of the calculation.
Our approach starts with the submitted return and supporting records. We establish the relevant amendment route and deadline, explain the proposed changes before submission and calculate the tax position without assuming that every correction should produce a refund.
Where the amendment involves self-employment, property, dividends, foreign income or multiple income sources, the different parts of the return can be reviewed together so that one correction does not create an inconsistency elsewhere.
No amendment is submitted without the client’s approval.
Frequently Asked Questions About Amended Self Assessment Tax Returns
Can I amend my Self Assessment tax return after submission?
Yes. A Self Assessment return can normally be amended after submission provided the applicable amendment deadline has not passed.
How long do I have to amend a Self Assessment tax return?
The standard amendment window is generally 12 months after the statutory filing deadline. For example, a 2024/25 return with a normal filing deadline of 31 January 2026 would usually need to be amended by 31 January 2027.
How soon after submitting can I amend my tax return?
If you submitted the return online through HMRC, you normally need to wait 72 hours before making an online amendment.
How far back can you amend a tax return in the UK?
The normal amendment window is generally 12 months after the statutory filing deadline. Once it has passed, another correction route may be required. Where tax has been overpaid because of a qualifying mistake, overpayment relief may sometimes be available within four years after the end of the relevant tax year.
Can I amend a tax return after 12 months?
You cannot normally use the standard amendment process after the amendment deadline has expired. Depending on the circumstances, the next step may involve notifying HMRC of omitted income or considering an overpayment relief claim.
How do I amend my Self Assessment tax return online?
For an eligible return filed through HMRC’s online service, you can normally access your Self Assessment account, select the relevant tax year, make the correction and submit the updated return. Different arrangements may apply where commercial filing software was used.
Where do I send an amended paper Self Assessment tax return?
Corrected paper pages should be sent to the appropriate HMRC address for your Self Assessment correspondence. They should be marked as an amendment and include your name and UTR.
Can an accountant amend my Self Assessment tax return?
An authorised tax agent can normally prepare and submit a Self Assessment amendment on your behalf, subject to the relevant deadline and filing method.
What documents do I need to amend my tax return?
The documents depend on the correction. They may include the submitted return, P60 or P45 forms, bank statements, invoices, expense receipts, dividend vouchers, rental records, pension records, foreign income documentation and relevant HMRC correspondence.
Can I amend my tax return if I forgot to include income?
Yes. Omitted income should be corrected. If the normal amendment deadline has already passed, a different correction route may be required.
Can I amend my return if I missed allowable expenses?
If legitimate allowable expenses were omitted, it may be possible to correct the return within the amendment window. The expenses should relate to the correct tax year and be supported by appropriate records.
Will I get a refund after amending my tax return?
Possibly. If the amendment reduces your tax liability and creates an overpayment, a repayment may be available. Not every amended tax return results in a refund.
What happens if I owe more tax after amending?
HMRC will update the Self Assessment position to reflect the revised liability. Additional tax may become payable and interest can arise where tax should have been paid earlier. The amendment can also affect payments on account.
Can HMRC charge a penalty because I amended my return?
An amendment does not automatically create a penalty. HMRC considers how an inaccuracy arose and the relevant circumstances, including whether reasonable care was taken.
Can HMRC investigate an amended tax return?
HMRC can review Self Assessment returns and may ask questions about amended figures. Significant corrections should therefore be supported by appropriate calculations and documentation.
How much does it cost to file an amended tax return?
The cost depends on the complexity of the correction, the quality of the records, the number of tax years involved and whether additional calculations or HMRC correspondence are required.
What is overpayment relief?
Overpayment relief is a separate route that may allow a taxpayer to claim relief where too much tax was paid and the normal Self Assessment amendment period has expired. The normal claim limit is four years after the end of the relevant tax year, subject to HMRC’s conditions and exclusions.
Will amending my return affect payments on account?
It can. If the amendment changes the amount used to calculate payments on account, those payments may also need to be updated as part of the revised Self Assessment position.
Get Help With an Amended Self Assessment Tax Return
If you have already filed your Self Assessment tax return and discovered an error, the first step is to establish what is wrong, which tax year is affected and whether the normal amendment deadline remains open.
Send us the relevant tax year, a copy of the submitted return and a short explanation of the issue. Audit Consulting Group can review the position, identify the appropriate correction route and explain what information is needed before an amendment is prepared.
Whether the correction results in additional tax, a reduced liability or a potential refund, the objective is the same: an accurate and supportable Self Assessment position with HMRC.