SA401 Form: HMRC PDF Download & Partner Registration Guide
Leave your details and our team will get back to you shortly.
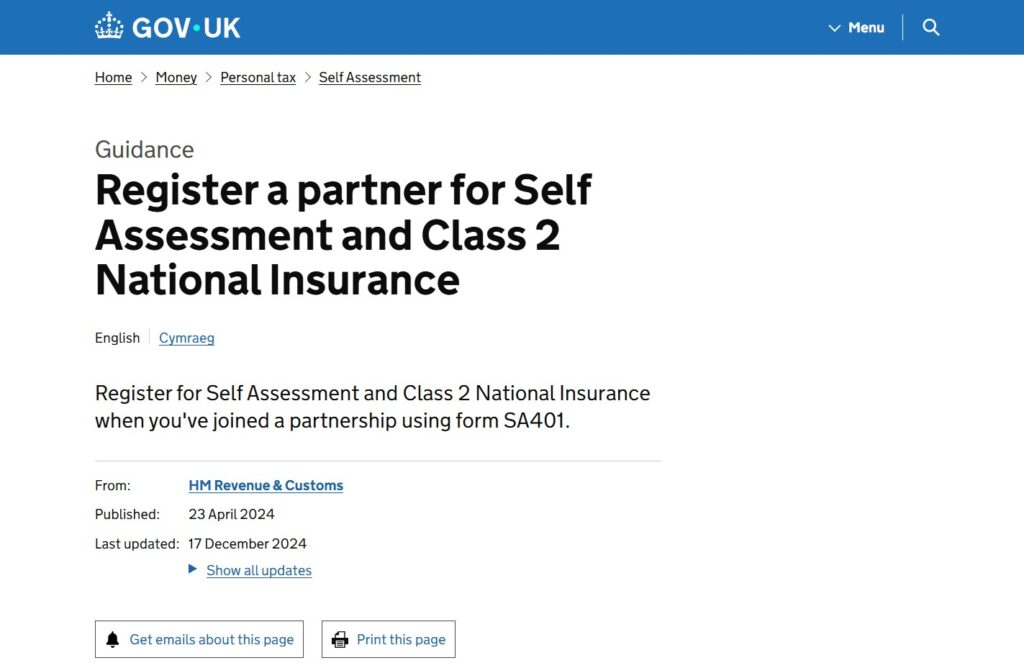
The HMRC SA401 form is used to register an individual partner for Self Assessment and Class 2 National Insurance purposes when they join a business partnership. It does not register the partnership itself and it is not an annual tax return. If you are asking what is a SA401 form, it is the individual partner registration document, not the partnership’s annual tax return.
Get the current SA401 form, PDF and registration guidance from HMRC. The route depends on your role: the nominated partner can register directly online where eligible; another individual partner joining a partnership must use the postal route. Completing a form on-screen is not the same as submitting it online.
SA401 Form PDF Download — Official HMRC Version
Looking for an SA401 form PDF or SA401 form download? HMRC provides a downloadable, printable SA401 PDF, a PDF that can be completed on-screen before printing, and an on-screen form-filling option that must also be printed and posted. Use the current official SA401 download page rather than a saved historical copy. The downloadable PDF is currently listed by HMRC as two pages; check the version and postal address shown on the actual form before using it.
To download SA401 or obtain an SA401 form to print, save the official PDF, prepare the relevant details, complete the form and follow the instructions on the document. The on-screen form-filling option cannot save your progress, so have your information ready first.
What Is the SA401 Form? Key Facts at a Glance
| Question | Answer |
|---|---|
| Form | SA401 — individual partner registration |
| Authority | HM Revenue & Customs (HMRC) |
| Purpose | Register an individual partner for Self Assessment and Class 2 National Insurance purposes |
| Format | Direct online registration for eligible nominated partners; postal form for other individual partners |
| Tax-year edition | SA401 is event-based, not an annual ‘SA401 2026’ return |
Who Needs to Complete the SA401 Partnership Registration Form?
If you need to register a partner for Self Assessment, first identify whether the applicant is an individual and whether they are the nominated partner. An individual who becomes a partner generally needs their own Self Assessment registration and partnership record. The nominated partner also has responsibility for the partnership’s registration and returns. An individual partner’s registration and the partnership’s registration are separate matters.
| Situation | Likely form or route | Qualification |
|---|---|---|
| Individual nominated partner | SA401-related direct online service or postal route | Online only where eligible |
| Other individual joining partner | SA401 by post | On-screen completion still requires printing and posting |
| New ordinary partnership itself | SA400 or the relevant online registration service | Partnership registration is separate from partner registration |
| LLP or limited partnership | Companies House registration may establish the partnership’s HMRC record | Does not remove individual members’ separate registration obligations |
| Company or trust as partner | SA402 | Not the individual SA401 form |
| Employee who is not a partner | Not SA401 solely because they work for the business | Check their actual tax circumstances |
What Information Is Needed for SA401?
The official SA401 instructions and SA401 guidance on GOV.UK identify the information to have ready. If you are looking for SA401 notes, use the instructions on the current HMRC page and the notes printed on the latest form rather than relying on an old downloadable guide. These are details to enter, not a universal list of documents to attach.
| Detail | When needed | Practical point |
|---|---|---|
| National Insurance number | Standard preparation information | Use the individual’s number |
| Personal Unique Taxpayer Reference (UTR) | If already held | Different from the partnership UTR |
| Date self-employment started | When applicable to the registration | Check against your own records |
| Date joined partnership | For the joining event | May differ from partnership’s start date |
| Partnership name, address and UTR | Partnership identification | Ask the nominated partner if missing |
| Companies House registration number | For specified LLPs/LPs registered from 25 October 2010 | Conditional, not a requirement for every partnership |
Personal UTR vs Partnership UTR: a Practical Check
A personal UTR does not by itself prove that HMRC has recorded your new partnership membership. The partnership also has its own UTR. If you already file Self Assessment, check whether your new partnership source has been registered; do not apply for a second personal UTR simply because you joined a partnership. If the partnership UTR is missing, ask the nominated partner to check the partnership registration and HMRC correspondence before completing the relevant fields.
Useful preparation records may include the partnership agreement and correspondence confirming joining dates. HMRC’s published SA401 information list does not mean these must all be attached to the form.
How to Fill In Form SA401: Step-by-Step Instructions
- Confirm you are registering an individual partner, rather than the partnership itself or a company partner.
- Obtain the current SA401 form and check whether the nominated-partner online service applies to you.
- Gather the personal details, joining dates and partnership information listed above.
- Complete the current HMRC fields accurately; do not substitute the partnership UTR for your personal UTR.
- Use the correct submission route, keep a copy for your records and monitor HMRC’s response.
Before you fill in form SA401, check the official fields and registration route. The precise boxes and instructions should be taken from the current HMRC form, not from an older screenshot or unofficial SA401 example.
SA401 Form Online or by Post: How to Submit
| Route | Who can use it? | What actually submits the registration? |
|---|---|---|
| HMRC direct online registration service | Nominated partner, where eligible | Completing the official signed-in online process |
| HMRC on-screen form-filling option | People using the postal route | Printing and posting the completed form |
| Downloadable SA401 PDF | People using the postal route | Completing, printing and posting to the address on the current form |
Searches for an SA401 form online can refer either to actual online registration or to a printable form. SA401 online can therefore mean two different things. The HMRC on-screen printable form is not an electronic upload facility. HMRC does not list ordinary email or PDF upload as a substitute for the required postal submission. If you are asking where to send SA401 or looking for the SA401 address, use the postal address printed on the current HMRC form, not an address copied from an old article. The SA401 paper form must be posted when that route applies. Check the official SA401 online and postal options.
SA401 Deadline: When Must a Partner Register?
HMRC’s partnership registration guidance states that registration is required by 5 October in the business’s second tax year. For example, if someone started a partnership or became a partner during 6 April 2025 to 5 April 2026, the illustrative deadline is 5 October 2026. Check your own joining date and Self Assessment status: the relevant obligation is fact-dependent, particularly if you are already registered.
If the deadline has passed, establish whether HMRC already has your individual and partnership details, take the correct registration action promptly and obtain tailored guidance where the facts are unclear.
What Happens After Sending SA401?
HMRC says it will usually contact you within 15 days of receiving the form, although busy periods can take longer. This is not a guarantee that a UTR will arrive within 15 days. If HMRC has not contacted you after three weeks, use the response-checking guidance linked from the official SA401 page.
Keep a record of the submission method and date, and review any correspondence for errors. Where applicable, the partnership and its partners will later have distinct tax-return responsibilities.
SA400 and SA401 vs SA402 — Which HMRC Form Do You Need?
| Form | Main purpose | Not a substitute for |
|---|---|---|
| SA400 | Register the partnership where required | Registering every individual partner |
| SA401 | Register an individual partner | Registering the partnership entity |
| SA402 | Register a partner that is not an individual | SA401 for an individual |
| SA800 | Partnership annual tax return, where required | Initial partner registration |
| SA100 with SA104 | Individual Self Assessment and partnership pages, where required | Registering a newly joining partner |
The difference between SA400 and SA401 is the applicant: SA400 concerns the partnership registration where required, while SA401 concerns an individual partner. When comparing SA401 and SA402, the key distinction is whether the partner is an individual or a non-individual entity. For the partnership itself, consult HMRC’s SA400 guidance; for a company, trust or other non-individual partner, consult SA402 guidance. The special registration arrangements for LLPs and limited partnerships are explained in HMRC’s Partnership Manual.
Common SA401 Errors and What to Do
| Mistake | Why it matters | Next step |
|---|---|---|
| Entering the partnership UTR as a personal UTR | They identify different records | Verify both numbers separately |
| Assuming a filled-in online form was submitted | Printable version still requires post | Follow the postal instructions |
| Sending an old PDF to an old address | Details or routing may change | Use current HMRC form and printed address |
| Assuming an existing personal UTR covers a new partnership | Partnership membership may not be recorded | Check the partnership link with HMRC |
| Treating SA401 as the annual return | Registration and reporting are distinct | Identify later return obligations separately |
If information has already been sent incorrectly, use HMRC’s relevant contact and registration guidance to establish the correction route. A correction to registration information is not the same as appealing a penalty or decision.
SA401 Form FAQs
Can I email or upload an SA401 PDF?
HMRC’s published SA401 postal route requires the completed form to be printed and posted. Do not assume an email attachment or PDF upload counts as submission.
Do I need SA401 if I already have a personal UTR?
You may still need to register or update your partnership-related position. A personal UTR does not automatically establish that HMRC has recorded the new partnership source; check your circumstances and HMRC record.
What if the partnership UTR is not yet available?
Ask the nominated partner to confirm the partnership’s registration status and HMRC correspondence. Do not invent a UTR or enter your own in its place; use HMRC’s guidance for the correct next step.
Can an accountant register a partner with HMRC?
An authorised tax agent may be able to assist with registration. The permitted process and authorisation depend on the service and the circumstances; see HMRC’s agent registration guidance.
Can SA401 be used to change an existing partner’s details?
SA401 is principally a registration form for an individual joining a partnership. For a change to an existing record, confirm the appropriate HMRC update route rather than assuming a new SA401 is required.
Official HMRC Sources and Professional Help
The primary reference is the current HMRC SA401 registration and download page. Further official guidance covers partnership registration and deadlines, SA400, SA402 and HMRC partnership registration records.
If you need help understanding the correct partner-registration route or preparing your information, you can contact Audit Consulting Group for an initial enquiry. HMRC supplies the official form; professional assistance is optional.
For help reviewing your partner registration requirements, contact Audit Consulting Group.