SA108 Form: Capital Gains Summary (Self Assessment)
Leave your details and our team will get back to you shortly.
The HMRC SA108 form is a supplementary section of the Self Assessment tax return used to report capital gains and allowable losses from disposals of assets such as property, shares, cryptoassets and valuable personal possessions. It is submitted as part of the SA100 tax return where the Capital Gains summary pages are required.
For the 2025/26 tax year, the Capital Gains Tax (CGT) annual exempt amount for most individuals is £3,000. However, whether you need to complete SA108 depends on more than the amount of tax payable. Reporting thresholds, capital losses, relief claims and other circumstances can also make these pages necessary.
Many UK taxpayers are surprised to learn they need to fill in this form. Even if you made a loss, reporting it can help reduce future tax bills where the loss qualifies and is properly claimed. Navigating the SA108 can be tricky, but with the right guidance – and support from Audit Consulting Group – you can understand your reporting obligations and avoid unnecessary mistakes.
Explore our Personal Tax & Self Assessment Services for expert assistance with capital gains reporting, tax calculations and Self Assessment compliance.
SA108 Form 2026 – Official HMRC PDF and Notes
HMRC has published the SA108 Capital Gains summary form for the 2025/26 tax year, commonly referred to as SA108 2026, together with official completion notes.
- Download SA108 Form 2026 PDF – GOV.UK – access the official Capital Gains summary supplementary pages.
- SA108 Notes 2026 – Official HMRC Guidance – find the detailed instructions for completing the form.
- Capital Gains Tax Rates and Allowances – GOV.UK – check the applicable annual exemption and tax rates.
Important: Use the SA108 form and notes that correspond to the tax year in which the disposal took place. SA108 2026 covers disposals in the tax year from 6 April 2025 to 5 April 2026.
What Is the HMRC SA108 Form?
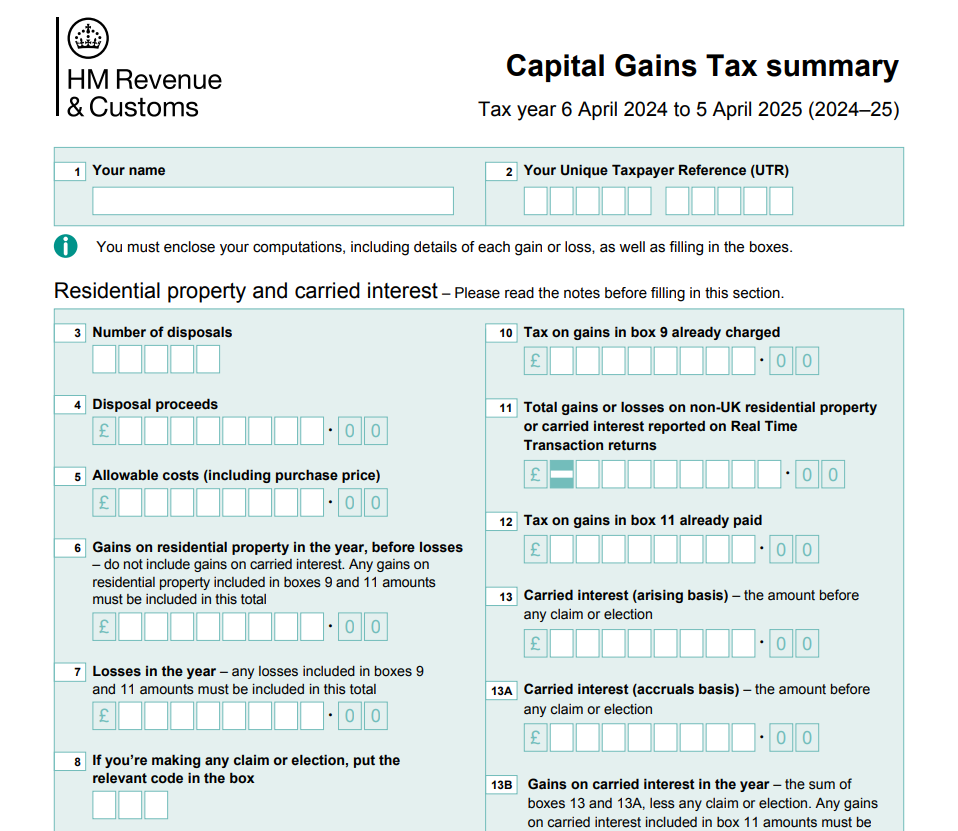
The HMRC SA108 is the Capital Gains summary section of your Self Assessment return. It provides HMRC with information about chargeable gains, allowable losses, relevant reliefs and other capital gains adjustments.
Depending on your circumstances, SA108 may cover:
- Sales of UK residential property, including second homes and buy-to-let properties, where gains are chargeable.
- Disposals of shares and securities outside tax-exempt arrangements such as ISAs.
- Taxable disposals of cryptoassets such as Bitcoin or Ethereum.
- Disposals of chargeable personal possessions, including certain jewellery, artwork and antiques, subject to applicable exemptions and special rules.
- Relevant gains or losses involving trusts and estates, where reportable on an individual’s return.
- Gains from overseas property or investments, subject to UK residence, applicable tax rules and available reliefs.
Not every asset sale creates a taxable gain. Exempt assets, reliefs, losses, acquisition costs and the taxpayer’s circumstances must be considered before deciding what to report.

Download the Current SA108 Form PDF and Notes from HMRC
For reference, the previous version is also available: SA108 Form PDF 2025 – Previous Tax Year. Do not use the 2025 version for a 2025/26 return.
When Do You Need to Complete SA108?
You may need to complete the HMRC SA108 form as part of your Self Assessment return if one or more of the relevant HMRC reporting conditions apply.
For the 2025/26 tax year, the official SA108 Notes identify circumstances including:
- You sold or disposed of chargeable assets worth more than £50,000.
- Your chargeable gains before deducting losses exceeded the £3,000 annual exempt amount.
- You have gains from an earlier year that become taxable in the current tax year.
- You want to claim an allowable capital loss or make a relevant capital gains claim or election.
- You have relevant foreign gains or remittances that must be reported under the applicable rules.
The £50,000 threshold relates to the value of chargeable disposals, not the amount of profit. It should not be confused with the £3,000 annual exempt amount.
For example, someone who sells shares for £55,000 may need to complete the Capital Gains summary pages even if their net taxable gain is below the annual exemption, provided the relevant Self Assessment reporting rules apply.
Property warning: If you dispose of UK residential property and Capital Gains Tax is due, you may need to report and pay the tax within 60 days of completion through the separate UK Property CGT reporting process. Do not assume that completing SA108 at the end of the tax year is sufficient.
Check HMRC’s UK Property Capital Gains Tax Reporting Rules.
How to Complete SA108 – Step by Step
Completing the SA108 Capital Gains summary requires accurate calculations and the correct classification of each disposal. The steps below provide a general framework for the 2025/26 tax year.
Step 1: Identify Your Chargeable Disposals
List the assets you sold, transferred, exchanged or otherwise disposed of during the tax year. Include relevant property, shares, cryptoassets and other chargeable assets.
Some transactions may count as disposals even where no cash was received, such as certain gifts or exchanges. Exemptions and special rules may apply.
Step 2: Gather Purchase and Disposal Records
Prepare the acquisition date, disposal date, purchase price, sale proceeds and evidence of allowable costs for each asset.
Keep contracts, statements, invoices, transaction histories and valuation documents. For inherited or gifted assets, the relevant market value rules may affect the calculation.
Step 3: Calculate Gains and Losses
Generally, a capital gain is calculated by deducting the allowable acquisition cost and qualifying expenses from the disposal proceeds, subject to applicable adjustments and reliefs.
For shares, cryptoassets and certain other assets, pooling, matching or special valuation rules may apply. Do not assume that every transaction can be calculated simply by subtracting the original purchase price from the sale price.
Step 4: Check Reliefs and the Annual Exempt Amount
Consider whether any reliefs apply, including Private Residence Relief, Business Asset Disposal Relief or other relevant reliefs.
For 2025/26, the annual exempt amount for most individuals is £3,000. Allowable losses and reliefs can affect the amount of gains subject to tax.
Step 5: Enter the Figures in the Correct SA108 Sections
Use the appropriate sections of the current SA108 form for residential property, other property and assets, listed or unlisted shares, cryptoassets, losses and relevant claims.
Follow the official SA108 Notes for the correct boxes. The reporting structure may change between tax years.
Step 6: Prepare Supporting Capital Gains Calculations
Maintain a clear calculation for each disposal, including proceeds, allowable costs, gains, losses and reliefs. Include supporting computations with the Self Assessment return as required by HMRC.
Step 7: Review and Submit Your Self Assessment Return
Check the completed SA108 information alongside the main SA100 return and any other relevant supplementary pages. Make sure the figures reconcile with property reports, investment statements and other tax records.
For the 2025/26 tax year, the usual deadline for online Self Assessment filing is 31 January 2027, while the usual paper filing deadline is 31 October 2026. Separate Capital Gains Tax reporting deadlines may apply to UK residential property disposals.
SA108 Online vs PDF – How Should You Submit It?
The SA108 form is not normally submitted as an independent tax return. It forms part of your Self Assessment filing.
SA108 Online Submission
Capital gains information can be included in an online Self Assessment return using an appropriate HMRC-supported filing route or compatible commercial tax software.
Some complex capital gains situations require commercial software capable of submitting the relevant supplementary pages. Check the available filing options before starting.
Check Online Self Assessment Filing Options – GOV.UK.
SA108 PDF and Paper Submission
If you submit a paper Self Assessment return, download the SA108 PDF for the correct tax year, complete the supplementary pages and include them with your SA100 return and required supporting information.
Get the Official SA108 PDF – GOV.UK.
SA108 vs Separate Capital Gains Tax Reporting
Reporting capital gains through SA108 is not the same as using the separate UK Property CGT reporting service or the real-time Capital Gains Tax service.
If you sold UK residential property, check whether the 60-day reporting rules apply. If you are already required to file Self Assessment, you may also need to include the disposal in your tax return even where it has already been reported separately.
Example of Filling in the SA108
The following examples are illustrative and use simplified figures. Actual calculations depend on the tax year, asset type, reliefs, losses, ownership and the taxpayer’s wider circumstances.
Case 1: Sale of a Buy-to-Let Property
- Jane sold her rental flat in Manchester for £300,000, which she originally bought for £220,000.
- The difference between the sale and purchase prices is £80,000.
- She incurred £10,000 in qualifying acquisition, disposal and capital improvement costs.
- Her calculated gain before losses, annual exemption and any applicable reliefs is £70,000.
- On her HMRC SA108, she reports the relevant property disposal figures and supporting capital gains calculation.
For 2025/26, if Jane qualifies for the full £3,000 annual exempt amount and has no relevant losses or other reliefs, the gain remaining after that exemption would be £67,000. The applicable CGT rate depends on her taxable income and other circumstances.
Important: Because this is a UK residential property disposal, Jane must also check whether the separate 60-day reporting and payment requirements apply.
Case 2: Share Disposals
- Tom sold £20,000 worth of company shares that he originally bought for £12,000.
- His simplified gain before allowable costs and reliefs is £8,000.
- Assuming he has no allowable losses or other gains and qualifies for the full £3,000 annual exempt amount, £5,000 of the gain remains potentially taxable.
- Tom must consider the applicable CGT rate and whether the gain needs to be reported through Self Assessment or another available reporting route.
If Tom instead made a gain below the annual exemption, the disposal would not automatically create CGT to pay. However, SA108 reporting may still be required where another reporting condition applies, including the relevant £50,000 disposal proceeds threshold.
Case 3: Cryptoasset Gains
- Sarah sold £15,000 worth of Bitcoin, originally acquired for £6,000.
- Her simplified gain is £9,000 before transaction costs and any applicable matching or pooling adjustments.
- Assuming she has no allowable losses or other gains and qualifies for the full £3,000 annual exempt amount, £6,000 remains potentially taxable.
- For 2025/26, Sarah should follow the cryptoasset reporting section and instructions in the current SA108 form and notes.
Cryptoasset calculations can become more complicated where multiple purchases, exchanges, transfers and disposals take place. Records should be reviewed carefully before filing.
Capital Gains Tax Rates and Allowances for 2025/26
For most individuals, the Capital Gains Tax annual exempt amount for 2025/26 is £3,000.
The main CGT rates for individuals in the 2025/26 tax year are:
- 18% on taxable gains falling within the available basic rate band.
- 24% on taxable gains falling above the basic rate band.
These main rates apply to most chargeable gains, including residential property gains not fully covered by Private Residence Relief. Special rules and rates may apply to particular categories of gains.
For 2025/26, gains qualifying for Business Asset Disposal Relief or Investors’ Relief may be subject to a 14% rate, provided the relevant conditions are met. From 6 April 2026, the rate for qualifying gains increases to 18%.
Your actual CGT liability depends on your taxable income, gains, allowable losses, annual exemption, reliefs and the timing of disposals.
Check Current and Historical CGT Rates – HMRC.
Common Mistakes with the HMRC SA108
- Forgetting to deduct allowable costs – qualifying acquisition, disposal and capital improvement costs may reduce the chargeable gain. Routine maintenance and other non-qualifying expenses cannot simply be deducted.
- Mixing Income Tax with CGT – rental income is generally reported through the relevant property income pages, while chargeable gains from a property disposal are reported through the appropriate capital gains route.
- Not reporting or claiming losses correctly – allowable losses may be used against gains, but the relevant claim and notification rules must be followed.
- Incorrect asset valuation – inherited assets, gifts and transactions between connected persons can involve market value rules.
- Missing cryptoasset disposals – selling, exchanging or otherwise disposing of cryptoassets may create reportable gains or losses.
- Using outdated CGT rates or allowances – the correct tax treatment depends on the disposal date and tax year.
- Missing the 60-day UK property deadline – some residential property disposals must be reported and any tax due paid before the annual Self Assessment deadline.
- Submitting SA108 without supporting calculations – HMRC expects appropriate capital gains computations to accompany the return.
Key Recommendations for Completing SA108
Keep detailed records – retain purchase contracts, receipts, valuations, investment statements and sale documents.
Use HMRC’s worksheets and notes – the current SA108 guidance helps identify the appropriate sections and calculations.
Check the reporting thresholds – a disposal may need to be reported even where no CGT is ultimately payable.
Do not forget foreign property and investments – overseas disposals may be subject to UK reporting rules depending on your residence and tax circumstances.
Review capital losses – allowable losses should be identified and claimed within the relevant time limits.
Check UK residential property deadlines – the separate reporting process may apply before your Self Assessment return is due.
Seek professional help – particularly where multiple assets, cryptoassets, mixed-use properties, overseas disposals or complex reliefs are involved.
FAQ – HMRC SA108
Do I need to fill in SA108 if I sold my main home?
Usually not if the entire gain qualifies for Private Residence Relief and no other reporting condition applies. However, partial relief, periods of letting, changes in use or other circumstances may create a reportable gain.
How much tax will I pay on gains?
For the 2025/26 tax year, the main CGT rates for individuals are 18% and 24%, depending on taxable income and the amount of chargeable gains. The annual exempt amount for most individuals is £3,000. Special rates and reliefs may apply to certain gains.
Can I report losses?
Yes. Allowable capital losses can reduce chargeable gains, and unused losses may be carried forward where the relevant rules are satisfied. Losses must be notified or claimed within the applicable time limits.
Do I need to declare crypto gains?
Cryptoasset disposals may create taxable gains or allowable losses. Whether you need to report them depends on your total gains, disposal proceeds and other reporting circumstances. The 2025/26 SA108 form includes specific reporting provisions for cryptoassets.
What happens if I do not file SA108?
If you are required to report capital gains and fail to do so correctly, HMRC may charge interest or penalties depending on the circumstances. Incorrect or incomplete reporting may also result in enquiries and additional tax assessments.
Where can I download the SA108 form for 2026?
You can download the official SA108 2026 PDF and the corresponding completion notes from the HMRC Capital Gains summary page on GOV.UK.
Can I complete SA108 online?
Yes, capital gains information can be submitted as part of an appropriate online Self Assessment return, including through compatible commercial tax software where required. SA108 is not a standalone online tax return.
Do I need SA108 if my gains are below £3,000?
Not necessarily. However, you may still need to complete SA108 if another reporting condition applies, such as the relevant £50,000 chargeable disposal proceeds threshold or a capital loss claim.
Is SA108 the same as SA100?
No. SA100 is the main individual Self Assessment tax return. SA108 contains supplementary pages for reporting capital gains and losses as part of that return.
Do I need to report a property sale within 60 days?
If you sell UK residential property and CGT is due, the separate 60-day reporting and payment requirements may apply. You may also need to include the disposal in your Self Assessment return.
Why Work with Audit Consulting Group?
The HMRC SA108 is one of the more detailed supplementary sections of Self Assessment. Errors in capital gains calculations or reporting can be expensive. At Audit Consulting Group, we help clients:
- Accurately calculate and declare chargeable gains and allowable losses.
- Review eligibility for reliefs such as Private Residence Relief, Business Asset Disposal Relief and rollover relief.
- Prepare cryptoasset capital gains calculations using the applicable HMRC rules.
- Identify and claim allowable capital losses correctly.
- Prepare supporting computations and relevant Self Assessment disclosures.
- Review UK property CGT reporting requirements and filing deadlines.
- Reduce the risk of avoidable errors, penalties and HMRC enquiries.
Contact Audit Consulting Group today — we can help you complete your HMRC SA108 form accurately and efficiently, giving you greater confidence in your tax reporting.
SA108 Capital Gains Tax Form Services Cost UK
Submit the SA108 form in the UK with expert capital gains tax support. We help individuals report capital gains accurately as part of Self Assessment. Our SA108 services include reviewing disposal records, preparing calculations, identifying applicable reliefs and supporting HMRC compliance at a clear, agreed price.
Service Cost Estimation
Select the service category below to calculate the estimated cost of either accounting & tax services or forms and submissions.
Select Required Services / Forms
Select one or more services/forms to receive an accurate cost estimate. You can adjust your selection at any stage.
How would you like to engage our services?
Please select whether you require a one-off service or ongoing monthly support.
Contract Duration
Your cost estimate
Apply now and get 10% OFF
Submit your request today and receive an exclusive 10% discount on your selected service.
All prices are estimates. To receive a personalised quote, please fill out the form or contact us.
Ready to get started?
Get professional support from experienced UK accountants