Leave your details and our team will get back to you shortly.
Certificate of Residence to Claim Tax Relief Abroad – HMRC Application Help
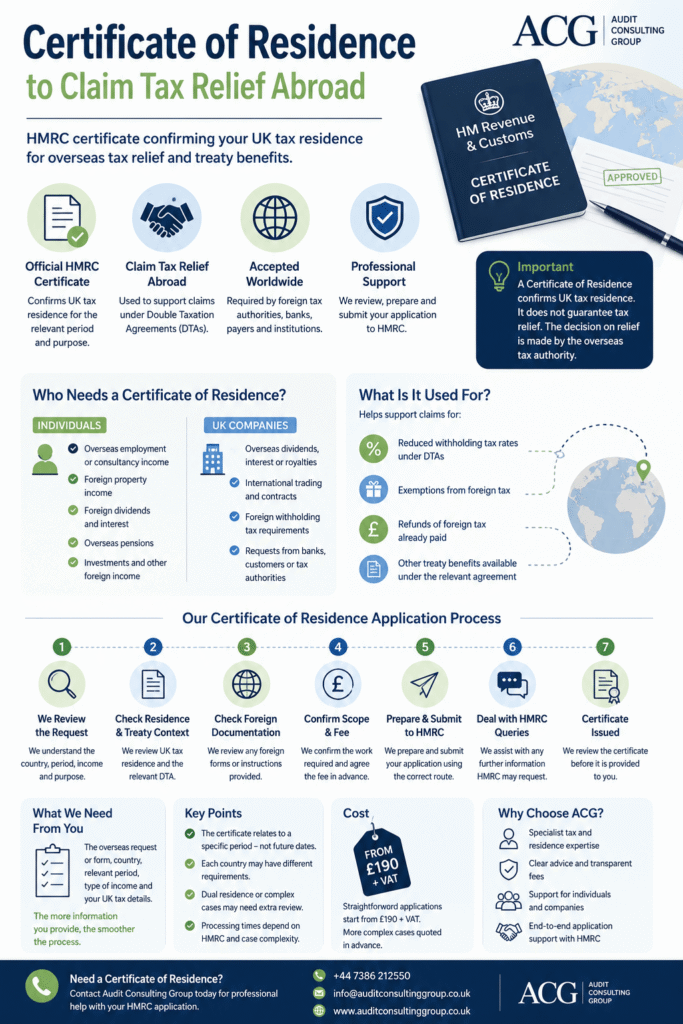
Need a UK Certificate of Residence (sometimes called a certificate of residency) for an overseas tax authority, foreign payer or withholding-tax claim? Audit Consulting Group (ACG) helps UK-resident individuals, sole traders, companies and other eligible applicants prepare an HMRC Certificate of Residence application. Our professional support starts from £190 + VAT for straightforward cases, with the scope agreed before work begins.
A Certificate of Residence can help support a claim for tax relief under a Double Taxation Agreement (DTA). HMRC decides whether it can issue the certificate; the overseas authority or payer decides whether a tax exemption, reduced withholding rate or refund is available. Send us the foreign request, country, relevant period and income type so we can check which document and application route may be appropriate.
UK Certificate of Residence: Quick Facts
| Question | Answer |
|---|---|
| Who issues it? | HM Revenue & Customs (HMRC). |
| What is it for? | Evidence of UK tax residence in support of an applicable tax-treaty claim. |
| Who can apply? | Eligible individuals, sole traders, companies and other organisations; special rules apply to partnerships, trusts and pension schemes. |
| How do I apply? | Through HMRC’s current online service, or by post if you cannot apply online. |
| Can an accountant help? | Yes. An appropriately authorised agent can apply on your behalf. |
| ACG service fee | From £190 + VAT for straightforward application support; the quotation confirms inclusions. |
| Is foreign tax relief guaranteed? | No. The overseas jurisdiction determines entitlement under its rules and the applicable treaty. |
UK Certificate of Residence Application Support
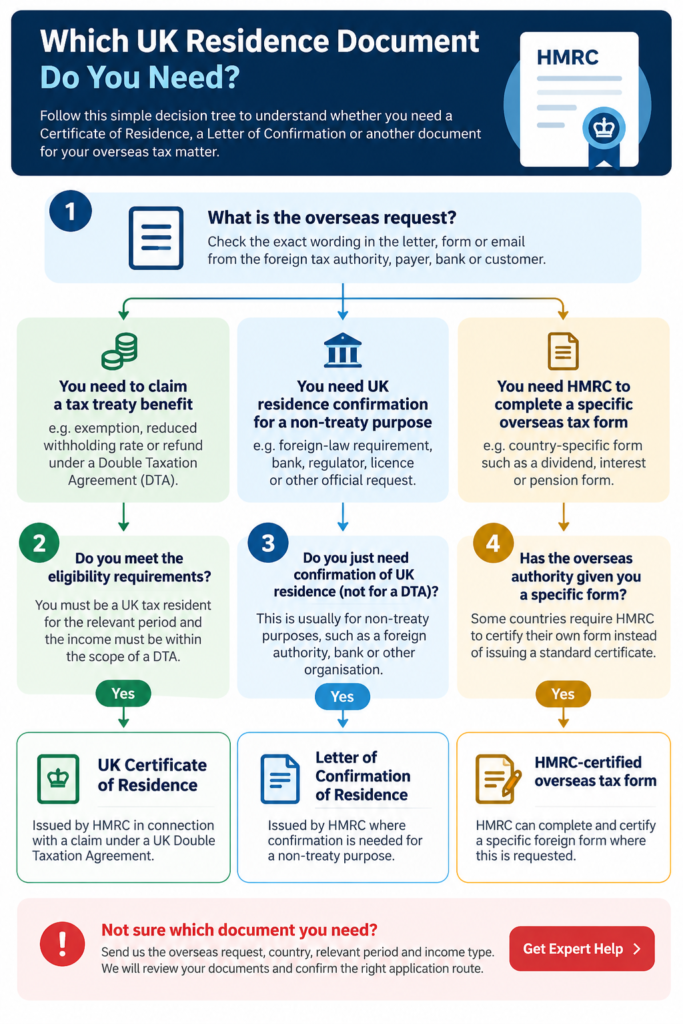
Not every request for proof of UK tax residence requires the same document. A foreign tax authority may accept a standard HMRC Certificate of Residence, require a specific overseas tax form to be certified, or ask for a Letter of Confirmation of Residence instead. Applying for the wrong document can delay a payment or foreign tax claim.
ACG reviews the original request, applicant, country, tax period, overseas income and treaty purpose before confirming the work. Depending on the agreed engagement, our service may include reviewing relevant UK residence information, checking foreign documentation, preparing the HMRC application and assisting with follow-up correspondence. More complex treaty analysis or overseas tax filings are separately scoped.
Before applying: send us the letter, form or email from the overseas authority, bank, customer or payer. The recipient’s exact wording is often the most useful starting point.
What Is a UK Certificate of Residence?
A Certificate of Residence (CoR), also described as a UK tax residency certificate, tax residency certificate UK, certificate of tax residence UK or HMRC tax residence certificate, is evidence issued by HMRC following its checks of UK residence for the relevant tax-treaty purpose and period.
It is commonly requested when a UK resident earns foreign dividends, interest, royalties, pensions, employment income, consultancy fees or other overseas income and needs to demonstrate UK residence to claim a benefit under a Double Taxation Agreement.
The certificate does not itself grant relief, prove eligibility for every treaty benefit or automatically reclaim tax. The relevant treaty, income category, beneficial ownership conditions where applicable and foreign authority’s procedures all matter.
Who May Need a Certificate of Residence?
You may need a UK Certificate of Residence for tax purposes if you are a UK resident receiving income from abroad, a contractor paid by an overseas customer, a shareholder receiving foreign dividends, a landlord with property overseas, a pension recipient or a UK business asked to provide formal residence evidence.
HMRC’s online service also supports applications from specified organisations, including partnerships, trusts, charities, pension schemes, public bodies and collective investment schemes. Being able to use the application service does not automatically mean that the applicant is entitled to treaty benefits. In particular, the tax treatment of partnerships differs from that of companies and individuals.
Certificate of Residence vs Letter of Confirmation of Residence
The right document depends on the purpose of the foreign request. HMRC generally issues a Certificate of Residence in connection with a claim under a UK Double Taxation Agreement. A Letter of Confirmation of Residence is generally relevant where confirmation is needed for a different purpose, such as a non-treaty foreign-law requirement.
| Overseas requirement | What to check |
|---|---|
| Claim a benefit under a UK tax treaty | HMRC Certificate of Residence, subject to eligibility. |
| Confirm UK tax residence for a non-treaty purpose | HMRC Letter of Confirmation of Residence. |
| Foreign authority provides its own form | Whether HMRC must certify the foreign form and what supporting evidence is required. |
| Bank or payer requests “proof of residence” | Clarify the recipient’s exact purpose and accepted wording before applying. |
For further explanation, see HMRC’s guidance on Letters of Confirmation.
Certificate of Tax Residence for Individuals and Sole Traders
For an individual, eligibility begins with the UK tax residence position for the period requested. Depending on the circumstances, HMRC may need information relevant to the Statutory Residence Test (SRT), UK day counts, ties to the UK, arrival or departure dates and any split-year treatment.
If you have not filed a relevant Self Assessment return for a period from 6 April 2013 onwards, HMRC may require the number of days you spent in the UK, an explanation of why you meet the SRT if you spent fewer than 183 days in the UK, and relevant arrival, departure or split-year dates. Spending 183 days in the UK is not the only way an individual can be UK resident.
Common Reasons Individuals Request a Certificate
- Overseas employment or consultancy income: a foreign employer or customer requests residence evidence before considering treaty treatment.
- Foreign dividends and interest: an overseas company, bank or investment platform asks for proof of UK tax residence.
- Foreign property income: a UK resident receives rental income from property abroad and needs documentation for the foreign tax process.
- Overseas pensions: a foreign pension provider or tax authority requests residence confirmation.
- International contracting: an overseas payer withholds tax from professional fees and requires residence evidence for a possible reduction or reclaim.
What ACG Reviews for an Individual Application
We establish the country, period, income type, reason for the certificate and the documents requested by the foreign recipient. Where appropriate, we review UK residence information and identify whether the request raises a more complex dual-residence or treaty issue. A Certificate of Residence is not a substitute for a full residence or cross-border tax opinion where one is needed.
Certificate of Residence for UK Limited Companies
A UK limited company may require an HMRC Certificate of Residence for a limited company (also called a company Certificate of Residence) when it receives foreign royalties, dividends, interest, consultancy fees or other overseas payments, or when a foreign tax authority requests residence evidence in connection with withholding tax.
UK incorporation is generally a basis for UK company residence, subject to statutory exceptions. Central management and control can also be relevant. Where a company is regarded as resident in two countries, the applicable treaty and its residence provisions may change the analysis; UK incorporation alone should not be treated as proof of entitlement to every treaty benefit.
Newly Incorporated Companies
Where a company has not yet filed a Corporation Tax Self Assessment return, HMRC requires additional details, including the name and address of each director and shareholder and an explanation of why the company believes it is UK tax resident. We review these requirements before preparing the request.
What ACG Reviews for a Company Application
Depending on the case, we review the company name and registration details, Corporation Tax UTR, country, relevant accounting period, type of overseas income, foreign payer’s instructions and any management or dual-residence concerns. Complex international structures may require separate specialist analysis.
Certificates of Residence for Partnerships, Trusts and Other Organisations
HMRC’s application service includes partnerships, trusts, charities, pension schemes and certain other organisations, but their residence and treaty-entitlement rules are not identical.
UK partnerships: most partnerships are tax-transparent and are not themselves treaty-resident under most UK DTAs. HMRC may provide confirmation concerning the eligible UK-resident partners instead. A limited number of treaties have special provisions. The application should identify the partners’ residence status and the relevant treaty requirement rather than assuming the partnership itself qualifies.
Trusts and pension schemes: additional residence, authorisation and documentary rules may apply. For registered pension schemes, HMRC sets out particular agent-authorisation arrangements. The correct route should be checked for the organisation involved.
See HMRC’s partnership guidance and its Certificate of Residence manual.
How to Apply for a Certificate of Residence from HMRC
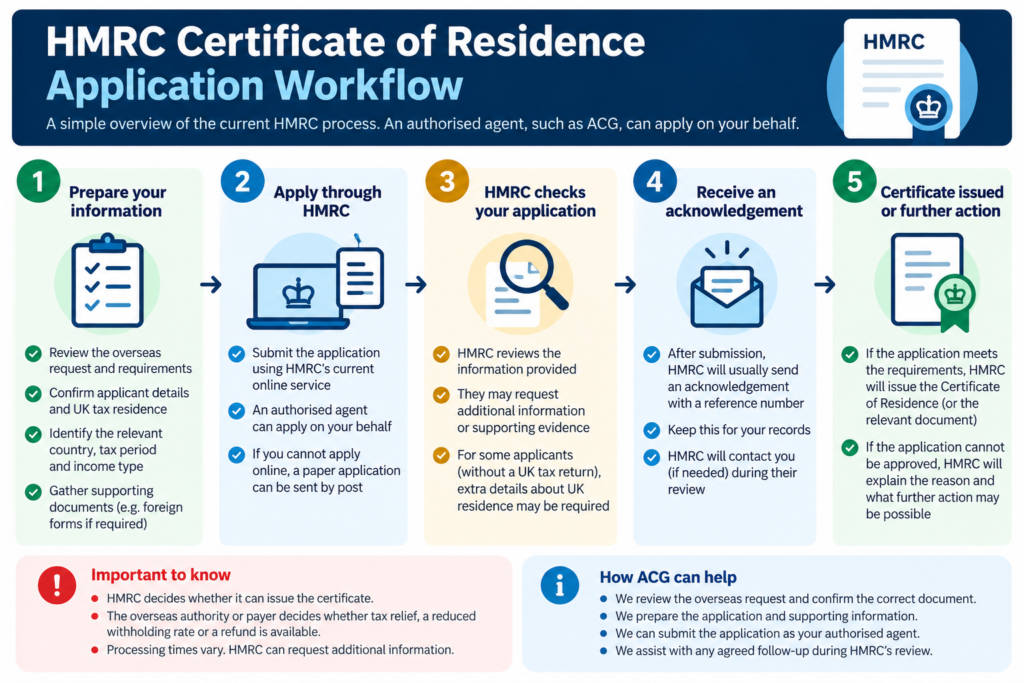
To request a Certificate of Residence in the UK, first check the country, period and treaty purpose. HMRC provides a current online Certificate of Residence and Letter of Confirmation application service. Older searches for RES1 form, HMRC RES1, HMRC RES1 online service or RES1 online service may refer to earlier terminology; use the current GOV.UK instructions rather than relying on an outdated form link.
- Confirm the purpose: identify the country, relevant Double Taxation Agreement, income type, required period and foreign recipient’s wording.
- Gather information: prepare the applicant details, relevant tax information, supporting residence evidence and any overseas form.
- Apply through HMRC: submit through the current online service yourself or through an appropriately authorised agent. If you cannot apply online, HMRC provides a postal alternative with addresses by applicant type.
- Respond to questions: HMRC may ask for further details before deciding whether it can issue the certificate or letter.
- Check the document: review the issued name, country, period and wording against the original overseas request before forwarding it.
You can apply yourself; hiring an accountant is not a legal requirement merely to use the service. ACG can assist where the foreign instructions, supporting documents or residence position require professional review.
Documents Needed for a UK Certificate of Residence Application
The exact requirements depend on the applicant and the purpose. HMRC generally needs to know the country, treaty, income type and period involved, together with information supporting the residence position.
| Core information | Additional information in some cases |
|---|---|
| Applicant’s full name or organisation details | Authorised agent details and appropriate authority |
| Country and reason for the request | Foreign tax authority’s form or requested wording |
| Relevant income and treaty claim | Beneficial ownership or subject-to-tax information where required by the treaty |
| Exact tax year or accounting period | UK days, Statutory Residence Test and split-year details for relevant individuals |
| Original overseas request or correspondence | Director/shareholder details and residence explanation for newly incorporated companies |
What Individuals Should Send ACG
As a starting point, send your name, contact details, country, period, foreign income type and the overseas request. We may then ask for your National Insurance number, UTR where applicable, residence history or relevant travel dates through an appropriate secure process.
What Companies Should Send ACG
Provide the company name, registration number, Corporation Tax UTR where available, country, period, income or payment details and the foreign recipient’s request. Where relevant, we may need director, shareholder or management information.
Application checklist: country, period, income, treaty purpose, applicant details and any foreign form. HMRC does not accept a request for a future date under its general application requirements; special Large Business pre-order arrangements are separately described by HMRC.
Using a Certificate of Residence to Claim Tax Relief Abroad
A major reason to apply for a certificate of tax residence in the UK is to support a foreign tax claim under a Double Taxation Agreement. A Certificate of Residence to avoid double taxation can provide evidence for treaty relief, but the treaty and overseas authority determine whether that relief applies. Treaties may provide reduced withholding tax rates, exemptions or other mechanisms to prevent or relieve double taxation, depending on the treaty and type of income.
Foreign dividends and interest: a bank, company or investment platform may request evidence of UK residence before considering a treaty rate. Royalties and consultancy payments: a foreign payer may deduct withholding tax unless the appropriate conditions and documentation are satisfied. Overseas pensions and employment income: different treaty articles and foreign administrative procedures may apply.
Sometimes a certificate is supplied before a payment is made; in other cases, tax is withheld first and the recipient must make a separate foreign refund claim. A Certificate of Residence may be necessary supporting evidence, but it does not replace the foreign application or establish that a refund must be granted.
Where beneficial ownership, dual residence, permanent establishment, income classification or treaty interpretation is disputed, specialist cross-border advice may be required beyond standard certificate preparation.
Does the Foreign Tax Authority Require Its Own Form?
Some overseas authorities accept a standard HMRC Certificate of Residence. Others require a country-specific certificate of tax residence form or a separate treaty-relief document to be certified by HMRC. The required wording and period may differ from the standard certificate.
Send us the original form or instructions before the application begins. We can assess whether a standard certificate appears appropriate or whether the foreign form needs to accompany the HMRC request. HMRC’s current guidance explains that foreign forms and supporting documents can be uploaded or sent as part of the relevant application route.
How ACG Handles Your Certificate of Residence Application
- Initial review: we check the foreign request, country, period, income and applicant.
- Residence and treaty context: we identify the relevant UK residence information and whether specialist advice may be needed.
- Foreign forms: we review any additional certificate wording or overseas authority requirements.
- Quotation: we confirm the agreed scope, fee and whether submission and HMRC follow-up are included.
- Preparation: we assemble the application information and supporting documents.
- Submission and HMRC queries: where included and appropriately authorised, we assist with the current HMRC route and agreed correspondence.
- Document review: we help check the issued certificate against the original requirement where included in the engagement.
Who Is Responsible for What?
| Party | Responsibility |
|---|---|
| Client | Provide accurate information, supporting documents and any required authority. |
| ACG | Perform the preparation, submission or follow-up work expressly agreed in the engagement. |
| HMRC | Review the residence and treaty information and decide whether to issue the certificate or letter. |
| Overseas authority or payer | Determine whether the evidence satisfies its requirements and whether foreign tax relief is available. |
What Happens After HMRC Issues the Certificate?
Check the certificate’s name, country, period and wording. You may then need to provide it to an overseas customer, pension provider, bank or tax authority, attach it to a foreign treaty-relief form or use it as evidence in a foreign tax refund claim.
If an overseas recipient asks for an HMRC Certificate of Residence apostille or a Certificate of Residence UK apostille, confirm exactly which document must be legalised and why. An apostille is not a universal requirement for UK Certificates of Residence, and obtaining one is a separate process from HMRC issuing the certificate. Foreign tax advice, foreign filings and legalisation are not assumed to be included in a standard HMRC application fee.
How Long Does It Take to Get a Certificate of Residence?
HMRC processing times vary with workload, the applicant, the period, the complexity of the residence position and any requests for further information. We do not promise a fixed HMRC issue date or guarantee an outcome.
ACG’s preparation time is confirmed after reviewing the documentation and agreed scope. If an overseas authority or payer has given you a deadline, provide it at the start so we can identify timing risks. A deadline imposed overseas does not require HMRC to issue a certificate by that date.
Certificate of Residence Application Service Cost UK
Our professional fee for straightforward UK Certificate of Residence application support starts from £190 + VAT. This is an ACG professional service fee, not a statement that HMRC charges that amount.
The final quotation depends on the applicant, number of countries or periods, foreign forms, residence complexity, treaty questions and whether submission or HMRC correspondence is included. Foreign tax reclaims, specialist opinions, legalisation and other third-party services may be quoted separately. We confirm the scope before substantive work begins.
Service Cost Estimation
Select the service category below to calculate the estimated cost of either accounting & tax services or forms and submissions.
Select Required Services / Forms
Select one or more services/forms to receive an accurate cost estimate. You can adjust your selection at any stage.
How would you like to engage our services?
Please select whether you require a one-off service or ongoing monthly support.
Contract Duration
Your cost estimate
Apply now and get 10% OFF
Submit your request today and receive an exclusive 10% discount on your selected service.
All prices are estimates. To receive a personalised quote, please fill out the form or contact us.
Ready to get started?
Get professional support from experienced UK accountants
Common Certificate of Residence Application Problems
- Wrong document: the recipient needs a Letter of Confirmation or certified foreign form rather than a standard CoR.
- Wrong period: the dates in the application do not match the overseas request.
- Incomplete residence information: the relevant tax return has not been filed or additional SRT evidence is needed.
- Dual residence: another country also regards the applicant as resident and treaty rules need analysis.
- Assumed treaty entitlement: UK residence alone does not establish eligibility under every treaty article.
- Partnership confusion: the partnership is assumed to be treaty-resident when the position may depend on its UK-resident partners.
- Foreign claim omitted: the applicant assumes the HMRC certificate automatically reduces or refunds overseas tax.
Practical Scenarios: Overseas Income and UK Residence
The following are illustrative examples, not verified ACG client cases or promises of particular HMRC or overseas tax outcomes.
UK Consultant Receiving Income From Overseas
A UK-based consultant is asked for residence evidence before an overseas customer considers withholding-tax treatment. The first step is to check the payer’s country, payment type, relevant period and treaty instructions. Where a CoR is appropriate, the HMRC application can be prepared with the correct details; any foreign tax relief remains a separate decision.
UK Company Receiving Overseas Royalties
A UK limited company receives royalty payments subject to foreign withholding tax. The company must establish which treaty provision and documents the payer requires, whether its residence position is straightforward and whether a foreign form must be certified. Obtaining the certificate does not itself process a foreign tax refund.
UK Resident Receiving a Foreign Pension
An individual living in the UK is asked to prove UK tax residence to an overseas pension provider. The relevant period, UK residence evidence, pension type and foreign authority’s form are checked. The pension provider or overseas authority then applies its own procedures and the applicable treaty.
Why Choose Audit Consulting Group?
Our approach begins with the actual overseas request rather than assuming every applicant needs the same document. We review the intended purpose, period, income and relevant UK residence information, explain the likely application route and identify when a more specialised tax review is necessary.
We support individuals and companies with the agreed HMRC Certificate of Residence preparation work, foreign document checks and, where included, submission or correspondence. We also explain what is not covered: HMRC controls the certificate decision, and foreign authorities control foreign tax relief.
For a straightforward case you can apply to HMRC yourself. If the foreign request is unclear, there are multiple jurisdictions or your residence position is complex, professional assistance may help you avoid preparing the wrong application.
Frequently Asked Questions About UK Certificates of Residence
What is a UK Certificate of Residence?
It is evidence issued by HMRC, following its checks, of UK tax residence for the relevant tax-treaty purpose and period.
How do I apply for a certificate of tax residence in the UK?
Use HMRC’s current online Certificate of Residence service or its postal alternative if you cannot apply online. You will need the country, period, income and treaty purpose, plus any required supporting details.
How to get a tax residence certificate in the UK?
To get a tax residence certificate, confirm which overseas country needs proof of residence and for what tax period, then use HMRC’s current application service. An authorised agent can help with a certificate of tax residence application if the request involves foreign forms, company residence or treaty questions.
Is the HMRC RES1 form still used?
RES1 remains a historic search term. Follow the current GOV.UK Certificate of Residence and Letter of Confirmation guidance for the applicable online or postal route.
Can an accountant apply for a Certificate of Residence for me?
Yes. An appropriately authorised agent can apply on your behalf using the relevant HMRC agent access and authority arrangements.
Can an individual or sole trader obtain a UK tax residency certificate?
Potentially, yes, where the residence and treaty requirements are met. Additional Statutory Residence Test information may be required if a relevant Self Assessment return has not been filed.
Can a UK limited company apply?
Yes, subject to the relevant residence and treaty conditions. Newly incorporated companies without a filed Corporation Tax return must provide additional information to HMRC.
Can a UK partnership get a Certificate of Residence?
Partnerships can use HMRC’s application service, but most UK partnerships are not themselves treaty-resident under most UK DTAs. HMRC may instead confirm the residence of eligible UK-resident partners, subject to the treaty.
What is the difference between a Certificate of Residence and a Letter of Confirmation?
A CoR generally supports a claim for treaty benefits. A Letter of Confirmation generally confirms UK residence for another purpose. Check what the foreign recipient requires.
Can I request a Certificate of Residence for a previous year?
A request may relate to an earlier period, provided HMRC can assess the residence position and purpose of the request.
Can I request a Certificate of Residence for a future date?
HMRC’s general application requirements do not allow requests for a future date. Specific Large Business pre-order arrangements are described separately in HMRC’s guidance.
Can I request certificates for more than one country?
Potentially. The countries’ treaty provisions, periods and document requirements must be checked individually. HMRC may request a spreadsheet for bulk applications.
What if I am tax resident in two countries?
Dual residence can require analysis of domestic rules and the relevant treaty’s residence article before the correct certificate or claim can be determined.
Can a company with overseas directors get a Certificate of Residence?
Potentially. Overseas directors do not automatically determine company residence. UK incorporation, management arrangements and any relevant treaty provisions may need to be assessed.
Does a Certificate of Residence reduce foreign withholding tax?
It may support a reduced treaty rate where the treaty and foreign rules allow it, but the certificate alone does not guarantee a reduction.
Can a Certificate of Residence help reclaim foreign tax already paid?
It may provide evidence for a foreign refund claim. The reclaim usually follows a separate procedure set by the foreign jurisdiction.
How long is a Certificate of Residence valid?
It relates to the residence period confirmed by HMRC. Whether a foreign authority accepts it for a later transaction or period depends on that recipient’s rules.
How long does HMRC take to issue a Certificate of Residence?
Processing times vary. HMRC may ask for additional information, and ACG cannot guarantee a particular issue date.
Do I need to be up to date with my UK tax returns?
Your filing and tax records may be relevant to HMRC’s checks. If a return for the requested period has not yet been filed, HMRC may require further residence information.
What if the foreign authority has its own tax residence form?
Send the form with the original request. HMRC may need to certify the overseas form or receive it as supporting documentation.
Can a UK Certificate of Residence be apostilled?
Legalisation or an apostille may be needed if the overseas recipient specifically requires it. This is not a standard requirement for every country or certificate.
How much does ACG charge for Certificate of Residence help?
Our professional support starts from £190 + VAT for straightforward applications. We confirm what is included and quote separately for more complex work.
What should I send ACG first?
Send the foreign authority’s letter, form or email, the country, relevant period, income type, applicant details and any deadline. We can then assess the appropriate service and quotation.
Official HMRC Certificate of Residence Guidance
For current application requirements, see HMRC: Apply for a Certificate of Residence or Letter of Confirmation. HMRC’s International Manual on Certificates of Residence explains specialist cases. Where treaty relief is involved, consult the relevant agreement in the UK tax treaties collection.
Ready to Apply for a UK Certificate of Residence?
If you need a Certificate of Residence to claim tax relief abroad, send Audit Consulting Group the original overseas request and a brief explanation of the country, income and period involved. We can review the appropriate application scope, explain what supporting information is needed and confirm the professional fee before substantive work begins.
Call +44 7386 212550, email info@auditconsultinggroup.co.uk, or contact Audit Consulting Group online.
Already received a foreign tax form or residence request? Send it to us first so we can check which HMRC document is appropriate.