SA109 Form HMRC: 2025/26 PDF, Notes and Filing Guide
Leave your details and our team will get back to you shortly.
The SA109 form is the HMRC supplementary page used with a Self Assessment tax return when particular UK residence, split-year, non-residence or foreign income and gains (FIG) regime details need to be reported or claimed. It is not a separate tax return. If you are looking for an HMRC SA109 form, start with the correct tax-year edition and check whether these pages apply to your circumstances before completing them.
This guide explains the 2025/26 SA109 pages, how they relate to the SA100 tax return, which information to prepare and how to file them. The official HMRC form and notes take precedence over general examples on this page.
Official SA109 Form and Notes for 2025/26
Get the SA109 form 2026 PDF, the SA109 notes 2026 and the official instructions from HMRC’s SA109 publication page. The 2026 publication relates to the 2025/26 tax year, from 6 April 2025 to 5 April 2026. Do not confuse the publication year with the tax year. Select the matching edition of the SA109 form download and SA109 guidance notes.
For an SA109 PDF download, use the official GOV.UK publication. The SA109 2026 notes should be read alongside the form. The downloadable paper form is not, by itself, a method of submitting the supplementary pages online.
SA109 Quick Facts
| Item | 2025/26 position |
|---|---|
| Form | SA109 — supplementary Self Assessment pages |
| Authority | HM Revenue & Customs (HMRC) |
| Official title | Residence and foreign income and gains (FIG) regime etc |
| Period | 6 April 2025 to 5 April 2026 |
| Main return | SA100; SA109 is completed where applicable |
| Main purpose | Relevant residence and FIG-related declarations or claims |
| Paper source | Official GOV.UK SA109 publication and notes |
| Filing | With the Self Assessment return, through a suitable online route or paper return |
What Is the SA109 Form?
What is SA109? The SA109 UK tax form, sometimes written SA 109 or SA-109, consists of supplementary pages for a UK Self Assessment return. HMRC uses the SA109 residence section to collect relevant residence-status and associated claim information, including matters that can affect the treatment of income and gains. The precise questions depend on the tax-year edition.
An SA109 tax return is a common search expression, but technically SA109 is part of the Self Assessment return rather than a standalone return. You complete the main SA100 and any additional pages that apply. The phrase residence remittance basis etc notes may still appear in older search results or document descriptions; use the current 2025/26 notes for the current rules.
Download SA109 form PDF 2025-2026
Who Needs SA109 — and Who Does Not?
You may need the SA109 residence pages if your Self Assessment position involves a UK residence or non-residence declaration, a split-year claim, a relevant personal allowance claim as a non-resident, or a claim/reporting matter covered by the 2025/26 residence and FIG pages. Whether you need them depends on the actual facts and HMRC’s current instructions.
A person with overseas income does not automatically need SA109. Foreign income can also involve SA106; the correct combination depends on residence, the nature of the income and any relief or regime claim. Equally, a person living abroad does not automatically need a non resident declaration form called SA109: first establish whether a Self Assessment return is required and which pages apply.
SA109, SA106 or P85: Which Route Applies?
This is a frequent source of confusion. SA109 addresses residence and specified claims within Self Assessment. SA106 is used for relevant foreign income and gains reporting. P85 is a separate HMRC process for some people leaving the UK who need to tell HMRC and may seek an Income Tax refund. One does not automatically replace another.
For example, an individual can have both a residence issue and foreign income to report, meaning SA109 and SA106 may both be relevant to the same SA100. Conversely, a person leaving the UK who is not filing a return may need to examine P85 rather than assume SA109 is a stand-alone departure notice. See Self Assessment forms for the ACG resource category.
Three Practical SA109 Scenarios
Illustrative example 1 — leaving the UK part-way through the tax year. Priya moves overseas and continues to receive some UK income. She checks her residence position under the statutory residence test and whether split-year treatment applies. If she needs a Self Assessment return, SA109 may be relevant to the residence claim. Moving abroad alone does not prove entitlement to split-year treatment.
Illustrative example 2 — UK resident with overseas dividends. Oliver remains UK resident and receives foreign dividends. He must consider the reporting of foreign income, potentially through SA106. The existence of dividends alone does not establish a need for SA109.
Illustrative example 3 — newly UK resident with earlier overseas income. Nadia is reviewing the 2025/26 FIG regime. She must check the statutory qualifying conditions and what claims are available, rather than relying on pre-April 2025 remittance-basis explanations. These examples are fictional and are not ACG client cases.
SA109 2025/26: FIG Changes and Older Remittance Basis Claims
The tax rules changed from 6 April 2025. The previous remittance basis was replaced for new foreign income and gains by a new foreign income and gains (FIG) regime for qualifying individuals, with separate transitional rules potentially relevant to pre-6 April 2025 amounts. This does not mean every person with foreign income can claim FIG treatment. Qualifying individuals generally need to be within their first four years of UK tax residence after at least ten consecutive tax years of non-UK residence, subject to the full conditions. A claim may affect entitlement to certain allowances, so do not assess it in isolation from the rest of the return. Review HMRC Helpsheet HS266 and HS264 transitional guidance.
| Issue | 2024/25 | 2025/26 |
|---|---|---|
| Broad regime context | Historic remittance-basis rules may be relevant | New FIG regime and transitional provisions may be relevant |
| SA109 edition | Use the 2024/25 pages and notes | Use the 2025/26 pages and notes |
| Practical warning | Do not copy an old claim into a later return | Check qualifying conditions and current instructions |
What Is Included in the SA109 Pages?
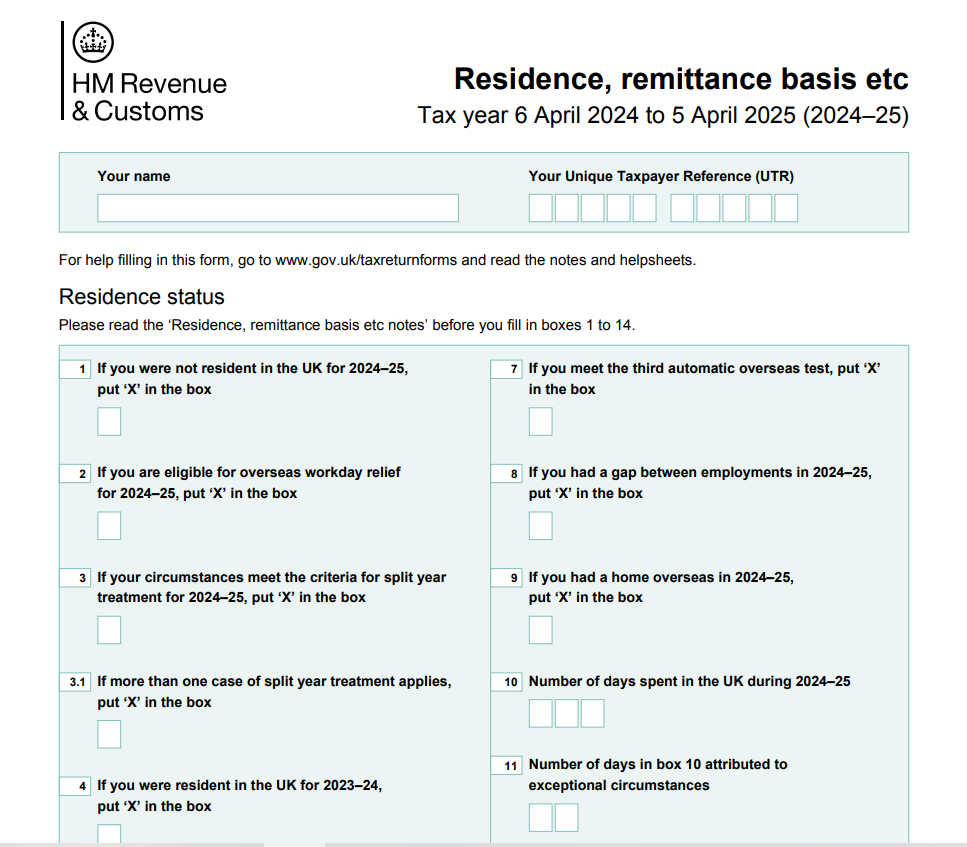
The SA109 residence form contains tax-year-specific questions concerning residence status and relevant claims. Do not rely on an old SA109 sample, SA109 example or online list of box numbers when filling in the 2025/26 edition. The official HMRC SA109 notes explain which entries are needed and the evidence behind them.
The pages address UK residence and non-residence, split-year treatment, relevant personal allowance claims and FIG-related declarations. The applicable entries depend on your circumstances; follow the 2026 form and notes rather than an older example.
A box number can change or its meaning can differ between editions. The 2026 notes were updated on 28 September 2026, including the explanation relating to boxes 28 and 29. Always use the latest published notes for those entries.
What Information and Records Do You Need?
Prepare the information needed to support your residence position and any claim. This is different from saying HMRC requires every document to be attached to the return.
| Information category | Why it matters | Useful preparation record |
|---|---|---|
| UK arrival and departure dates | Residence and split-year analysis | Travel calendar and tickets |
| Days spent in the UK | Statutory residence test considerations | Day-count working paper |
| Work and family ties | Relevant to some residence-test outcomes | Work schedule, accommodation details |
| Income and gains | May affect other Self Assessment pages | Tax statements and income summaries |
| Basis for specific claims | HMRC may ask for supporting information | Claim calculations and contemporaneous records |
These are preparation examples, not a universal list of mandatory attachments. Where facts are disputed, obtain advice before choosing a residence status or claim.
How to Complete SA109
First, confirm that you need a Self Assessment return and the 2025/26 SA109 supplementary pages. Second, use the official SA109 form guidance and the correct edition of the notes. Third, determine your residence position using the applicable statutory rules rather than assuming residence from nationality or an address. Fourth, complete only the applicable parts and reconcile claims with the main SA100 and other supplementary pages. Finally, reconcile the SA109 claims with the main SA100 tax calculation and any SA106 foreign pages, SA108 capital gains pages or other applicable supplementary pages. Check that each claim is supported by the relevant facts and that the same amounts have not been treated inconsistently across pages.
If you are checking how to complete SA109, use the current form and its accompanying notes rather than a box-by-box example from a previous tax year. The safe approach is to use the actual 2025/26 HMRC notes for field-level entries, because the form and the underlying FIG rules are version-sensitive.
How to Submit SA109 Online or by Post
If you want to file SA109 online, check that your chosen Self Assessment software supports the SA109 supplementary pages for the relevant tax year. A downloadable PDF cannot simply be attached to the standard HMRC online return as a substitute for supported supplementary-page filing. Confirm the provider’s current capabilities before you submit SA109.
For paper filing, obtain the correct SA100 and SA109 editions, follow the official signing and postal instructions, and submit the completed return through the applicable HMRC paper route. People searching where to send SA109, SA109 postal address or SA109 where to send should check the address in the current official return instructions, rather than rely on an address copied from an older blog post.
| Route | What to do | Common pitfall |
|---|---|---|
| Online through compatible software | Prepare SA100 and supported SA109 entries, validate and file | Assuming HMRC’s basic online interface accepts any SA109 PDF |
| Paper Self Assessment return | Complete and send SA100 with applicable SA109 pages | Using a different tax year’s pages or an old address |
SA109 Deadlines for the 2025/26 Tax Year
SA109 follows the applicable Self Assessment return filing deadline, rather than a separate universal SA109-only deadline. For a typical 2025/26 return, the standard paper filing deadline is 31 October 2026, and the standard online filing deadline is 31 January 2027. The standard balancing payment deadline is also 31 January 2027 where applicable, but filing and payment are different obligations. Exceptions can apply, including special notice-to-file circumstances; check the deadline that HMRC has given you.
| Obligation | Standard date for 2025/26 | Distinction |
|---|---|---|
| Paper Self Assessment return | 31 October 2026 | Return filing, including relevant supplementary pages |
| Online Self Assessment return | 31 January 2027 | Return filing through an eligible online route |
| Balancing payment | 31 January 2027 | Payment obligation; may differ from tax due under other arrangements |
What Happens After You File?
HMRC receives the Self Assessment return and may process it, calculate tax or ask for clarification where entries or claims require review. Keep the return, relevant calculations and supporting records. Do not assume that submitting SA109 means HMRC has formally approved every residence or FIG claim. There is no guaranteed SA109-specific processing time stated here.
If you discover a mismatch between SA109 and SA100, or HMRC queries a residence position, respond using the official correspondence and Self Assessment correction processes. The correct next step depends on whether the return is still amendable and whether HMRC has opened an enquiry.
Common SA109 Mistakes
- Downloading SA109 2025 or older SA109 notes PDF for a 2025/26 return simply because a search result looks familiar.
- Treating overseas income as automatic proof that SA109 is required, without considering SA106 and residence facts.
- Treating SA109 as a standalone return or a generic non resident declaration form.
- Claiming split-year treatment without establishing the qualifying statutory case.
- Copying old remittance-basis advice into a post-6 April 2025 FIG claim.
- Assuming that a PDF download is equivalent to an SA109 online submission.
- Failing to reconcile the SA109 entries with the main SA100 and other supplementary pages.
How to Amend SA109 or Deal With Late Filing
If you submitted incorrect SA109 information, the correction usually needs to be considered as part of the Self Assessment return amendment process, rather than sending a new isolated SA109 page without context. HMRC’s amendment time limits and methods depend on the relevant return and circumstances. If an amendment is no longer available, another formal route may be necessary; do not assume the same procedure always applies.
If the return is late, check whether you have a filing obligation, whether HMRC issued a notice to file, what deadline applied and whether penalties have been charged. A penalty dispute and a return correction are different processes.
Related Forms: SA100, SA106, SA108 and P85
| Form | Main role | When it may be relevant |
|---|---|---|
| SA100 | Main Self Assessment tax return | Where a Self Assessment return is required |
| SA109 | Residence and relevant FIG-related supplementary pages | Where the relevant residence or claim details apply |
| SA106 | Foreign supplementary pages | Where foreign income or gains must be reported |
| SA108 | Capital gains supplementary pages | Where chargeable gains or relevant FIG-related reporting needs these pages |
| P85 | Leaving-the-UK notification/refund process | Certain departures where P85 is appropriate |
Completing SA109 Yourself vs Professional Support
You can use the official HMRC form and notes to prepare the supplementary pages yourself if you can establish the relevant facts and understand the claims. Professional help may be useful where residence changes during the year, split-year treatment is uncertain, several countries are involved, or FIG and transitional rules affect the return.
The SA109 form is an HMRC document; any paid review or tax-return preparation is a separate professional service. ACG can be contacted to discuss whether assistance is appropriate, but this page does not assert a specific fee, guaranteed result or filing authority.
SA109 Frequently Asked Questions
Do I need SA109 if I have foreign income?
Not automatically. You may need SA106 for foreign income, while SA109 depends on residence and other relevant claim circumstances.
Can I submit SA109 online?
Potentially, using compatible Self Assessment software that supports the relevant supplementary pages. A downloaded SA109 PDF is not itself an online submission route.
Where can I download the SA109 2025/26 form and notes?
Use the official GOV.UK SA109 publication and choose the 2025/26 edition and notes issued in 2026.
Can SA109 be filed separately from SA100?
SA109 is a supplementary page of a Self Assessment return, not a standalone return. Any correction to a filed return should follow the applicable HMRC amendment process.
Is SA109 the same as P85 or SA106?
No. SA109 concerns residence and specified claims; SA106 concerns foreign income reporting; P85 is a separate process for certain people leaving the UK.
Does a FIG claim remove the need to check other supplementary pages?
No. Check the treatment and reporting of each relevant source of income or gains and reconcile any FIG claim with SA100 and the applicable supplementary pages.
Does SA109 still use the remittance basis in 2025/26?
The historic remittance basis was replaced from 6 April 2025 by the FIG regime for qualifying individuals, alongside transitional rules. Check the 2025/26 SA109 notes and current HMRC helpsheets before making a claim.
Official HMRC Sources
- SA109 form and current notes.
- HS266: Foreign income and gains (FIG) regime, 2026.
- HS264: Pre-6 April 2025 foreign income and gains and temporary repatriation facility.
- HMRC Self Assessment information.
- HMRC commercial software suppliers.
Need Help Understanding SA109?
If your UK residence position, split-year treatment or FIG-related reporting is unclear, you can contact Audit Consulting Group to discuss the information you have and what support may be appropriate. The official HMRC form and notes remain available for anyone preparing their return independently.
SA109 Residency Status Form Services Cost UK
Get professional support with the SA109 form in the UK to declare residency and domicile status. We help ensure correct completion of residency information for Self Assessment. Our SA109 services reduce compliance risks and reporting errors.
Service Cost Estimation
Select the service category below to calculate the estimated cost of either accounting & tax services or forms and submissions.
Select Required Services / Forms
Select one or more services/forms to receive an accurate cost estimate. You can adjust your selection at any stage.
How would you like to engage our services?
Please select whether you require a one-off service or ongoing monthly support.
Contract Duration
Your cost estimate
Apply now and get 10% OFF
Submit your request today and receive an exclusive 10% discount on your selected service.
All prices are estimates. To receive a personalised quote, please fill out the form or contact us.
Ready to get started?
Get professional support from experienced UK accountants