P50 Form HMRC: Claim Tax Back After Stopping Work
Leave your details and our team will get back to you shortly.
The P50 form is an HMRC claim for people who have stopped working and may have overpaid Income Tax through PAYE in the current tax year. If you have received your final pay and meet HMRC’s conditions, you may be able to claim without waiting until the tax year ends. Leaving employment does not, by itself, guarantee a refund or mean that P50 is the right form.
This guide explains who can use the HMRC P50 form, how to claim online or by post, what to do without a P45, and how to check the next steps.
Official HMRC P50 Form: Online Claim or Print and Post
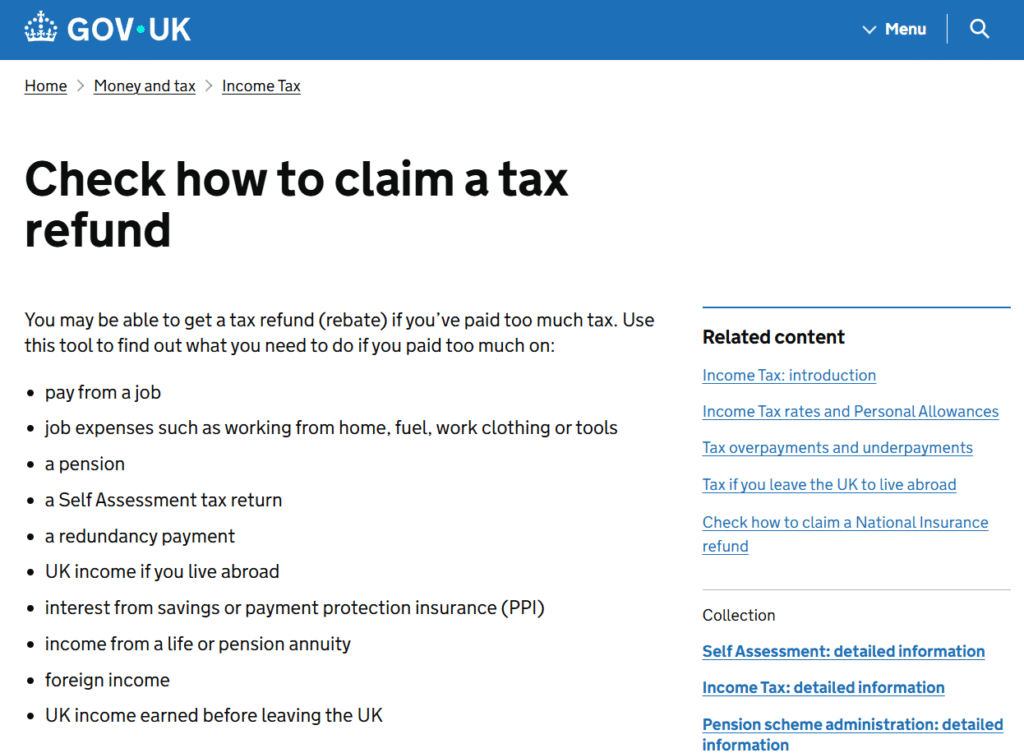
Open the official P50 form and online claim on GOV.UK.
If you are searching for the GOV.UK P50 form or want to know how to get a P50 form from HMRC, use the official link above. It provides access to the current claim process and instructions for people who need to submit their claim by post.
HMRC offers an online claim through its sign-in service and an interactive form you can complete on screen, then print, sign and post. Completing the postal form on screen is not the same as submitting a claim electronically. Always use the official page rather than an old third-party P50 form PDF download.
P50 Form Quick Facts
| Item | Details |
|---|---|
| Form | P50 — claiming back Income Tax after stopping work |
| Issued by | HM Revenue & Customs (HMRC) |
| Tax | Income Tax deducted under PAYE |
| Period | Current UK tax year (6 April to 5 April) |
| Claim routes | Online through GOV.UK or interactive print-and-post form |
| P45 | Useful, but you can explain why Parts 2 and 3 are unavailable |
| Government fee | No HMRC application fee stated |
What Is the HMRC P50 Form?
The P50 tax form, also known as the P50 HMRC form, is used to ask HM Revenue & Customs to review Income Tax deducted through PAYE after you have stopped working. You must meet HMRC’s conditions before using this claim route.
PAYE tax is calculated as you are paid; if you leave part-way through the tax year and have less taxable income than anticipated, some tax already deducted may be repayable.
For example, a person who stops working in July and has no further taxable earnings may have paid more PAYE tax than their eventual annual liability. However, having overpaid PAYE is different from qualifying to claim through P50 immediately: your next job, benefits, pension and other income can affect which route HMRC expects you to use.
Who Can Use a P50 Form?
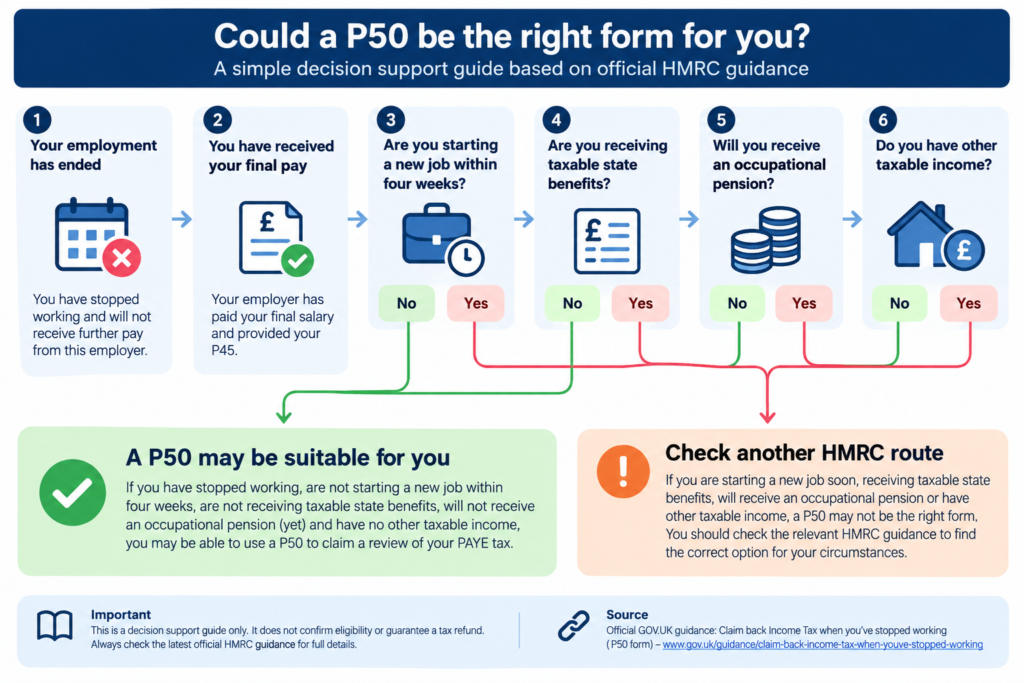
HMRC describes circumstances in which a person who has stopped working and received their final payment can claim. Examples include being unemployed for at least four weeks without claiming taxable state benefits, returning to full-time education, retiring without receiving an occupational pension, or not expecting to work again. These are alternative circumstances to consider, not a checklist requiring every example to apply.
Before making an HMRC P50 tax refund claim, consider any employment expected shortly, taxable state benefits, occupational pension payments, self-employment profits and other taxable income. If you remain registered with an employment agency, HMRC may expect the agency to provide your final pay and tax details first.
When P50 May Not Be the Correct Route
- Starting a new job within four weeks: the new employer may deal with overpaid tax through PAYE.
- Receiving taxable state benefits: another HMRC process may apply.
- Receiving an occupational pension: the pension provider may be able to adjust your tax.
- Refund after a pension withdrawal: check the relevant pension refund form, such as P55 or P50Z, rather than assuming P50 applies.
- Earlier tax year or Self Assessment: the repayment may need to be dealt with through another tax refund or return process.
- Leaving the UK: check whether P85 is more appropriate.
Do I Qualify for a P50 Tax Refund?
Start by checking whether your employment has ended and your final pay has been received. Next consider whether you will start another job within four weeks, receive taxable benefits or a pension, or have other taxable income. If any of these apply, check another HMRC route before submitting P50. If none applies and you meet HMRC’s current conditions, P50 may be suitable — HMRC will still decide whether any repayment is due.
Three Practical P50 Examples
These are hypothetical examples, not actual client cases or guarantees of eligibility.
These situations illustrate when a person might claim tax back through P50 and when another PAYE route may be more appropriate.
Career Break After Leaving Employment
Anna leaves her job in July, receives her final pay and plans several months away from work. If she has no taxable benefits or other circumstances affecting the claim, P50 may be worth checking.
Moving to Another Employer
James leaves one employer and starts another three weeks later. Rather than immediately claiming on P50, he should check how his new employer will deal with his PAYE record.
Retiring Without an Occupational Pension
David stops working and does not receive an occupational pension. P50 may be relevant, but HMRC still needs to consider his other income and tax position.
What Information Do You Need for the HMRC P50 Form?
Have the following information ready, where relevant to the questions in the current HMRC service:
- National Insurance number and personal details.
- Former employer’s PAYE reference, if available.
- Employment leaving date, final pay and PAYE tax deducted.
- Details from your P45, where available.
- Other taxable income, including self-employment profits, pension payments, taxable benefits or property income where applicable.
Useful records: keep your final payslip, P45 and other income records to check the amounts you enter. These are helpful supporting records, not necessarily mandatory attachments in every claim.
Can You Submit P50 Without a P45?
Yes. HMRC asks whether you have Parts 2 and 3 of your P45 and allows you to explain why they are unavailable. The absence of those parts does not automatically prevent a P50 claim. If your employer has not provided a P45, explain this accurately and use the information you do have; do not invent missing pay or tax figures.
How to Complete and Submit P50 HMRC
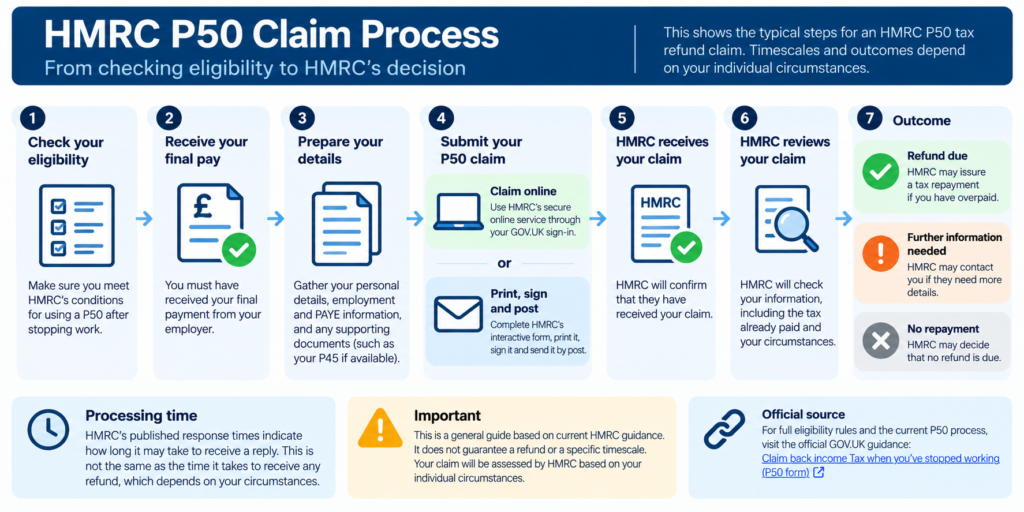
To claim tax back using P50, first check whether this is the correct HMRC route for your circumstances. An HMRC P50 claim to recover overpaid tax requires accurate employment, PAYE and other income information.
- Check eligibility: read the current HMRC P50 guidance and confirm that the form suits your circumstances.
- Wait for final pay: make sure your last employment payment has been received.
- Gather details: have your NI number, PAYE figures, P45 information and other income records ready.
- Complete the claim: answer all relevant questions and disclose taxable income accurately.
- Choose submission: use the official online service, or complete, print, sign and post the interactive form.
- Keep a record: retain any acknowledgement, copy or postal evidence available.
P50 Online vs Print and Post — Which Route Should You Use?
| Feature | Online P50 claim | Print-and-post P50 |
|---|---|---|
| Where to start | Official GOV.UK P50 page | Same GOV.UK page |
| Sign-in | Required for online service | Alternative if you cannot sign in |
| How to submit | Electronically | Print, sign and post to HMRC |
| Important point | Follow confirmation shown by the service | Completing on screen does not submit the claim |
Looking for an HMRC P50 form download or HMRC P50 form PDF? Use the official GOV.UK service rather than an outdated third-party document. You can submit a claim online or use HMRC’s interactive form to complete, print, sign and post your claim. Check the current instructions before submitting.
When Can You Submit a P50 Claim?
Check that you have received your final pay and meet one of HMRC’s qualifying circumstances. Being unemployed for at least four weeks is one example, not a universal waiting period for every applicant. P50 is for relevant claims in the current tax year; in October 2026 that is 2026/27. For a previous tax year, check the appropriate alternative route.
There is no single P50 filing deadline equivalent to the Self Assessment return deadline.
How Long Does a P50 Tax Refund Take?
HMRC’s P50 guidance says a reply may take 14 days after it receives a completed claim. That is a reply-time indication, not a promise that your tax refund will be paid within 14 days. The overall time can be longer if HMRC requests more information or needs to check your tax record.
Wondering how long a P50 takes to process? HMRC’s published reply-time guidance should not be confused with the time required to issue any repayment. The actual outcome depends on the information provided and HMRC’s review.
If you are searching for how long HMRC takes to process P50, distinguish the date HMRC receives the claim, its review and decision, and any subsequent repayment.
What Happens After You Submit the P50 Claim?
HMRC checks your claim against its tax records. It may confirm that a repayment is due, ask for more information or decide that no repayment is payable at that point. Follow the payment instructions on the current HMRC page; do not assume that the reply date is the payment date.
What If Your P50 Claim Is Delayed or Incorrect?
If you have not received a reply after HMRC’s indicated period, check the latest official guidance and use HMRC’s Income Tax contact information when appropriate. Keep any postal proof or online acknowledgement.
If you want to check your HMRC P50 claim status, start with the current GOV.UK response-time guidance. For questions about a submitted claim, use HMRC’s official Income Tax contact details. Do not assume that a separate P50 tracking service is available.
If you notice a mistake, ask HMRC how to correct it rather than assuming a second P50 claim is the correct procedure. If you disagree with HMRC’s calculation, compare it with your payslips, P45 and other taxable income before contacting HMRC. Do not assume there is a separate P50-specific appeal form.
P50 vs P45, P55, P50Z, P53, P53Z and P85
| Form | Purpose | When to check it |
|---|---|---|
| P50 | Claim overpaid Income Tax after stopping work | Eligible current-year employment situation |
| P45 | Employment leaving and PAYE record | When leaving a job; not a refund claim |
| P55 | Refund after certain flexible pension withdrawals | Tax deducted from qualifying pension access |
| P50Z | Refund in certain full flexible pension access circumstances | Specific pension withdrawal conditions |
| P53 / P53Z | Refund routes for certain small pension lump sums | Small pension payments and relevant circumstances |
| P85 | Notify HMRC of leaving the UK and address tax position | Leaving or having left the UK |
P50Z is not a replacement for P50. If your refund relates to pension withdrawals, use the HMRC pension tax refund checker and its pension refund guidance. You can also read our P55 HMRC guide. If you are leaving the UK, check HMRC’s P85 guidance.
Common Mistakes With the P50 Tax Refund Form
- Applying before final pay: HMRC may not yet have the complete PAYE figures.
- Assuming P45 is mandatory: HMRC allows an explanation when Parts 2 and 3 are missing.
- Ignoring other taxable income: pension income, taxable benefits and other earnings may affect the claim.
- Using P50 for a pension withdrawal: a pension-specific form may be required.
- Not posting the paper form: completing it on screen alone does not submit it.
- Assuming a refund is guaranteed: HMRC must first establish whether tax was overpaid.
P50 Form vs Professional Tax Refund Support
You can make an eligible P50 HMRC claim yourself using GOV.UK. Professional support is optional and separate from the official process. It may be useful if you have several employers, inconsistent PAYE records, multiple sources of income or uncertainty about whether P50 or another route applies.
FAQ — HMRC P50 Form
Can I claim a P50 tax refund without a P45?
Yes. HMRC lets you explain why Parts 2 and 3 of your P45 are unavailable. You must still provide accurate pay and tax information.
Can I fill out and submit a P50 form online?
Yes. GOV.UK provides an electronic P50 claim. There is also an interactive form that must be printed, signed and posted.
Can I use P50 if I start another job?
If you expect to start a new job within four weeks, HMRC generally expects the new employer to deal with the PAYE position rather than an immediate P50 claim.
How long does HMRC take to reply to a P50 claim?
HMRC indicates that a reply may take 14 days after receiving a completed claim. This is not a guaranteed refund payment date.
Can I claim P50 if I receive Universal Credit?
Universal Credit is generally tax-free, but P50 eligibility depends on your full circumstances, including any other taxable benefits or income. Check the current HMRC conditions.
What if my final pay was in a previous tax year?
P50 is designed for eligible claims in the current tax year. Check HMRC’s previous-year tax refund guidance or your Self Assessment position instead.
Is P50 the same as P50Z?
No. P50 concerns certain refunds after stopping work; P50Z relates to specific flexible pension access circumstances.
Official HMRC Sources
- Claim back Income Tax when you’ve stopped working (P50)
- Check which pension tax refund route applies
- Claim a tax refund on your pension by post
- P85: Leaving the UK
HMRC guidance reviewed for this editorial update: 14 October 2026. Always check the official GOV.UK page for current rules and submission instructions.
Need Help With Your P50 Tax Refund?
If you are unsure whether P50 applies, your PAYE figures appear incorrect or you have other taxable income, Audit Consulting Group can discuss your circumstances and possible next steps. Professional assistance is optional; eligible applicants can use the HMRC service directly.