£38k After Tax UK: £38,000 Take-Home Pay & Salary Guide in 2026/27
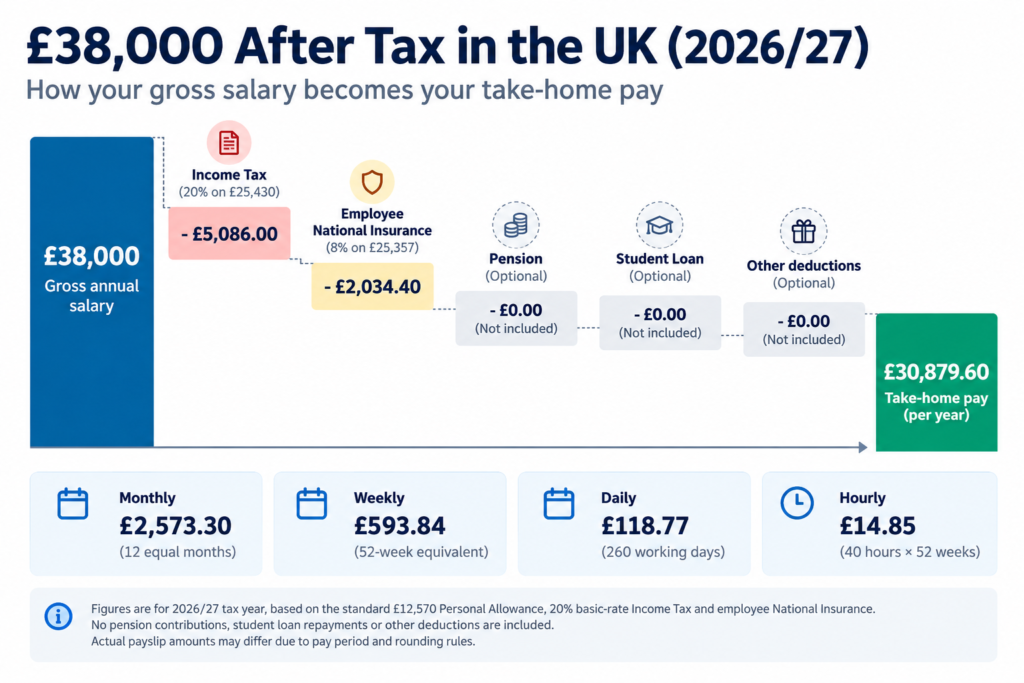
How much is £38k after tax in the UK? On a £38,000 gross annual salary, standard 2026/27 PAYE deductions in England, Wales or Northern Ireland leave approximately £30,879.60 a year, or £2,573.30 a month. This assumes the standard £12,570 Personal Allowance, ordinary employee National Insurance (category A), no student loan repayments, no pension contributions, no taxable benefits and no other adjustments. Scotland has different Income Tax bands, so its take-home figure is different.
For anyone comparing a job offer or checking a payslip, this guide gives a £38k take home pay UK estimate, explains the £38,000 take-home pay calculation and shows which deductions can change the result. It is a gross-to-net estimate, not an individual payroll quotation.
How Much Is £38,000 After Tax in the UK?
| Measure | Gross pay | After Income Tax and employee NI |
|---|---|---|
| Per year | £38,000.00 | £30,879.60 |
| Per month (12 equal months) | £3,166.67 | £2,573.30 |
| Per week (52-week equivalent) | £730.77 | £593.84 |
| Per day (260 working days) | £146.15 | £118.77 |
| Per hour (40 hours × 52 weeks) | £18.27 | £14.85 |
The monthly, weekly, daily and hourly figures are annualised equivalents; actual payslip amounts may differ because PAYE and National Insurance are calculated through payroll using the relevant pay period and rounding rules. The daily figure assumes five working days per week. The hourly figure assumes 2,080 paid hours a year, not that you work every week without leave.
This 38000 take home pay UK estimate excludes pension and student loan deductions. For a personalised estimate, use the official HMRC Income Tax estimator.
£38k After Tax per Month, Week, Day and Hour
For a £38k monthly salary after tax comparison, £38,000 gross a year works out at £2,573.30 net per month under the standard assumptions above. If your contract pays £38k a year in 12 equal monthly instalments, your gross monthly salary is approximately £3,166.67. Income Tax and NI reduce that figure before any further payroll deductions.
If you are asking what is £38k a year monthly after tax, the answer is approximately £2,573.30 before pension and loan deductions. The £38k salary monthly take-home figure is an annualised average, not a guaranteed payslip amount; weekly and hourly equivalents depend on your contracted hours.
| Contracted weekly hours | Gross hourly equivalent | Indicative net hourly equivalent* |
|---|---|---|
| 35 hours | £20.88 | £16.97 |
| 37.5 hours | £19.49 | £15.84 |
| 40 hours | £18.27 | £14.85 |
The net hourly figure is £30,879.60 divided by annual contracted hours, not an hourly PAYE tax calculation. The familiar £19.49 figure is appropriate for 37.5 hours a week, not 40 hours. A different working pattern, unpaid leave or irregular hours changes the comparison.
For budgeting, use the amount you actually receive in your bank account, especially if your employer deducts pension contributions, student loans or other authorised amounts. The £38k after tax UK per month estimate is not a guarantee of identical monthly net pay.
How Is a £38,000 Salary After Tax Calculated?
The standard £38k after tax and NI calculation starts with your annual gross earnings. For 2026/27, the standard UK Personal Allowance is £12,570. The remaining £25,430 falls entirely within the 20% basic-rate Income Tax band for England, Wales and Northern Ireland. Standard employee Class 1 NI is 8% on earnings between the primary threshold and upper earnings limit. HMRC’s Income Tax rates and 2026/27 employer payroll thresholds provide the source rules.
| Step | Calculation | Annual amount |
|---|---|---|
| Gross salary | Contractual annual salary | £38,000.00 |
| Standard Personal Allowance | Tax-free amount | £12,570.00 |
| Income subject to basic-rate tax | £38,000 − £12,570 | £25,430.00 |
| Income Tax | £25,430 × 20% | £5,086.00 |
| Employee NI | (£38,000 − £12,570) × 8% | £2,034.40 |
| Estimated net salary | £38,000 − £5,086 − £2,034.40 | £30,879.60 |
The combined annual deduction in this simplified £38k salary after tax example is £7,120.40. That does not mean you pay a flat 28% tax rate: the calculation applies separate rates to income above relevant thresholds. Employer National Insurance is a cost to the employer and is not deducted as employee NI from this £38k salary.
This example describes ordinary employment under PAYE. A self-employed person’s taxable profits, Class 4 NI and payment arrangements follow different rules. Similarly, a second job, non-standard tax code, salary sacrifice, taxable benefits or pension contributions can change the result.
£38k After Tax in Scotland vs England, Wales and Northern Ireland
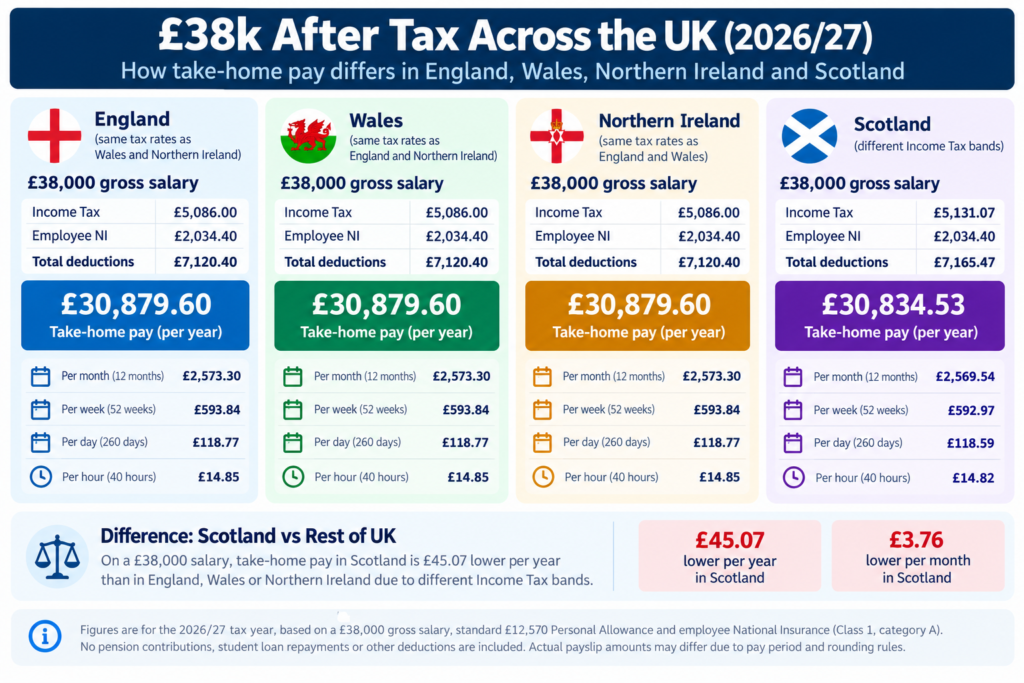
£38k after tax Scotland cannot be calculated by simply copying the England figure. Scottish residents generally pay Scottish Income Tax rates on wages, while employee NI follows UK-wide rules. The 2026/27 Scottish bands include a 19% starter rate, 20% basic rate and 21% intermediate rate at this income level. See HMRC’s Scottish Income Tax bands.
| 2026/27 annual £38,000 salary | England, Wales and Northern Ireland | Scotland |
|---|---|---|
| Income Tax | £5,086.00 | £5,131.07 |
| Employee NI (standard category A) | £2,034.40 | £2,034.40 |
| Net per year | £30,879.60 | £30,834.53 |
| Net per month, annualised | £2,573.30 | £2,569.54 |
| Difference in annual net pay | — | £45.07 less |
Scottish worked example: (£3,967 × 19%) + (£12,989 × 20%) + (£8,474 × 21%) = £5,131.07 of Income Tax. Subtract this and £2,034.40 employee NI from £38,000 to get £30,834.53. This assumes the standard allowance and no additional adjustments. Scottish taxpayer status depends on the applicable residence rules, not merely the location of an employer’s office.
£38k After Tax With a Student Loan
If you have a student loan, 38k after tax and student loan will be lower than the headline take-home amount. Repayments depend on the plan, income threshold, pay frequency and whether a postgraduate loan also applies. For 2026/27, undergraduate Plan 1, 2, 4 and 5 repayments are generally 9% of relevant pay above the plan threshold; postgraduate loan repayments are generally 6% above their separate threshold. GOV.UK lists the current repayment thresholds.
| Student loan scenario at £38,000 | 2026/27 annual threshold | Illustrative annual repayment* | Illustrative annual take-home after loan* |
|---|---|---|---|
| No student loan | — | £0.00 | £30,879.60 |
| Plan 1 | £26,900 | £999.00 | £29,880.60 |
| Plan 2 | £29,385 | £775.35 | £30,104.25 |
| Plan 4 | £33,795 | £378.45 | £30,501.15 |
| Plan 5 | £25,000 | £1,170.00 | £29,709.60 |
| Postgraduate Loan only | £21,000 | £1,020.00 | £29,859.60 |
These are illustrative annualised calculations using the full-year threshold and unrounded 9%/6% arithmetic — not guaranteed deductions on actual payslips. Payroll calculates repayments using the relevant pay period and its rounding rules. The table starts from the England/Wales/Northern Ireland standard net figure; for Scotland, use the Scottish net figure first.
For example, 38k after tax with student loan Plan 2 means an illustrative £775.35 annual loan repayment, or approximately £64.61 per month on an annualised basis. If you also repay a postgraduate loan, it may be collected alongside the applicable undergraduate plan; do not simply add together several undergraduate plans. Confirm your loan type with the Student Loans Company and your employer’s payroll record.
A bonus can cause a student loan deduction in a particular pay period even when your annual earnings are close to a threshold. Salary sacrifice may change the relevant payroll earnings; an ordinary pension contribution does not necessarily do so.
£38k After Tax With Pension Contributions
Your 38k after tax and pension amount depends on how contributions are calculated and which workplace pension arrangement applies. The £30,879.60 standard net estimate above assumes no employee pension deduction. Do not subtract an arbitrary 5% of the full salary without checking the scheme’s pensionable-pay definition, employer contribution and tax relief method.
| Pension method | How employee contributions are handled | Income Tax effect | Employee NI effect |
|---|---|---|---|
| Net pay arrangement | Deducted before PAYE Income Tax | Usually reduces taxable pay | Normally NI remains based on gross earnings before the pension deduction |
| Relief at source | Employee pays from after-tax pay; pension provider adds basic-rate relief | Relief added to pension; further relief may depend on tax circumstances | Normally does not reduce NI |
| Salary sacrifice | Employee agrees to lower contractual cash pay in exchange for employer pension contribution | Usually reduces taxable employment pay | May reduce employee NI, subject to arrangement and rules |
HMRC explains the two ordinary workplace pension relief methods. Salary sacrifice has separate rules and must reflect a genuine arrangement; GOV.UK explains how workplace pensions affect pay.
Illustrative example, not a payroll quotation: if a qualifying net pay pension arrangement deducts £1,900 annually (5% of the full £38,000 salary, purely as an assumption), the Income Tax reduction at a 20% marginal rate is £380. Your spendable pay would fall by approximately £1,520 relative to the no-pension example, while standard employee NI would ordinarily remain unchanged. In a relief-at-source scheme, the same £1,900 gross pension contribution could instead involve an employee payment of £1,520 and a £380 provider tax-relief addition. These examples are not interchangeable with salary sacrifice and may differ if contributions are based on qualifying earnings rather than full salary.
For salary sacrifice, check the contractual reduction, pension contributions, effects on other benefits and student loan treatment before estimating the final take-home pay. Do not assume every scheme offers salary sacrifice or that a lower net salary means the pension is worse value.
Why Is My Actual £38k Take-Home Pay Different?
An online £38,000 after tax UK per month estimate is useful for comparing offers, but your payslip is the better record of what you were actually paid. Use the following checks before assuming payroll is wrong.
| Check | What can change | What to review |
|---|---|---|
| Tax code | Personal Allowance or collection of tax adjustments | Code on payslip and HMRC Personal Tax Account |
| Scottish taxpayer status | Income Tax bands | Scottish S prefix where applicable |
| Pension scheme | Employee contribution and relief method | Scheme documents and pensionable-pay basis |
| Student or postgraduate loan | Additional payroll deduction | Plan and pay-period threshold |
| Bonuses or overtime | Taxable pay and NI for the period | Gross pay and year-to-date totals |
| NI category | NI rate or exemption | Category letter on payslip |
| Benefits or deductions | Taxable benefits or agreed deductions | Payroll and employment documents |
| Start date / irregular pay | PAYE cumulative position and NI period | First payslip, P45, payroll frequency |
A tax code such as 1257L commonly corresponds to the standard Personal Allowance, but it is not proof that your total tax position is correct. An emergency or non-cumulative code can cause temporary differences. If the numbers look wrong, compare your payslip against HMRC’s current-year Income Tax estimator and ask payroll to explain the deductions. If necessary, check the tax code with HMRC.
Is £38k a Good Salary in the UK or London?
Leave your details and our team will get back to you shortly.
Whether £38k is a good salary in the UK after tax depends more on your household and costs than on a universal benchmark. A standard take-home amount of around £2,573 per month may cover very different lifestyles depending on housing costs, childcare, travel, debt repayments and whether the household has one or two earners.
If you search for 38k after tax London, the basic PAYE calculation is generally the same as elsewhere in England. London does not have a separate ordinary employment Income Tax band. What may differ substantially is the cost of housing and commuting. Compare your expected £38k net salary with your actual budget rather than assuming that gross pay alone measures affordability.
A practical monthly budget starts with £2,573.30 before pension and loan deductions. Deduct housing, council tax, utilities, food, transport, childcare and committed repayments; then assess emergency savings and discretionary spending. This is a planning framework, not an estimate of current local prices.
For a different question—how this compares with typical UK earnings—see ACG’s average wage after tax in the UK guide. The destination must be checked before an internal link is added. That page owns the average-wage topic; this guide remains focused on a £38,000 salary.
2025/26 vs 2026/27 — Has £38k Take-Home Pay Changed?
A reader searching for 38k after tax UK 2026, 38000 after tax 2025/26 or 38k after tax 2026/27 should first identify the tax year. The UK tax year runs from 6 April to 5 April. Under the standard England/Wales/Northern Ireland employee assumptions used here, the Personal Allowance (£12,570), 20% basic-rate tax and 8% employee NI between the relevant thresholds are the same in 2025/26 and 2026/27. The illustrative £30,879.60 annual net result therefore remains unchanged between those years in this narrow scenario.
That does not mean every person’s take-home pay is unchanged. Scottish tax bands and student loan repayment thresholds can change, and personal tax codes, pension arrangements or pay can change. This article’s main answer uses 2026/27; any earlier tax-year query should be interpreted with the rules that applied in that year. Do not reuse a 2024/25 graphic without confirming its figures and labels.
£38k After Tax Frequently Asked Questions
£38k a year is how much a month after tax?
A standard £38,000 annual salary is approximately £2,573.30 net per month in England, Wales or Northern Ireland in 2026/27 after Income Tax and employee NI, before pensions, loans and other deductions. The figure is an annualised average, not a guaranteed monthly payslip amount.
How much is £38k after tax weekly?
The annualised equivalent is £593.84 per week after standard Income Tax and NI. Weekly payroll may differ slightly from dividing the annual net by 52 because NI is assessed by pay period.
Is 38k after tax in Scotland the same?
No. Under the stated 2026/27 assumptions, the Scottish estimate is £30,834.53 annually or £2,569.54 monthly, compared with £30,879.60 and £2,573.30 elsewhere in the UK for the same standard salary scenario.
How much is 38k after tax with a Plan 2 student loan?
Using the 2026/27 annual Plan 2 threshold of £29,385, an illustrative 9% repayment on the £8,615 excess is £775.35 annually. This gives an illustrative £30,104.25 after Income Tax, employee NI and that loan, before pension deductions. Actual payroll deductions are rounded by pay period.
How does a 5% pension affect 38k take-home pay?
It depends on whether the scheme calculates 5% on full salary or qualifying earnings and whether it uses net pay, relief at source or salary sacrifice. For example, a £1,900 annual gross contribution under an assumed net pay arrangement could reduce take-home pay by approximately £1,520 after basic-rate Income Tax relief; NI ordinarily remains calculated on gross earnings before the pension deduction.
How much is £38k after tax hourly?
At 40 hours per week for 52 weeks, £38,000 is £18.27 gross per hour and approximately £14.85 net per hour under the standard assumptions. At 37.5 hours, it is £19.49 gross and approximately £15.84 net per hour. These are annualised equivalents, not hourly payroll calculations.
Why is my 1257L take-home pay different from a salary calculator?
The tax code is only one input. Pension contributions, student loans, NI category, taxable benefits, bonuses, cumulative PAYE and pay frequency may all change the payslip. Check the gross amount and individual deductions rather than comparing only the final bank payment.
Will a bonus on a £38k salary be taxed at 40%?
Not automatically. Additional taxable income is subject to the relevant marginal bands, and a bonus may change Income Tax, NI and student loan deductions in that pay period. Whether some earnings reach a higher tax band depends on the total taxable income and the applicable regional rates. An unusually large deduction on one payslip does not necessarily represent the effective rate on your full annual salary.
Official Sources and Further Help
This calculation uses the 2026/27 rates and published guidance available at the time of drafting:
- HMRC Income Tax rates and allowances.
- HMRC 2026/27 payroll and National Insurance thresholds.
- Scottish Income Tax rates.
- Student loan repayment thresholds.
- Workplace pension relief methods.
- HMRC current-year Income Tax estimator.
Calculation scope: UK employee salary, tax year 2026/27, standard allowance, ordinary employee NI category A, no pension/loan unless explicitly stated. Figures are illustrations and do not replace payroll records or individual tax advice.
If your income involves several jobs, employment and self-employment together, or complex deductions, professional advice may help you reconcile your tax position. Audit Consulting Group provides personal tax and Self Assessment support. There is no need to buy a service to use the calculations in this guide.