Documents Needed for VAT Registration in the UK: HMRC Checklist
Documents needed for VAT registration in the UK vary by business structure. To register with HM Revenue & Customs (HMRC), you normally need identifying information, relevant tax references, bank details and turnover figures. Limited companies, sole traders and partnerships have different requirements, while overseas businesses may follow additional rules. Some VAT registration identity documents are requested as part of the applicable application; invoices, contracts, bank statements and address evidence are not automatically mandatory attachments for everyone.
This guide explains the documents required for VAT registration, which figures to prepare, when HMRC may request further proof and how to check your application before submission. It distinguishes information you must enter from evidence you may need to provide later. Always follow the questions in the current HMRC registration service, as requirements vary by applicant and circumstances.
Quick Answer: What Documents Do You Need for VAT Registration?
If you are asking “what documents do I need for VAT registration?” or “what documents are needed for VAT registration?”, the answer starts with the legal structure of the applicant. These VAT registration requirements UK businesses face are primarily information requirements; the VAT registration documents required as attachments depend on the particular case.
Use this VAT registration documents checklist to organise the information before you sign in to HMRC. A checklist item does not necessarily mean you must upload a scanned document.
| Item | What to prepare | Status |
|---|---|---|
| Business identity | Registered or trading name, address and legal structure; company registration number (CRN) for a limited company. | Core application information |
| Tax references | Unique Taxpayer Reference (UTR) and relevant Corporation Tax, Self Assessment or PAYE information, as applicable. | Core information according to business type |
| Personal identity | National Insurance number and an identity document, such as a passport or driving licence, for individuals or partnerships as directed by HMRC. | Required information/document for applicable applicants |
| Bank details | Bank account details for the business or applicant, as requested in the online service. | Core application information |
| Turnover | Annual turnover details and an estimate of taxable turnover for the next 12 months. | Core application information |
| Trading evidence | Invoices, contracts, order confirmations, sales records or business plans. | Keep ready; may be requested where relevant |
| Bank statements or premises evidence | Statements, lease, utility bill or other corroboration of activity or address. | Not a universal mandatory upload |
| Additional forms | VAT2 for relevant partnership details, VAT1 for permitted postal applications, or another form for a special registration. | Conditional |
HMRC’s official registration guidance sets out separate information lists for limited companies and for individuals or partnerships. Do not delay a standard online application simply because you have not collected every example of possible supporting evidence in this article.
Documents required for VAT registration in the UK: required information versus supporting evidence
If you are searching for a VAT registration documents list, distinguish the information entered into HMRC’s service from the paperwork used to check it. The documents required for VAT registration UK applicants need are not identical in every case. A company may need its CRN and UTR, while an individual may need National Insurance and identity details. Supporting documents for VAT registration, such as customer contracts or business-address evidence, become relevant where HMRC requests them or the application route specifically requires them.
Use the table above as your list of documents for VAT registration, then confirm the applicable fields in HMRC’s current online form. A generic VAT registration documents PDF found online is not a substitute for HMRC’s live requirements.
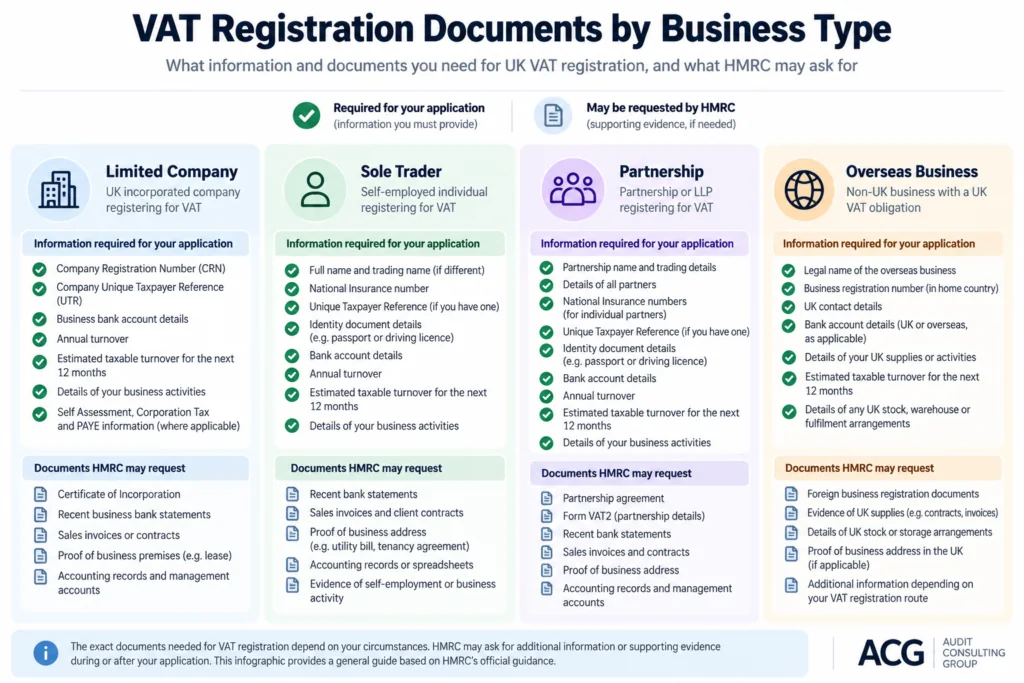
VAT Registration Documents by Business Type
Business structure determines which identifiers HMRC expects. It also affects who is responsible for supplying information and whether extra partnership or overseas details are needed.
| Applicant | Main information | Potential additional evidence |
|---|---|---|
| Limited company | CRN, company UTR, bank details, annual turnover, projected taxable turnover, and relevant Corporation Tax, PAYE and Self Assessment information. | Incorporation records, trading contracts or invoices if HMRC needs clarification. |
| Sole trader | National Insurance number, identity document, bank details, UTR if held, annual turnover and taxable-turnover estimate; relevant Self Assessment and employment information. | Invoices, customer orders or evidence of intended taxable activity. |
| Partnership | Relevant partner identity and tax details, bank information and turnover; additional partnership details requested by the registration service. | Partnership agreement or VAT2 details where applicable. |
| Overseas business | Business identity, establishment and UK supply information, relevant overseas identifiers and projected taxable activity. | Foreign registration records, contracts, UK stock or supply evidence and translations if HMRC requests them. |
For a deeper comparison, see our guide to VAT registration documents by business type. The present article remains the general checklist; the linked guide deals with structure-specific detail.
Business Identification and Tax Reference Details
Leave your details and our team will get back to you shortly.
If you are still establishing a limited company, our company formation service explains the incorporation stage. Sole traders can also find help with self-employed registration. These are separate from VAT registration.
Limited company: CRN, UTR and HMRC records
A limited company should have its Company Registration Number (CRN) available. This is the identifier issued by Companies House, not the same as its Corporation Tax UTR or a VAT number. HMRC also lists the business’s bank details, annual turnover and estimated taxable turnover for the coming 12 months. Prepare the information relevant to Self Assessment, Corporation Tax and PAYE so the application can be completed consistently.
Check the legal name and CRN against the company’s Companies House record. A trading name may differ from the registered company name; enter each in the appropriate field rather than treating them as interchangeable. A certificate of incorporation may help you check the details, but the official standard online checklist does not say every limited company must upload that certificate.
Sole trader: National Insurance and proof of identity
For an individual applicant, HMRC lists a National Insurance number and an identity document such as a passport or driving licence. It also asks for bank details, a UTR if you have one, annual turnover and an estimate of taxable turnover for the next 12 months. You may need information from Self Assessment records, payslips or a P60.
 If you do not yet have a UTR, do not invent one or enter another person’s tax reference. Follow the current online questions and check whether you need to complete a separate tax-registration step. A sole trader’s trading name does not create a separate legal person from the individual.
Partnership: partner information and VAT2
Partnerships should identify the partnership correctly and have the relevant partner details ready. HMRC’s online process can ask for additional information. Form VAT2 may be needed to provide partnership details; it is not a replacement for the main registration application. An agreement may help clarify the partners and trading arrangements, but it is not a universal upload requirement for every partnership.
Limited liability partnerships and other arrangements may have distinct filing circumstances. Check the actual legal form before selecting an application route.
Company VAT registration documents and personal identification
When preparing company VAT registration documents, use the legal company’s details rather than a director’s separate business information. A Companies House certificate may help verify the CRN, but it is not the same as the HMRC VAT registration document issued after successful registration. For individuals and partnerships, the relevant VAT registration identity documents can include a passport or driving licence, as stated in HMRC guidance.
The phrase VAT document requirements covers several distinct matters: identity information, tax records, turnover figures and any extra evidence specifically requested. There is no universal rule that every director must provide a passport scan, a utility bill and three months of bank statements with a standard limited-company application.
Bank Account and Business Address Information
HMRC includes bank account details in its standard information lists. Prepare the account holder’s name, sort code and account number where relevant, and ensure the details belong to the appropriate applicant. Do not confuse supplying bank details with a universal requirement to upload recent bank statements.
A business address must accurately describe the relevant establishment or trading location. A registered office, correspondence address and place where business is carried on can be different. If HMRC asks for address evidence, suitable documents might include a lease, utility bill or other records that genuinely support the address stated. Whether a document is acceptable depends on the question asked and the circumstances.
Keep personal information secure. Do not send passports, statements or other sensitive documents to an unverified email address or upload service. Use the method specified by HMRC or your authorised agent.
Turnover and Trading Evidence for VAT Registration
Reliable sales figures start with accurate records. Our bookkeeping services can support the underlying record-keeping, while this article explains the VAT registration evidence.
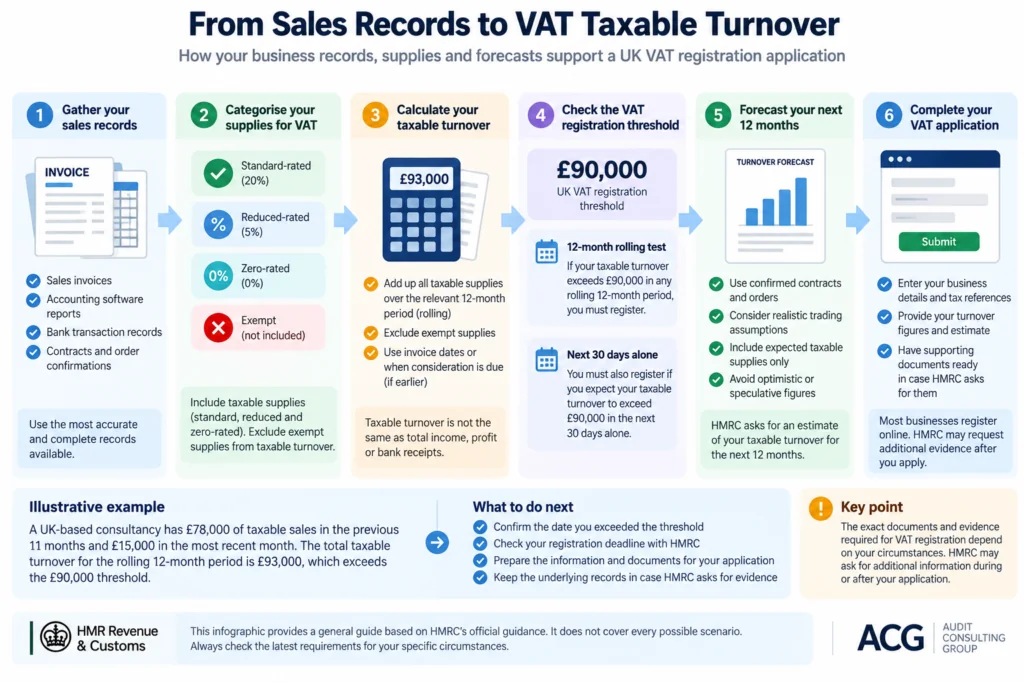
VAT taxable turnover is not automatically the same as total cash received into a bank account or the turnover shown in annual accounts. For the UK registration threshold, you need to identify the value of supplies that count under the applicable VAT rules. Standard-rated, reduced-rated and zero-rated taxable supplies can count; exempt and genuinely outside-the-scope supplies are treated differently. Certain reverse-charge and other transactions can affect the calculation, so complex cross-border or construction cases may require a separate assessment.
When does the £90,000 threshold apply?
For a business eligible for the normal UK registration threshold, mandatory registration can arise when taxable turnover in the previous rolling 12 months exceeds £90,000. A separate test applies if you expect taxable turnover to exceed £90,000 in the next 30 days alone. These are different tests; the second is not simply an annual forecast divided into months.
Under the historic rolling test, you normally notify HMRC within 30 days of the end of the month in which the threshold was exceeded, with registration effective from the first day of the second month after that month. Under the future 30-day test, you must register by the end of that 30-day period and the effective date is generally the date you first realised the threshold would be exceeded. Check the precise timing against HMRC’s current registration rules.
Worked example: reconstructing the rolling 12-month figure
Illustrative example only. A UK consultancy reviews its records at the end of September. It has £86,000 of UK taxable supplies and £7,000 of additional zero-rated supplies that count towards the registration threshold over the previous 12 months. Its relevant taxable turnover is £93,000, not £86,000. Assuming no special adjustment or registration exception applies, it has exceeded the standard threshold. It should confirm the first month in which the rolling total crossed £90,000, rather than using the date of the latest invoice as the sole trigger.
To support your calculation, reconcile your sales ledger to invoices, credit notes and receipts. Explain timing differences, cancelled invoices, deposits and non-taxable transactions. Retain the workings even if the online form asks only for the resulting figures.
| Source | What it helps establish | Common issue |
|---|---|---|
| Sales ledger | Transaction dates, values and customer records. | Gross receipts may not equal taxable turnover. |
| Sales invoices and credit notes | Evidence of the underlying supplies and adjustments. | Duplicated or cancelled transactions. |
| Bank records | Cash movements and payment reconciliation. | Loans, transfers and refunds mistaken for sales. |
| Contracts and orders | Nature, value and timing of current or expected supplies. | Projected work treated as completed sales. |
| Accounts or management reports | Cross-check of period totals. | Accounting periods differing from rolling VAT periods. |
Additional Supporting Documents HMRC May Request
Many businesses ask, “What supporting documents are needed for VAT registration?” There is no single supplementary pack that every applicant must upload. HMRC can seek further evidence to establish whether the applicant is carrying on, or genuinely intends to carry on, an economic activity and whether the requested registration is appropriate.
Depending on the case, useful evidence may include customer invoices, signed contracts, purchase orders, supplier invoices, premises records, stock information, business plans or correspondence about forthcoming taxable work. HMRC may also need clarification of the ownership structure or the person authorised to act. Provide evidence that answers the specific question; sending large unrelated bundles can make the position harder to understand.
What if the business has not started trading?
A business can in appropriate circumstances seek voluntary VAT registration before making its first taxable sale, provided there is a genuine intention to make taxable supplies and the applicable eligibility rules are met. A new design studio, for example, might have a signed customer engagement, equipment purchases and a business plan but no issued sales invoice. Those documents can help explain the proposed activity; they do not guarantee HMRC approval.
Illustrative example only. A start-up intends to supply taxable design services and has agreed its first contract. It prepares the contract, expected commencement date and realistic turnover forecast. If HMRC asks why it wants to register before trading, the company can explain its plans with supporting evidence. Whether registration is available and the effective date depend on the actual facts and current rules.
Mandatory vs Voluntary VAT Registration: Document Differences
If you need help assessing whether registration is mandatory or voluntary, see our VAT registration services.
Both mandatory and voluntary applicants need accurate identity and turnover information. The difference is primarily why registration is sought, not that voluntary applicants must automatically submit an entirely different set of documents.
| Question | Mandatory registration | Voluntary registration |
|---|---|---|
| Reason for applying | Relevant legal registration trigger has arisen. | Eligible business elects to register below the threshold or before taxable trading begins. |
| Important figures | Historic rolling turnover or qualifying 30-day expectation and relevant dates. | Nature of intended taxable supplies and credible forecast. |
| Possible supporting evidence | Sales records and workings showing when the trigger occurred. | Contracts, business plan or other evidence of genuine intended activity, if requested. |
| Key caution | Late registration can create VAT liabilities for earlier periods. | Registration brings VAT accounting and reporting obligations even at low turnover. |
Businesses whose turnover temporarily exceeds the threshold may in specific circumstances be able to apply for a registration exception; that is different from ordinary voluntary registration and can require the postal route. See VAT Notice 700/1 for the conditions.
Authorisation letter for VAT registration: when an agent is involved
An authorisation letter for VAT registration may be discussed when a business asks an accountant to communicate with HMRC, but a letter is not a standard compulsory attachment for every applicant. Agent access and authorisation must follow the applicable HMRC process. If an accountant is helping, agree who is submitting the application, what information the agent can use and how HMRC correspondence will be handled. An informal letter should not be treated as a replacement for HMRC’s required agent-authorisation arrangements.
VAT1, VAT2 and Online VAT Registration
VAT registration application, VAT registration form and paper routes
The usual VAT registration application is completed online. People looking for a VAT registration form UK or VAT1 form should know that HMRC generally directs applicants to its online service. The paper VAT1 registration form is used in specified circumstances, including certain registration exceptions, or when HMRC agrees that the applicant cannot register online. If you need VAT registration by paper, follow HMRC’s postal registration instructions instead of relying on an unofficial VAT1 form PDF download.
For partnerships, VAT2 form is used to supply partner details. HMRC’s VAT2 guidance explains when it is used and how to upload it during registration or post it to the relevant team. A VAT registration form and the documents proving that a business is registered are different things.
Most UK businesses register for VAT online. The online service requests the applicable information and may ask for additional forms based on the business type. You can usually save an incomplete application and return to it later.
VAT1 is the paper registration form used in specified circumstances, including certain registration exceptions and other cases HMRC identifies. It is not the default option for every applicant who prefers paper. If you cannot use the online service, HMRC explains how to request the form and when it may agree to a postal application in its Register for VAT by post guidance.
VAT2 provides relevant partnership information when required. Other forms, including VAT1A, VAT1B, VAT1C or VAT68, may apply to particular transactions or changes; they are not interchangeable with a standard new registration. Use the instructions attached to the specific HMRC process.
Overseas Businesses and Special Circumstances
For more detailed support on UK stock, cross-border supplies and non-established businesses, explore our international VAT services.
The normal £90,000 UK threshold does not apply in the same way to a non-established taxable person (NETP). An overseas business making taxable supplies in the UK may need to register from its first relevant taxable supply. However, having a customer in the UK does not by itself prove that every overseas service is a UK taxable supply: place-of-supply rules, the nature of the transaction, and any applicable reverse charge or other special rules matter.
Prepare information on where the business is established, what it sells, where goods are located, the type of customers and the actual UK taxable activity. For example, an overseas seller holding stock in the UK presents different VAT questions from an overseas consultancy supplying certain services to a UK business. If the position is unclear, assess it before assuming a threshold or VAT treatment.
Other special cases include taking over a business, transferring an existing VAT number, separate divisions and certain Northern Ireland transactions. Where a VAT number transfer is relevant, see HMRC’s guidance on transferring VAT registration.
How to submit supporting documents for VAT registration
There is no single submission method for every type of VAT registration supporting documents. Some documents are provided during the online process, including VAT2 where applicable; others may be requested later by HMRC. If you are wondering how to upload documents for VAT registration, use only the upload facility shown in your application or the method HMRC specifies in its correspondence. Do not send sensitive records to an unrelated website claiming to be a general HMRC document-upload portal.
If HMRC asks for additional information, identify the application reference, answer each question, provide only relevant evidence and keep a copy of what you submitted. For example, a request about the principal place of business may call for an explanation of where operations are actually managed, rather than merely another copy of the registered-office address.
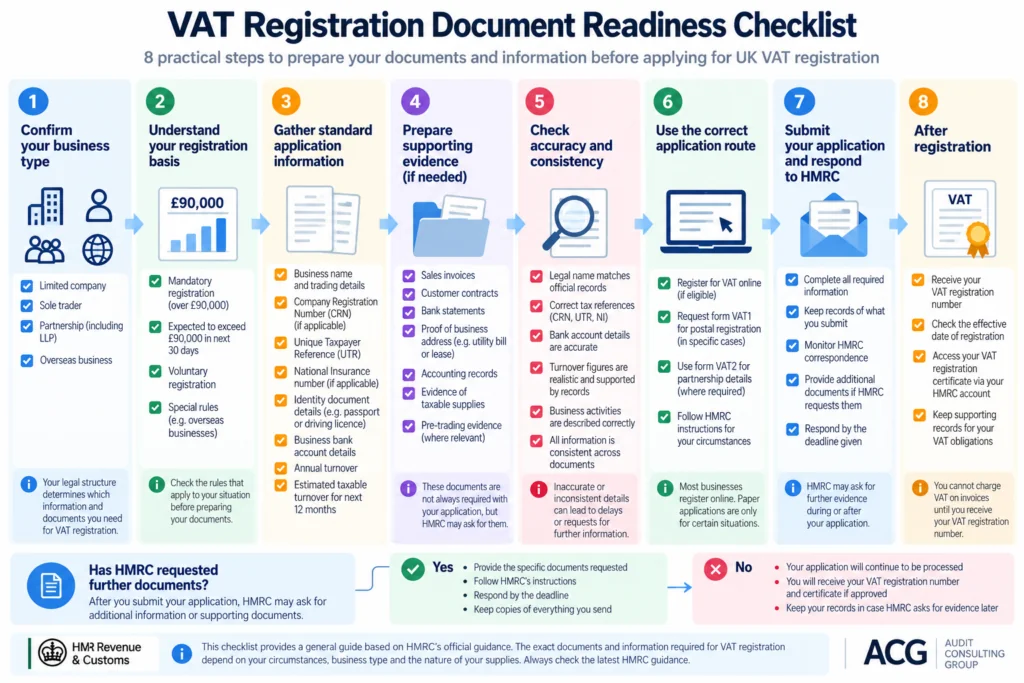
VAT Registration Document Readiness Checklist
For help with the ongoing obligations that follow registration, see our VAT compliance advisory service.
- Confirm the correct applicant and legal structure, including registered and trading names.
- Gather the CRN, National Insurance number, UTR and relevant tax records applicable to your structure.
- Have bank details and an accurate business or establishment address ready.
- Prepare annual turnover figures and the next 12 months’ estimated taxable turnover.
- Check the rolling 12-month and next-30-days registration tests, if relevant.
- Separate standard-, reduced- and zero-rated supplies from exempt or outside-the-scope items; check special cases.
- Keep a reconciliation and relevant supporting documents available if HMRC asks.
- Identify whether VAT2, a permitted postal VAT1 application or another special process applies.
- Review dates, names, identifiers and the reason for registering for consistency.
- Use the official HMRC service or an appropriately authorised agent, and retain your application records securely.
Common Document Mistakes and HMRC Follow-Up Requests
| Problem | Why it matters | What to do |
|---|---|---|
| CRN confused with UTR | Different organisations issue different identifiers. | Check the company record and HMRC tax correspondence separately. |
| Bank deposits treated as turnover | Transfers, loans or refunds may distort the figure. | Reconcile deposits to sales and other receipts. |
| Zero-rated sales omitted | Some zero-rated supplies count as taxable turnover. | Check VAT liability by supply rather than by VAT charged. |
| Annual accounts used as rolling 12 months | The registration test is not limited to the financial year. | Recalculate month by month. |
| Unexplained overseas sales | Place-of-supply treatment can change the calculation. | Record the supply type, customer and relevant jurisdiction. |
| Generic documents sent in response to HMRC | The specific query remains unanswered. | Answer each request directly with clearly labelled evidence. |
If HMRC contacts you after submission, read the request carefully, note any deadline and respond through the specified channel. Explain inconsistencies rather than silently changing figures. Keep copies of your response and evidence. Where HMRC refuses registration or disputes an effective date, the next step depends on the actual decision and any review or appeal rights stated in the notice; do not assume every case has the same remedy.
VAT Registration Certificate and Proof of Registration
After receiving your VAT number, you can also read our guide to VAT number verification for checking customer and supplier VAT details.
To obtain a copy of a VAT certificate or check where to get a VAT registration certificate, begin with your official HMRC VAT account and registration correspondence. Do not rely on an original VAT certificate image supplied by an unrelated website.
After registration, HMRC provides a nine-digit VAT registration number and confirmation of the effective date of registration, together with information about VAT reporting. A VAT registration certificate or confirmation is evidence that the business has been registered; it is different from the documents used to apply.
The VAT number should be included on VAT invoices once issued. The effective date can be earlier than the date on which HMRC communicates the number, so businesses should establish the correct VAT treatment for supplies made in that intervening period and follow HMRC guidance on invoicing adjustments. Do not invent a VAT number or show one that has not been assigned.
HMRC explains how to access VAT services through the business tax account after receiving the registration number. If you need proof of VAT registration for a supplier, customer or marketplace, use the official registration details and certificate available to your business rather than an unofficial template.
How to get a VAT registration certificate and verify proof of VAT registration
People searching for an HMRC VAT registration certificate, HMRC VAT certificate or VAT4 registration certificate are usually looking for evidence after approval, not a document to attach to their initial application. HMRC sends the registration number, effective date and related information following registration. Once the business has the number, follow HMRC’s instructions for adding VAT services to its business tax account and accessing its available registration records.
If you need to know how to get a VAT registration certificate, how to view my VAT certificate or how to find my VAT registration certificate online, first check that the registration is complete and the appropriate VAT online service is linked to your business tax account. Available digital certificate and download options can change; use HMRC’s current account instructions rather than an unofficial certificate generator. A VAT registration certificate, a VAT registration document and proof of VAT registration can be used in overlapping everyday language, but they should not be confused with the original application form.
For customers and suppliers, evidence of VAT registration may include official confirmation and the assigned VAT number. A document with your VAT number does not automatically replace an official certificate when a third party specifically asks for one. The UK VAT number is generally nine digits; use the official verification service where appropriate.
Frequently Asked Questions About VAT Registration Documents
What documents do I need to register for VAT as a limited company?
Prepare your CRN, company UTR, business bank details, annual turnover and an estimate of taxable turnover for the next 12 months. HMRC also asks for relevant Corporation Tax, PAYE and Self Assessment information. Additional evidence is case-dependent.
Do I need a passport for VAT registration?
HMRC lists an identity document, such as a passport or driving licence, for individuals and partnerships. The precise identity checks depend on who is applying and the route used. Do not assume that every limited company must upload every director’s passport as part of a standard application.
Can I register for VAT without a UTR?
HMRC asks limited companies for a UTR and individuals or partnerships for a UTR if they have one. Follow the relevant online questions and confirm which tax registrations are needed for your circumstances; never use an incorrect reference to bypass a field.
Are bank statements mandatory for VAT registration?
Bank account details are part of HMRC’s standard information list. Recent bank statements are not a universal standard upload requirement, although HMRC may request statements or other evidence to check particular information.
Do I need proof of business address?
You need to provide accurate address information. A lease, bill or similar record may be useful if HMRC asks you to substantiate the address, but there is no blanket requirement for every online applicant to upload the same proof.
Can I register for VAT before making any sales?
Potentially, yes. An eligible business intending to make taxable supplies may be able to register voluntarily before trading begins. HMRC may seek credible evidence of the intended activity, such as contracts or plans.
What turnover evidence should I keep?
Retain sales ledgers, invoices, credit notes and a calculation of taxable turnover for the relevant periods. Contracts and forecasts may support a next-30-days test or voluntary registration. Explain adjustments clearly.
Is VAT2 required for every partnership?
VAT2 is used to provide partner details when registering a partnership for VAT and to update those details later. HMRC says the form can be uploaded during the registration process or posted to its VAT registration team. Follow the current VAT2 instructions and obtain the relevant partners’ details and signatures.
Can I use VAT1 instead of registering online?
Most applicants should register online. VAT1 is used for specified postal cases or where HMRC accepts that the applicant cannot use the online service. Check the official postal-registration guidance before requesting a form.
Does an overseas company need the same documents?
Not necessarily. HMRC may need overseas business identifiers and evidence of UK taxable supplies. Non-established taxable persons can have a different registration trigger, so assess the supply and establishment facts first.
How do I get a VAT registration certificate?
After HMRC registers the business, use its official confirmation and VAT account services to access the relevant registration information. The VAT registration number and effective date are the key details to verify.
What happens if HMRC requests additional documents?
Respond to the specific questions by the deadline and through the channel HMRC provides. Supply relevant evidence, explain discrepancies and retain copies. If the request concerns a complex VAT position, professional advice may help.
What evidence is needed for VAT registration?
HMRC requires the information relevant to the applicant’s business type, including identity or company details, tax references, bank details and turnover. What evidence is needed for VAT? beyond that depends on the specific application and any follow-up request. Contracts, invoices, bank statements or proof of trading can support a case, but none is a universal attachment for all applicants.
What documents are required for voluntary VAT registration?
The basic applicant details are similar to those used for mandatory registration. Where the business has not started trading, credible evidence of an intention to make taxable supplies may be important. Documents required for voluntary VAT registration therefore depend on the activity and the information HMRC asks the applicant to substantiate.
What if I have two businesses or two trading names?
For VAT registration of two businesses, the important question is whether they are operated by the same taxable person or by separate legal persons. Two trading names used by one sole trader do not automatically create two separate VAT registrations. Companies are separate legal persons unless an applicable group-registration arrangement changes the position. Check the legal structure before applying.
What is a VAT registration certificate, and how is it different from a VAT registration form?
A VAT registration form is part of applying for VAT. A VAT registration certificate or official registration confirmation establishes that HMRC has registered the business. If you are searching for how to get proof of VAT registration or how to get VAT certificate UK, use the official HMRC registration communication and linked VAT account services.
Professional VAT Registration Assistance
Learn more about our VAT registration assistance if you would like professional support preparing your HMRC application.
If your registration involves multiple business entities, uncertain taxable turnover, overseas trading, pre-trading activity or an HMRC evidence request, a tax professional can help assess the facts and prepare a consistent application. Audit Consulting Group can discuss the documents and information needed for your circumstances; the scope and fees should be agreed before work begins.
Official Sources and Editorial Scope
This guide explains general UK VAT registration information and is not a determination of any particular business’s VAT status. The applicable treatment depends on its supplies, establishment, dates and other facts. Official references: HMRC: How to register; HMRC: When to register; VAT Notice 700/1; and Register for VAT by post.
About the Author
Iryna Shmulenko is a qualified accountant and auditor with strong experience in finance, internal audit, and accounting systems. She previously built and supervised complete accounting and control frameworks for various companies across multiple countries. As one of the founders of Audit Consulting Group (UK), she provides accounting, tax, VAT, payroll, and internal audit services to UK and international clients. Iryna combines global audit standards with modern UK practices to create efficient and transparent financial processes. She is ACCA partly qualified and specialises in tax advisory, financial audit, internal controls, and business process optimisation.