Average Wage After Tax UK: Monthly, Weekly & Annual Take-Home Pay
Tax calculations: 2026/27 UK tax year (6 April 2026–5 April 2027). Earnings benchmark: latest verified ONS Annual Survey of Hours and Earnings (ASHE), April 2025.
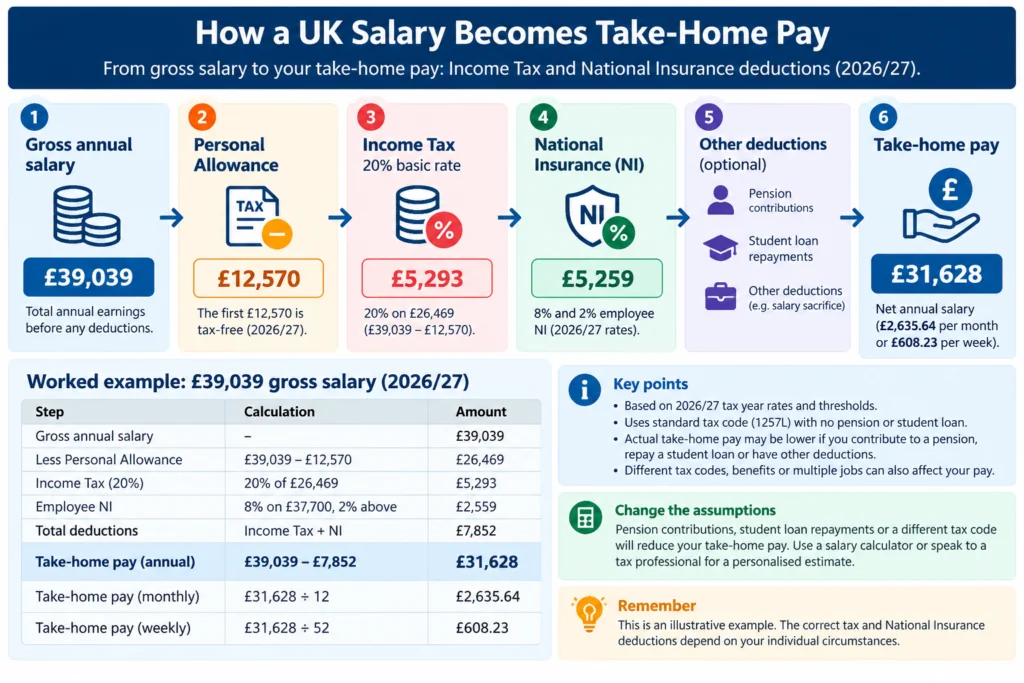
What is the average wage after tax in the UK? As a useful benchmark, the Office for National Statistics (ONS) reported median gross annual earnings of £39,039 for full-time employees who had been in their jobs for at least a year in April 2025. If someone earned that amount throughout the 2026/27 tax year in England, Wales or Northern Ireland, their illustrative take-home pay would be approximately £31,628 a year, £2,636 a month or £608 a week, after standard Income Tax and employee National Insurance (NI), before pension contributions and student loan repayments.
This is not an ONS figure for average net salary: it is our calculation applied to a specifically defined ONS gross-pay statistic. The median is the midpoint of a distribution, not the arithmetic mean. Your payslip can differ because of where you live, tax code, pension scheme, student loan, bonuses or other deductions.
See the ONS earnings release and HMRC employer tax rates for the underlying sources.
What Is the Average Wage After Tax in the UK?
People searching for the average salary UK after tax, average UK take-home pay or average net salary UK often expect one definitive number. There is no single answer without specifying the workforce, the period and the deductions included. The ONS publishes several earnings measures, including median weekly earnings for full-time workers, median annual earnings for full-time employees employed in their job for at least a year, and hourly earnings excluding overtime. Those figures cannot be substituted for one another.
In April 2025, the ONS reported £766.60 median gross weekly earnings for full-time employees and £19.67 median hourly earnings excluding overtime. Its £39,039 annual median refers to the narrower group of full-time employees in the same job for at least one year. The £39,039 figure is the annual benchmark used for our illustrative PAYE calculation; it is not an observed 2026 salary or an official net-pay statistic. These measures describe gross earnings, not the amount transferred to a bank account.
Average UK Salary Before Tax vs After Tax
Gross salary is pay before deductions. Net salary or take-home pay is what remains after applicable payroll deductions. For most employees, the main statutory deductions are PAYE Income Tax and employee Class 1 NI. Workplace pension contributions and student loan repayments can reduce the cash received further. Employer NI is an employer cost, not an additional deduction from the employee’s stated gross salary.
The term average wage may refer to the mean (all salaries added together and divided by the number of employees) or the median (the middle observation). High salaries can pull the mean upwards. For a practical picture of a typical worker’s pay, the median is often the more useful benchmark. It is still necessary to identify whether the measure includes part-time workers and whether it covers weekly, annual or hourly earnings.
Methodology used throughout the main calculations: employee aged under State Pension age; standard Personal Allowance of £12,570; England, Wales or Northern Ireland Income Tax; standard employee Class 1 NI category A; steady pay across the year; no other taxable income, pension contributions, student loans, salary sacrifice, benefits or adjustments. Figures are rounded and illustrative, not a payroll quote. Scotland is calculated separately below. NI is actually assessed by pay period for most employees, so real payslips can differ slightly from annualised examples.
Average Monthly, Weekly and Annual Take-Home Pay
The UK average salary per month after tax depends on which gross salary benchmark is used. Using the ONS £39,039 annual median and the stated 2026/27 assumptions:
| Measure | Gross pay | Illustrative take-home after Income Tax and employee NI |
|---|---|---|
| Annual | £39,039 | £31,628 |
| Monthly (annual ÷ 12) | £3,253.25 | £2,635.64 |
| Weekly equivalent (annual ÷ 52) | £750.75 | £608.23 |
| Daily equivalent (annual ÷ 260 working days) | £150.15 | £121.65 |
The weekly and daily rows are annualised equivalents, not predictions of a weekly or daily payroll calculation. An average hourly wage UK after tax cannot be derived reliably without the employee’s contracted hours, paid leave and payroll basis. For example, dividing the illustrative annual net pay by 1,950 hours (37.5 hours × 52 weeks) gives about £16.22 net per contracted hour. This is a mathematical illustration, not an ONS hourly net-pay statistic.
UK Take-Home Pay by Gross Annual Salary
The following comparison answers common searches for salary after tax UK, net salary UK and monthly take-home pay. All rows use exactly the same 2026/27 England/Wales/Northern Ireland assumptions explained above.
| Gross annual salary | Income Tax | Employee NI | Net annual | Net monthly |
|---|---|---|---|---|
| £20,000 | £1,486 | £594 | £17,920 | £1,493 |
| £25,000 | £2,486 | £994 | £21,520 | £1,793 |
| £30,000 | £3,486 | £1,394 | £25,120 | £2,093 |
| £35,000 | £4,486 | £1,794 | £28,720 | £2,393 |
| £39,039 (ONS benchmark) | £5,294 | £2,118 | £31,628 | £2,636 |
| £40,000 | £5,486 | £2,194 | £32,320 | £2,693 |
| £45,000 | £6,486 | £2,594 | £35,920 | £2,993 |
| £50,000 | £7,486 | £2,994 | £39,520 | £3,293 |
| £60,000 | £11,432 | £3,211 | £45,357 | £3,780 |
| £75,000 | £17,432 | £3,511 | £54,057 | £4,505 |
Numbers are rounded to the nearest pound. Pension, loan and other deductions are excluded. This is an illustrative gross-to-net table, not a survey of net earnings.
Someone on £40,000 gross, for example, takes home about £2,693 a month before pension and loan deductions under these assumptions. That is different from saying £40,000 after tax: the latter would mean the person actually receives £40,000 net, requiring a higher gross salary.
How to Calculate Salary After Tax in the UK
Income Tax: start with the Personal Allowance
For the 2026/27 tax year, the standard Personal Allowance is £12,570. On a £39,039 gross salary, the amount above that allowance is £26,469. Assuming the entire taxable amount is in the 20% basic-rate band, annual Income Tax is £26,469 × 20% = £5,293.80. Higher and additional rates apply to relevant portions of larger incomes; tax is not charged at the top marginal rate on the entire salary.
The Personal Allowance is normally reduced by £1 for every £2 of adjusted net income above £100,000 and may be eliminated at £125,140. Consequently, a simple calculation using the full allowance would be wrong for some higher earners.
National Insurance: a separate employee deduction
For most employees in 2026/27, employee Class 1 NI is 8% on earnings between the primary threshold (£12,570 annual equivalent) and upper earnings limit (£50,270 annual equivalent), then 2% above the upper limit. For our £39,039 example, estimated employee NI is (£39,039 − £12,570) × 8% = £2,117.52. Check the official NI rates.
Worked PAYE calculation: £39,039 gross salary
| Step | Calculation | Annual amount |
|---|---|---|
| Gross earnings | ONS benchmark applied as an illustrative salary | £39,039.00 |
| Income Tax | (£39,039 − £12,570) × 20% | −£5,293.80 |
| Employee NI | (£39,039 − £12,570) × 8% | −£2,117.52 |
| Estimated net pay | Gross less Income Tax and NI | £31,627.68 |
| Estimated monthly net | £31,627.68 ÷ 12 | £2,635.64 |
The exact monthly figure above is based on the unrounded annual result. It may differ by a few pence from tables that round annual deductions first.
UK Income Tax and NI Rates in 2026/27
For employment income in England, Wales and Northern Ireland, the principal 2026/27 Income Tax bands for a person with the standard Personal Allowance are:
| Illustrative annual income range (standard allowance assumed) | Marginal Income Tax rate |
|---|---|
| Up to £12,570 | 0% |
| £12,571–£50,270 | 20% |
| £50,271–£125,140 | 40% |
| Above £125,140 | 45% |
The £100,000 Personal Allowance taper can change the effective marginal rate and means the table is not a complete calculation for every individual. Scotland uses different bands on non-savings, non-dividend income, discussed below. National Insurance thresholds and rates apply UK-wide for the standard employee category, subject to individual category and payroll circumstances.
Official references: HMRC Income Tax rates and allowances and 2026/27 employer thresholds.
How Much Gross Salary Gives You £3,000 a Month After Tax?
A frequent question is: “What salary is £3,000 a month after tax UK?” If the target is £3,000 net per month, the target annual take-home pay is £36,000. Under our standard England/Wales/Northern Ireland assumptions, a gross salary of approximately £45,112 a year produces that net amount before pension contributions, student loans and other deductions.
At this salary level, the 20% Income Tax rate and 8% employee NI rate apply to earnings above £12,570, so each additional pound of gross salary leaves approximately 72 pence in take-home pay. A workplace pension or student loan would mean you need a higher gross salary to receive £3,000 in cash each month. Scottish tax bands may also change the result.
Average Salary After Tax in Scotland vs the Rest of the UK
The average salary after tax in Scotland is not necessarily the same as in England for an identical gross salary. Scottish residents pay Scottish Income Tax rates on employment earnings. Wales currently uses the same effective employment-income rates as England and Northern Ireland for the 2026/27 examples here, while Scottish bands differ.
Scotland: different Income Tax bands
For 2026/27, the Scottish rates for non-savings, non-dividend income are 19% starter, 20% basic, 21% intermediate, 42% higher, 45% advanced and 48% top. The respective gross-income boundaries, assuming the full Personal Allowance, are £16,537, £29,526, £43,662, £75,000 and £125,140. See Scottish Income Tax rates.
Worked comparison: same gross pay, different Income Tax
At £40,000 gross, using the same standard NI assumptions and excluding pension and student loan deductions:
| Item | England, Wales and Northern Ireland | Scotland |
|---|---|---|
| Gross salary | £40,000 | £40,000 |
| Estimated Income Tax | £5,486 | £5,551.07 |
| Estimated employee NI | £2,194.40 | £2,194.40 |
| Estimated net annual | £32,319.60 | £32,254.53 |
| Estimated net monthly | £2,693.30 | £2,687.88 |
The Scottish estimate uses 19% on £3,967, 20% on £12,989 and 21% on £10,474 of taxable earnings. The difference is modest at this salary but can change substantially at other income levels. These are tax-rule comparisons, not claims about average wages in each nation.
How Pension Contributions and Student Loans Change Take-Home Pay
Workplace pensions: the scheme determines the tax effect
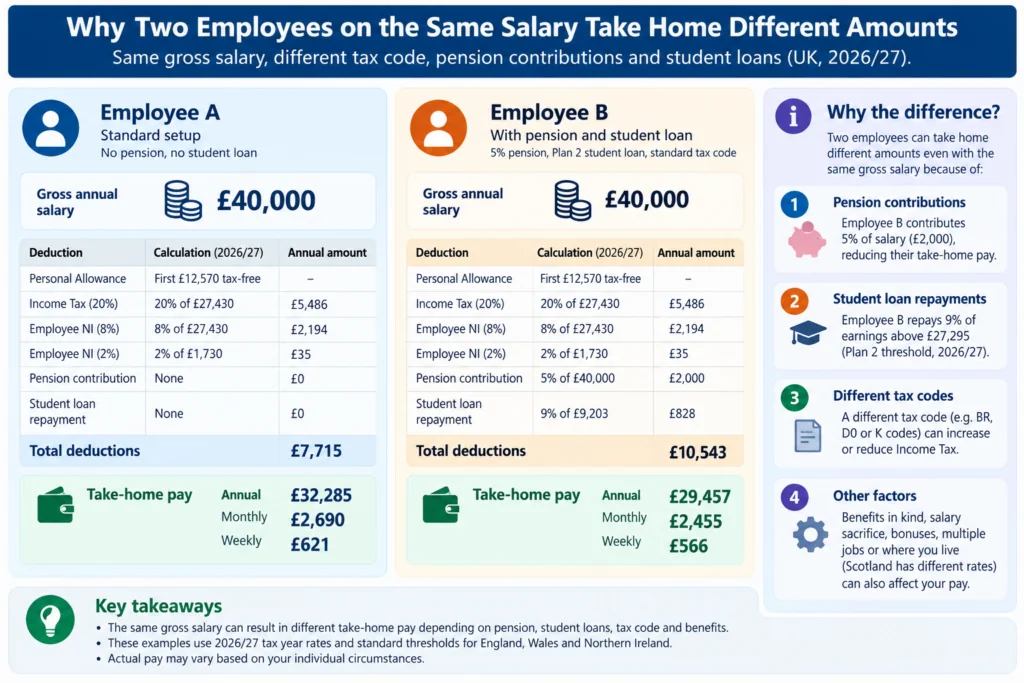
Auto-enrolment minimum contributions are commonly described as 5% from the employee and 3% from the employer, but these are generally calculated on qualifying earnings, not necessarily the entire salary. Employers may use different certified bases, and the way tax relief is delivered matters.
With a net pay arrangement, eligible employee contributions are deducted before Income Tax but generally do not reduce employee NI. With relief at source, contributions are taken from net pay and the pension provider adds basic-rate tax relief; higher-rate taxpayers may need to claim additional relief. With salary sacrifice, an employee agrees to reduce contractual cash salary in exchange for an employer pension contribution, potentially changing both Income Tax and NI. These mechanisms cannot be represented by a single universal “5% pension deduction” from gross pay.
Student loan repayment thresholds, 2026/27
Student loan deductions are based on the relevant plan and earnings above its threshold. The 2026/27 thresholds are:
| Loan plan | Annual threshold | Repayment rate above threshold |
|---|---|---|
| Plan 1 | £26,900 | 9% |
| Plan 2 | £29,385 | 9% |
| Plan 4 | £33,795 | 9% |
| Plan 5 | £25,000 | 9% |
| Postgraduate Loan | £21,000 | 6% |
Source: HMRC student loan employer guidance. An employee on £40,000 gross with Plan 2 would repay approximately (£40,000 − £29,385) × 9% = £955.35 a year, equivalent to about £79.61 a month when annualised. Actual deductions use pay-period thresholds and rounding. A postgraduate loan may be collected alongside an undergraduate plan.
Why Your Payslip May Differ from an Average Take-Home Estimate
A salary advertised at £40,000 does not guarantee the same monthly bank transfer for everyone. Factors include:
- Tax code: an emergency code, an adjustment for a previous underpayment, or a second job can change PAYE deductions.
- Pension: employee contribution rate, qualifying earnings, tax-relief mechanism and salary sacrifice affect net pay differently.
- Student loan: the plan and whether a postgraduate loan also applies matter.
- Bonuses and overtime: higher pay in one period can increase that period’s deductions, particularly NI and student loan repayments.
- Benefits in kind: some taxable benefits are reflected through payroll or an adjusted tax code.
- Multiple jobs or income sources: your total annual tax position may differ from each employer’s payroll calculation.
- Scotland: different Income Tax rates on employment income.
Income Tax is progressive. Moving into a higher band does not normally mean all your salary is taxed at that higher rate. The extra rate applies to the relevant portion, subject to allowance tapering and other rules.
How Salaries Vary by Region and Occupation
UK earnings vary by location, occupation, age, hours and employment type. London may have higher gross pay in many occupations, but a larger gross salary does not by itself establish greater disposable income: housing, commuting and household costs are separate from PAYE deductions.
The ONS ASHE release provides regional and occupational breakdowns. However, it would be misleading to publish a table of supposedly precise average net salary by region or industry without selecting a consistent ONS measure and applying a stated tax method. A London figure for full-time weekly median earnings should not be compared with a UK annual mean or a part-time industry average.
For meaningful comparisons, check (1) the same year, (2) full-time versus all employees, (3) median versus mean, (4) annual versus weekly measures, and (5) Scotland’s separate Income Tax treatment. See the ONS ASHE bulletin and linked datasets. A detailed regional table can be added after its exact ONS dataset and population have been verified; it should not be populated with unsupported estimates.
How to Check Your Payslip and Tax Code
If your monthly salary after tax is unexpectedly low, start with your payslip rather than assuming your employer made a mistake. Compare gross taxable pay, tax code, Income Tax, employee NI, pension, student loan and any other deductions. Check whether a bonus, unpaid leave or changed hours affected the period.
Then check the tax code HMRC has issued. 1257L commonly indicates the standard Personal Allowance for someone taxed under the relevant non-Scottish code; Scottish tax codes normally have an S prefix and Welsh codes may have a C prefix. Codes such as BR, D0 or 0T may be correct in certain circumstances, especially with multiple jobs, but should not be treated as automatically correct or incorrect without context.
Use GOV.UK’s tax code guidance and compare the code shown in your HMRC account with the one used by payroll. If you identify a discrepancy, ask your employer’s payroll team and HMRC to review the relevant information. Keep recent payslips, your P60 (where available), pension statements and student loan plan details to support the check.
Frequently Asked Questions
What is the average UK take-home pay per month?
There is no single official net figure for all UK workers. Applying standard 2026/27 England/Wales/Northern Ireland tax and NI rules to the ONS April 2025 £39,039 annual full-time median benchmark gives an illustrative £2,636 per month, before pensions and student loans. That is a calculated example, not an ONS net-pay survey result.
What is the difference between average and median salary?
The arithmetic mean divides total earnings by the number of employees. The median is the midpoint: half of observations fall below it and half above. Because high earners can distort the mean, the median is often more representative of typical pay, but both depend on the population measured.
How much is £30,000 a year after tax?
Under the standard 2026/27 England/Wales/Northern Ireland assumptions, approximately £25,120 a year or £2,093 a month, before pension, student loan and other deductions.
Is £40,000 a good salary in the UK?
It depends on household circumstances, location and living costs. Under our baseline assumptions, £40,000 gross produces around £2,693 a month in England, Wales or Northern Ireland. It is close to the ONS £39,039 full-time annual median benchmark for employees in their jobs for at least a year, but that is not a cost-of-living assessment.
What salary do I need to take home £3,000 per month?
Approximately £45,112 gross a year under the baseline 2026/27 England/Wales/Northern Ireland rules. You may need more if you make pension contributions or repay a student loan, and the answer may differ in Scotland.
Is take-home pay lower in Scotland?
Not always. Scotland has different bands and rates for employment income, so the answer depends on gross salary. At £40,000 gross, our standard illustration gives approximately £2,688 monthly in Scotland compared with £2,693 in England, Wales or Northern Ireland.
Does my pension reduce my take-home pay?
Usually your cash take-home pay is reduced by employee pension contributions, but the effect depends on whether your scheme uses net pay, relief at source or salary sacrifice. Tax relief can offset part of the contribution cost.
How do student loans affect net salary?
Repayments generally apply to earnings above your plan’s threshold. For 2026/27, Plan 2 uses a £29,385 annual threshold and a 9% repayment rate on earnings above it. Other plans have different thresholds, and postgraduate loans use 6%.
Why does my payslip show less than a salary calculator?
A calculator may exclude your pension, student loan, taxable benefits, tax-code adjustment or pay-period effects. Check that it uses the correct tax year and UK nation, then compare each deduction on your payslip.
Official Sources, Calculation Method and Further Help
Official sources:
- ONS — Employee earnings in the UK: 2025 (ASHE)
- HMRC — Rates and thresholds for employers, 2026/27
- HMRC — Income Tax rates and allowances
- GOV.UK — National Insurance rates
- Scottish Government — Scottish Income Tax 2026/27
- HMRC — Student loan repayment guidance
- GOV.UK — Tax codes
Scope: Illustrative calculations for standard PAYE employees; no personal tax advice. Figures are based on the tax year 2026/27, with the April 2025 ONS ASHE benchmark. Gross annual salary is treated as steady annual employment pay. Tax and NI are annualised for comparison; actual payroll uses statutory pay-period and rounding rules. Student loans, pensions, tax-code adjustments, salary sacrifice and other deductions are excluded from the baseline unless specifically stated.
If your tax code, multiple income sources or PAYE deductions need individual review, contact Audit Consulting Group to discuss the circumstances.