VAT on Services to Overseas Customers: UK Place of Supply Rules
Do you charge VAT on services to overseas customers? Not always. UK VAT on services to overseas customers depends on whether the buyer is a business or private consumer, where the relevant parties belong for VAT purposes and what service is supplied. For most general-rule business-to-business (B2B) services, the place of supply is where the customer belongs. For general-rule business-to-consumer (B2C) services, it is normally where the supplier belongs, although important exceptions apply.
This guide explains how a UK supplier should assess VAT on services to overseas customers, including EU and non-EU clients, professional services, digital services, invoicing and UK VAT Return reporting. It concerns services, not exports of goods.
Do You Charge VAT on Services to Overseas Customers?
When deciding whether to charge VAT on services outside the UK, start with the legal place of supply, not simply the overseas billing address. UK VAT on services to overseas customers can be different for an EU business, a non-EU business and a private consumer in the same country. The question is not just whether the customer is overseas, but which rule applies to the actual service.
| Customer and service | Usual starting rule | UK VAT outcome |
|---|---|---|
| Overseas business buying a general-rule service | Place of supply is where the business customer belongs | Usually outside the scope of UK VAT |
| Overseas private customer buying a general-rule service | Place of supply is where the UK supplier belongs | UK VAT may be due if the supply is taxable |
| Overseas private customer buying a qualifying professional or intangible service | Special B2C rule: customer location | Usually outside the scope of UK VAT |
| Services subject to a special place-of-supply rule | Depends on the precise service and circumstances | Determine under the specific rule |
Important: “Outside the scope of UK VAT” is not the same as “zero-rated”. Nor does the absence of UK VAT necessarily mean there are no VAT or sales-tax obligations overseas.
How UK VAT Place of Supply Rules Work
 Searches such as VAT on services provided outside UK often refer to two different situations: work physically performed abroad and services supplied to a customer based abroad. They are not equivalent. For many professional services, where the work is carried out does not decide the VAT place of supply. By contrast, a service directly related to a particular property can be governed by the location of the land.
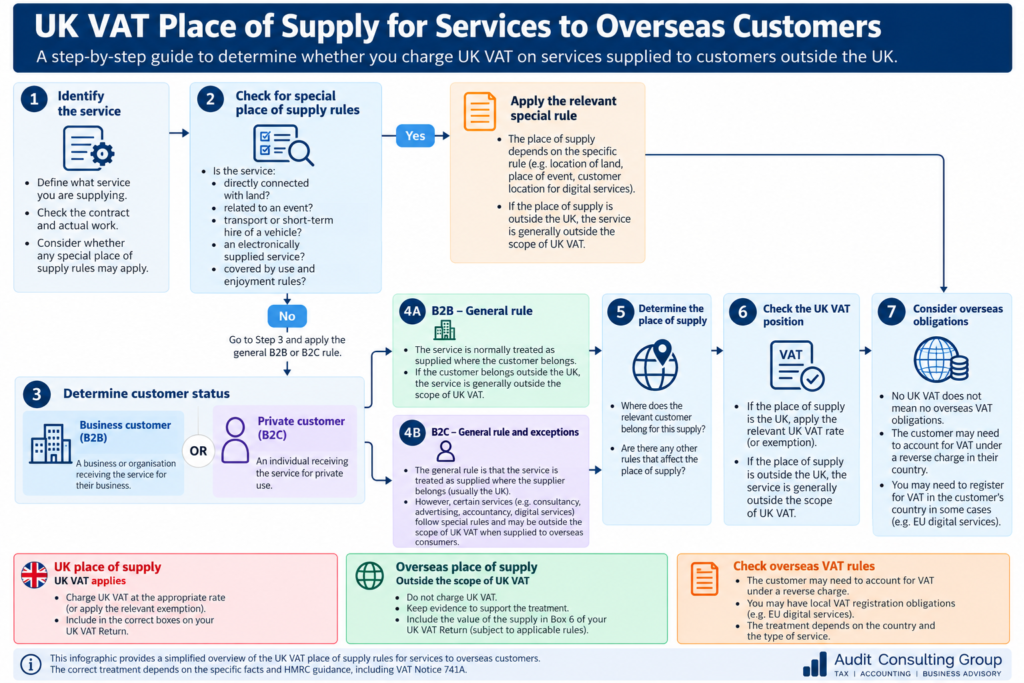
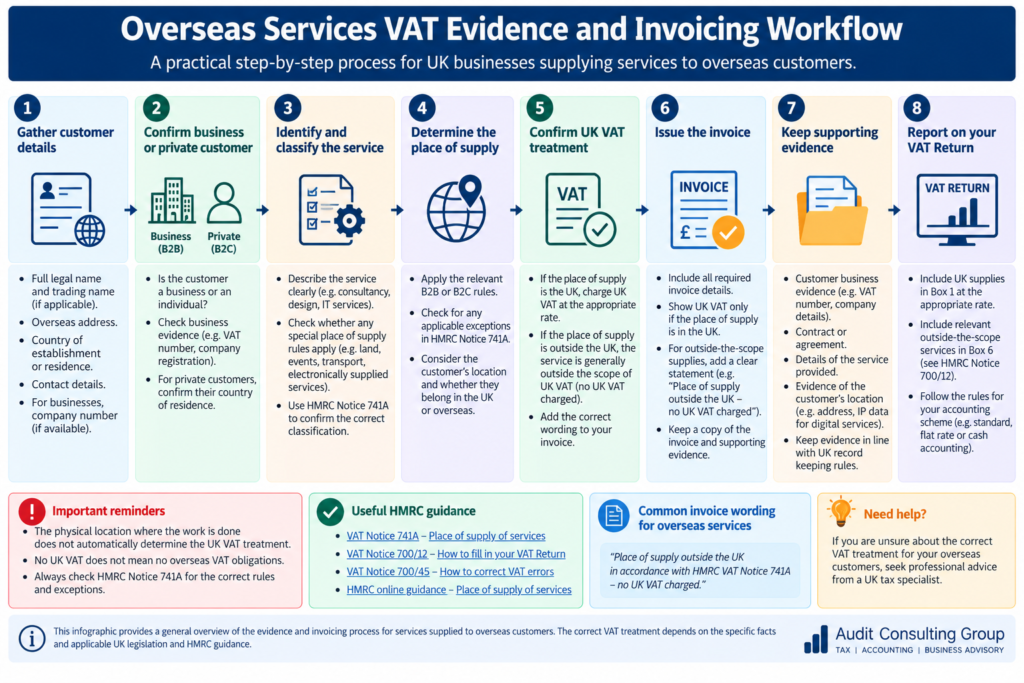
The UK VAT place of supply of services rules therefore require a sequence: classify the supply, identify the recipient and their status, establish the relevant place of belonging, test any special rules and only then decide whether UK VAT is chargeable. This sequence applies even where the invoice is in a foreign currency or the customer has no UK VAT number.
The place of supply determines the country in which a service is treated as supplied for VAT purposes. The place where someone sits while doing the work is not necessarily the place of supply. HMRC’s VAT Notice 741A sets out the general rules and exceptions.
Identify what service you are actually supplying
Start with the contract, deliverables and economic substance. Marketing consultancy, access to automated software, admission to an event and work on a building are not necessarily treated alike. A package containing different elements may require an assessment of whether it is one composite supply or several distinct supplies.
Determine whether the customer is in business
For the general B2B rule, you need appropriate evidence that the customer is a business and is receiving the service in that capacity. An overseas VAT registration number can help, but is not the only possible evidence. Relevant evidence may include company registration details, commercial contracts, business correspondence and other documentation appropriate to the jurisdiction.
Determine where the customer belongs
A customer’s billing address alone may not establish where they belong for a particular supply. A business can have more than one establishment. Consider whether the service is received by the business establishment or a fixed establishment elsewhere, applying HMRC’s establishment rules to the facts.
VAT on Services to Overseas Businesses (B2B)
VAT on B2B services outside the UK: under the general rule, a qualifying service supplied to a business belonging outside the UK is normally outside the scope of UK VAT. This is the starting point for VAT on services to overseas businesses, including services to an overseas company or foreign companies that are receiving the work for business purposes. It is not a blanket exemption for every transaction with a foreign-registered customer.
Do you charge VAT on services to an overseas company?
Usually not where the overseas company is the genuine business recipient, belongs abroad for that supply and the service falls under the general B2B rule. For example, a UK agency delivering a qualifying marketing strategy project to an Australian trading company would generally not charge UK VAT. Check whether a UK fixed establishment is actually receiving the service, whether the work is connected with land or another special category, and whether Australian indirect-tax requirements apply. Keep records explaining the decision.
For most B2B services covered by the general rule, the place of supply is where the business customer belongs. A UK VAT-registered consultancy providing ordinary strategic advice to a business established in Germany, for example, would normally treat that service as outside the scope of UK VAT, provided no special rule applies.
Do not assume that every invoice to a foreign company qualifies. Check the customer’s business status, the establishment receiving the service and the precise nature of the supply. Services connected with land, event admission and certain other activities can follow different rules.
Evidence to retain for overseas B2B services
- The signed agreement, statement of work or order.
- Customer legal name, address and relevant business registration evidence.
- VAT number or alternative evidence of business status, where appropriate.
- Evidence identifying the establishment receiving the service.
- A documented explanation of the applicable place-of-supply rule.
- Invoice and supporting transaction records.
If the business customer is in an EU member state, check whether local reverse-charge rules place an accounting obligation on that customer. This is a matter of the relevant overseas law, not a universal UK invoicing rule.
VAT on Services to Overseas Consumers (B2C)
 Charging VAT on services to overseas customers is more complicated when the buyer is a private individual. Do not assume that every overseas consumer invoice must include UK VAT, or that all overseas customers are VAT-free. First apply the general B2C rule, then consider the specific exceptions, including those for certain professional and intangible services supplied to non-UK consumers.
Under the general B2C rule, a service is normally supplied where the supplier belongs. Therefore, a UK supplier may need to charge UK VAT to a private overseas customer for a taxable general-rule service. But this is only the starting point.
Professional, technical and intangible services
HMRC Notice 741A, section 12, provides a special rule for specified B2C services supplied by a UK business to customers who belong outside the UK. For qualifying services, the place of supply is where the customer belongs, making the service outside the scope of UK VAT. The qualifying categories include specified professional, consultancy, advertising, financial, intellectual and other intangible services. Classification depends on the nature of the service, not simply the supplier’s job title.
Example: A UK graphic designer creates a brand identity for a private individual belonging in Canada. Depending on the precise contractual service, qualifying advertising or similar intangible services may fall within the section 12 exception. It would be wrong to assume that UK VAT is automatically chargeable merely because the customer is a consumer.
Electronically supplied services are not every service delivered online
An automatically delivered digital product may be an electronically supplied service. A bespoke consultation conducted by a person over video call does not become an electronically supplied service merely because the internet is used to deliver it. The distinction matters because electronically supplied services have their own place-of-supply rules and can create overseas VAT obligations.
Special Place of Supply Rules
Before relying on either general rule, test whether your service falls within a special category under HMRC Notice 741A.
Land and property-related services
Services with a sufficiently direct connection to specific land or property are generally supplied where that land is located. Not every service to a property business is automatically land-related: the actual service and its connection to the property matter.
Events, admission and activities
B2B admission to events and B2C services relating to certain activities have specific rules. The distinction between admission and wider event services is important. Virtual participation may require a different assessment from in-person attendance; do not apply a blanket “where the event takes place” conclusion without checking the relevant rule.
Passenger transport, catering and other exceptions
Passenger transport, restaurant and catering services, certain hire arrangements and other defined supplies can be subject to special treatment. Check the relevant section of Notice 741A rather than assuming the general B2B or B2C rule decides the outcome.
Use and enjoyment
For certain specified services, use-and-enjoyment provisions can change the result where services are effectively used or enjoyed in a different territory. These provisions are not a universal override for every overseas service. Apply them only to the categories and circumstances covered by the rules.
VAT on Services to EU and Non-EU Customers: Worked Examples
Do UK businesses charge VAT on services to EU customers?
 For a typical consultancy or accountancy service supplied to an EU business customer under the general B2B rule, UK VAT is normally not charged because the place of supply is outside the UK. A private EU customer can have a different outcome, and electronically supplied services, land-related services and admission to events require separate checks. Brexit did not turn all services supplied to the EU into zero-rated supplies.
What if the customer is outside Europe?
For services supplied to businesses in the USA, Canada or Australia, the same UK general B2B principle normally applies. This is why VAT on overseas sales of services cannot be determined by geography alone. A service to a private customer in the same country may follow the general B2C rule or an exception. Local GST, VAT or sales-tax requirements must be assessed separately; the UK rule does not settle foreign liabilities.
The following are hypothetical illustrations, not individual tax advice. Each assumes a UK-established supplier, no unusual fixed-establishment facts and no additional special rule unless stated.
| Scenario | Likely UK treatment | What to verify |
|---|---|---|
| UK marketing consultant advises a German trading company | Generally outside the scope of UK VAT under the B2B general rule | Customer business status, receiving establishment and German VAT obligations |
| UK accountant advises a US business | Generally outside the scope of UK VAT under the B2B general rule | Business evidence, service classification and any applicable US taxes |
| UK designer provides qualifying advertising/design services to a Canadian private customer | May be outside the scope of UK VAT under the special B2C rule | Whether the actual service falls within Notice 741A section 12 |
| UK business supplies a general-rule service to a French private customer | May be within the scope of UK VAT | Whether any special B2C rule displaces the general rule |
| UK architect provides services directly connected to property in Spain | Generally outside the scope of UK VAT under the land rule | Direct connection to the property and Spanish VAT requirements |
| UK supplier sells automated digital access to a private customer in Ireland | May be outside the scope of UK VAT under digital-services rules | Classification, customer location and EU VAT registration/OSS requirements |
These examples demonstrate why “EU versus non-EU” is not enough to determine the UK VAT result. The service and customer status must be established first.
Outside the Scope of UK VAT vs Zero-Rated Services
| Classification | Meaning | Example or implication |
|---|---|---|
| Outside the scope of UK VAT | The supply is not within UK VAT’s territorial scope under the place-of-supply rules | Many general-rule B2B services to overseas businesses |
| Zero-rated | The supply is within the UK VAT system but the applicable rate is 0% | Specific supplies that qualify for zero-rating under UK law |
| Exempt | The supply is within the UK VAT system but is exempt under a relevant provision | Some financial and other exempt services; input VAT recovery may be restricted |
The distinction matters for invoicing, VAT accounting, turnover calculations and input VAT recovery. Input VAT incurred in connection with overseas supplies may be recoverable where the relevant statutory conditions are met, but partial exemption and other restrictions can apply.
Reverse Charge VAT on Overseas Services
The reverse charge is a mechanism under which the recipient, rather than the supplier, accounts for VAT under the applicable law. It should not be described as automatically applying to every service supplied abroad.
For a qualifying B2B supply to an EU customer, the customer’s local VAT rules may require the customer to account for VAT under a reverse charge. Confirm the customer’s status, the service type and the law of the destination country. A US customer should not automatically be given an EU-style reverse-charge statement.
There is also a separate UK reverse-charge mechanism relevant when UK businesses receive certain services from overseas suppliers. That inbound situation is different from the main subject of this guide.
How to Invoice Overseas Customers
Invoice examples: UK VAT on overseas services
| Invoice item | German business (general-rule B2B) | US private consumer (general-rule B2C) |
|---|---|---|
| Service | Business consultancy | Service not covered by a special B2C rule |
| Fee before UK VAT | £1,000 | £1,000 |
| UK VAT treatment | Outside the scope of UK VAT | UK place of supply; charge UK VAT at the rate applicable to that taxable service |
| What to retain | Business status and receiving-establishment evidence | Service classification and evidence supporting the B2C treatment |
These examples assume a UK VAT-registered supplier and no other special rule. They illustrate why the answer to “Do I have to charge VAT to overseas customers?” depends on both customer status and service classification.
Your invoice should identify the supplier and customer, describe the service accurately, state the consideration and apply the correct UK VAT treatment. A supplier that has determined that a service is outside the scope of UK VAT should not show a fictional 0% UK VAT rate as though it were a zero-rated supply.
Illustrative invoice wording
“Outside the scope of UK VAT — place of supply outside the United Kingdom under the applicable place-of-supply rules.”
This is illustrative explanatory wording, not a mandatory HMRC formula and not a substitute for any invoice statement required by the customer’s jurisdiction. Where an overseas reverse charge applies, use wording appropriate to that country’s rules.
Retain evidence of the customer’s business status and location, the service agreement, relevant invoices and the basis for your VAT decision. Check applicable record-retention obligations.
Reporting Overseas Services on Your UK VAT Return
Under VAT Notice 700/12, Box 6 generally includes supplies outside the scope of UK VAT as described in Notice 741A. Box 1 records UK output VAT due; a correctly classified outside-the-scope service does not create UK output VAT merely because its value appears in Box 6. The detailed treatment depends on the transaction and any applicable VAT accounting scheme.
Worked example: overseas consultancy invoice
Assume a UK VAT-registered consultancy invoices £2,000 for an ordinary general-rule service to a verified German business, with no special place-of-supply exception. The supply is normally outside the scope of UK VAT. No UK output VAT is charged on that invoice. Under the normal VAT Return rules, the £2,000 is generally included in Box 6, but it does not add UK VAT to Box 1. Check scheme-specific reporting rules before filing.
This example addresses the supplier’s UK VAT Return. It does not establish the German customer’s reporting obligations.
VAT on Overseas Services After Brexit
Businesses searching for Brexit VAT on services should distinguish services from goods. The main general-rule B2B customer-location test remains relevant for supplies to EU businesses, but UK suppliers may face different EU compliance, invoicing or registration requirements than before the end of the transition period. For services supplied to overseas customers, check the current UK place-of-supply rules and the relevant destination-country obligations independently.
Following the end of the Brexit transition period, UK suppliers must apply the current UK place-of-supply rules and separately consider the relevant EU member state’s VAT law where applicable. The general B2B customer-location principle continues to be important, but the UK’s departure from the EU does not make every supply to an EU customer zero-rated or outside the scope automatically.
For cross-border services, keep goods-specific Brexit rules separate from service rules. Northern Ireland’s special arrangements for goods should not be assumed to govern all services.
Common VAT Mistakes and How to Correct Them
- Charging UK VAT solely because the supplier is in the UK: first establish the correct place of supply.
- Assuming all overseas private customers are VAT-free: check the B2C general rule and applicable exceptions.
- Calling an outside-the-scope supply “zero-rated”: record the correct VAT classification.
- Treating a video consultation as an automated digital service: assess how the service is actually delivered.
- Assuming the foreign reverse charge always applies: verify the destination country’s requirements.
- Omitting relevant outside-the-scope sales from Box 6: follow Notice 700/12 and your accounting scheme.
What if you have already charged VAT incorrectly?
Review the original contract, customer evidence, tax point and applicable rule before changing the invoice. Where an invoice or VAT Return was wrong, the appropriate correction may involve a credit note, corrected invoice and/or a VAT Return error adjustment or separate disclosure. Follow VAT Notice 700/45 and the relevant correction conditions. Do not simply remove previously declared VAT without considering the invoice and reporting consequences.
Overseas Services VAT Checklist
- Confirm that the transaction is a service rather than goods.
- Describe the actual service and identify any composite supply.
- Establish whether the customer is acting as a business or consumer.
- Identify where the customer and relevant establishments belong.
- Check whether a special place-of-supply rule applies.
- Determine the UK place of supply and VAT classification.
- Consider destination-country VAT, GST or sales-tax obligations separately.
- Collect and retain evidence supporting the decision.
- Issue an invoice with accurate VAT treatment and appropriate wording.
- Report the transaction correctly on the UK VAT Return and review the treatment if facts change.
Frequently Asked Questions
Do you charge VAT on services to overseas clients?
Not automatically. General-rule B2B services to overseas businesses are normally outside the scope of UK VAT, while B2C services require consideration of the general rule and exceptions.
Do UK companies charge VAT to EU businesses?
Usually not for qualifying general-rule B2B services where the EU business customer belongs outside the UK. Special rules and the customer’s local VAT obligations must still be checked.
Do I charge UK VAT to a private customer in the USA?
It depends on the service. Certain professional, consultancy, advertising and intangible services may qualify for the special B2C rule, while other services may follow the general B2C rule or a different exception.
Is a VAT number essential to prove an overseas customer is a business?
It is useful evidence, particularly for EU businesses, but HMRC permits other appropriate evidence in relevant circumstances. Keep documentation that supports the customer’s business status.
Does UK VAT apply when the work is performed in the UK?
Not necessarily. For many services the place of supply depends on customer status and belonging rather than where the supplier physically performs the work.
Are digital services to overseas customers VAT-free?
Do not assume so. Electronically supplied services have particular rules, and overseas VAT obligations may arise even where UK VAT is not charged.
Do overseas service invoices go in VAT Return Box 6?
HMRC’s normal Box 6 rules include supplies outside the scope of UK VAT under Notice 741A. Check the transaction and any applicable special accounting scheme.
Can I reclaim UK input VAT relating to overseas services?
Potentially, where the relevant recovery conditions are met. The nature of the supplies, partial exemption and other restrictions can affect recovery.
Do I have to charge VAT to overseas customers?
Not always. Under the general B2B place of supply rule, most services supplied by a UK business to an overseas business customer are outside the scope of UK VAT. For private customers, UK VAT may apply under the general B2C rule, but exceptions exist for certain professional, consultancy, advertising and electronically supplied services. The correct treatment depends on the customer’s status, where they belong and the type of service supplied.
Is VAT charged on services outside the UK?
Not necessarily. The physical location where services are performed does not automatically determine whether UK VAT is due. If the place of supply is outside the UK under the applicable rules, the service is generally outside the scope of UK VAT. However, some services performed abroad may still have a UK place of supply, and overseas VAT obligations may arise.
What does HMRC say about VAT on overseas services?
HMRC VAT Notice 741A explains how to determine the place of supply of services, including the general B2B and B2C rules and their exceptions. HMRC VAT Notice 700/12 explains VAT Return reporting, including the treatment of relevant outside-the-scope supplies in Box 6. Businesses should check both notices before deciding how to invoice and report overseas services.
HMRC Guidance and Professional Support
For the full rules, consult HMRC VAT Notice 741A and HMRC VAT Notice 700/12. Cross-border supplies can require a review of contracts, customer status, establishments and the precise service classification.
If you need help assessing a particular transaction or coordinating UK and overseas VAT treatment, see Audit Consulting Group’s International VAT Services.
+44 7386 212550
info@auditconsultinggroup.co.uk
Final Thoughts
VAT on overseas services is one of the most technical areas of UK VAT. While the general rules are clear in principle, exceptions, customer status, and Brexit changes create real-world complexity. Applying the correct place of supply rules protects your business from penalties, ensures accurate VAT reporting, and prevents unnecessary VAT costs for you and your customers.