£23,000 After Tax UK (2026/27): Monthly & Annual Take-Home Pay
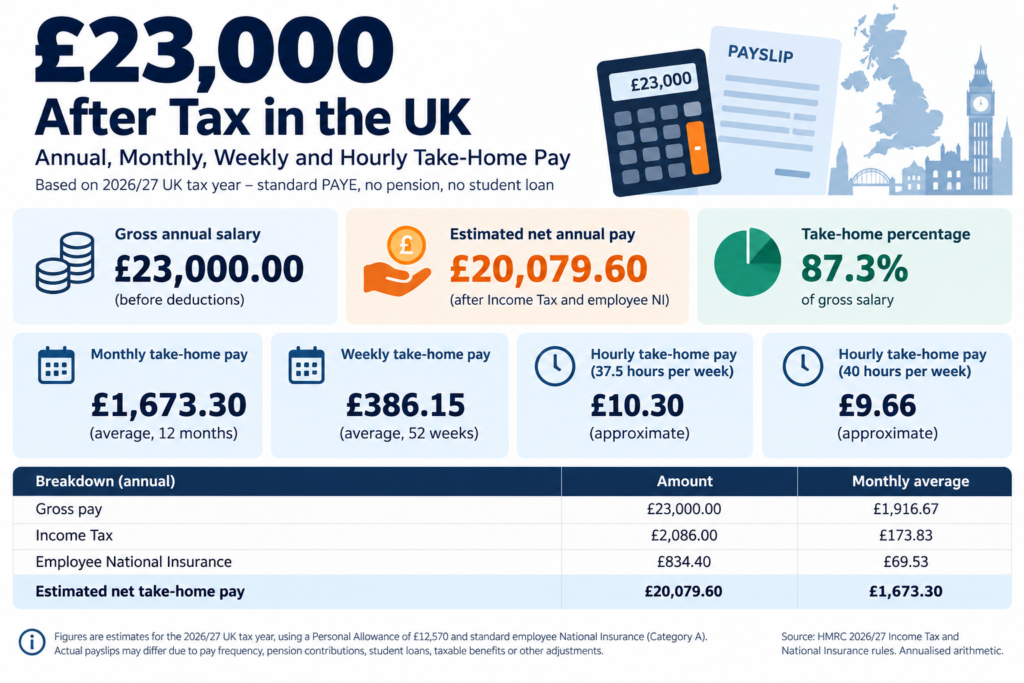
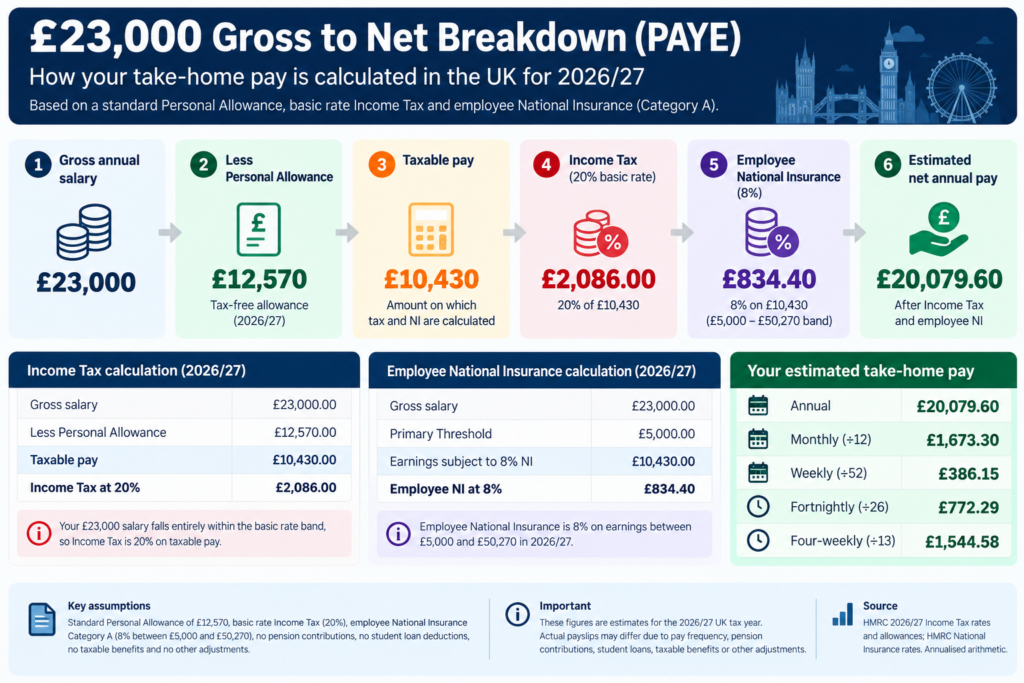
If your gross annual salary is £23,000, your estimated take-home pay after Income Tax and employee National Insurance is £20,079.60 a year, or £1,673.30 a month, in England, Wales or Northern Ireland in the 2026/27 UK tax year. That is about £386.15 a week. These figures assume a standard Personal Allowance of £12,570, ordinary PAYE employment, employee National Insurance category A, and no pension contributions, student-loan deductions, taxable benefits or other adjustments. Actual payslips can differ because payroll operates by pay period.
This guide shows how a £23,000 salary after tax works in the UK, from monthly take-home pay to Income Tax, National Insurance, Scottish rates and common payslip deductions. Here, £23,000 after tax means starting with £23,000 gross annual pay and calculating what remains; it does not mean earning £23,000 net.
How Much Is £23,000 After Tax in the UK?
| £23,000 gross salary — standard PAYE illustration | Annual | Monthly average |
|---|---|---|
| Gross pay | £23,000.00 | £1,916.67 |
| Income Tax | £2,086.00 | £173.83 |
| Employee National Insurance | £834.40 | £69.53 |
| Estimated net take-home pay | £20,079.60 | £1,673.30 |
 For someone asking what is £23,000 after tax in the UK, the table gives the standard annual and monthly PAYE estimate. Your take-home pay on £23,000 is approximately 87.3% of gross earnings; Income Tax and employee NI together account for around 12.7%. Scottish taxpayers have a slightly different result because Scottish Income Tax bands apply to employment income.
The illustration is for the tax year 6 April 2026 to 5 April 2027. It is not a payslip guarantee or a calculation of employer costs. The official Income Tax rates and allowances and National Insurance rules determine the basic rates used below.
£23,000 Salary After Tax: Annual, Monthly, Weekly and Hourly
If you are comparing job offers, budgeting for rent or checking a monthly payroll deposit, the same £23k annual salary can be expressed in different ways. A salary of 23000 after tax per month is not £23,000 per month: the £23,000 figure is the annual gross salary.
| Pay period | Gross equivalent | Estimated net equivalent |
|---|---|---|
| Year | £23,000.00 | £20,079.60 |
| Month (12 per year) | £1,916.67 | £1,673.30 |
| Week (52 per year) | £442.31 | £386.15 |
| Fortnight (26 per year) | £884.62 | £772.29 |
| Four weeks (13 per year) | £1,769.23 | £1,544.58 |
| Day (260 working days) | £88.46 | £77.23 |
These are annualised averages, not predictions of the precise tax and NI on an individual weekly or four-weekly payslip. Payroll deductions are calculated using relevant pay-period rules and may involve rounding.
For someone comparing £23k per year after tax with a monthly wage, the important distinction is that £23k a year after tax is not the amount received in the bank: £23,000 is the starting gross salary, while the estimated net annual pay is £20,079.60. If you are paid fortnightly, use the 26-payments figure rather than dividing by 12.
£23k a Year Is How Much a Month?
If you earn £23k a year, that is approximately £1,916.67 gross per month. For a standard PAYE employee, £23k after tax monthly works out at about £1,673.30. So when comparing a £23k monthly salary take-home estimate with a job offer, make sure the offer quotes annual gross pay rather than monthly net pay.
For budgeting, distinguish calendar-month pay from four-weekly pay. Four-weekly workers receive 13 payments in a year, not 12. A four-weekly payment can therefore be smaller than a monthly one without the annual salary being lower.
If your question is how much is £23,000 a year after tax per month, the annualised answer is £1,673.30. That is the same calculation used for a £23k take-home pay UK estimate; it is not a promise that every payslip will be identical.
£23,000 a Year Per Hour — and the Minimum Wage Check
The hourly figure depends on contracted hours, not just salary. Assuming 52 paid weeks:
| Contracted hours | Gross hourly equivalent | Effective net hourly equivalent |
|---|---|---|
| 37.5 hours/week | £11.79 | £10.30 |
| 40 hours/week | £11.06 | £9.65 |
These are arithmetic salary equivalents, not statutory minimum-wage calculations. From April 2026, the National Living Wage for workers aged 21 and over is £12.71 per hour. At £23,000 gross, the illustrative £11.79/hour at 37.5 hours and £11.06/hour at 40 hours are below that rate. On a simple 52-week calculation, £23,000 supports about 34.8 paid hours per week at £12.71/hour. Whether an actual arrangement complies depends on the worker’s age, hours counted for minimum-wage purposes, pay reference period and relevant deductions. Check the current National Minimum Wage rates and ask the employer to clarify any apparent shortfall. The effective net hourly figure is not the basis for minimum-wage compliance.
How Is Tax Calculated on a £23,000 Salary?
A reliable £23,000 salary after tax calculator should make its arithmetic visible. The following steps show exactly how the standard £23,000 PAYE calculation works in England, Wales and Northern Ireland. A tax calculator that does not disclose its assumptions may give a different result because it includes pensions, student loans or a different tax year.
 Personal Allowance and Taxable Pay
 Personal Allowance and Taxable Pay
The standard Personal Allowance in 2026/27 is £12,570. For an employee entitled to the full allowance, the amount of £23,000 subject to Income Tax is:
£23,000 − £12,570 = £10,430 taxable employment income.
The Personal Allowance is an Income Tax concept; do not treat the taxable-income calculation as the legal method for every National Insurance situation. Employee NI has its own thresholds, category rules and earnings-period calculations.
Income Tax on £23,000
For this salary, all £10,430 of taxable income falls within the 20% basic-rate band in England, Wales and Northern Ireland:
£10,430 × 20% = £2,086 Income Tax per year.
That is about £173.83 per month on an annualised basis. If you want to know how much Income Tax you pay on a £23k salary, this £2,086 figure covers Income Tax only. National Insurance is a separate deduction, explained next.
National Insurance on £23,000
For an ordinary employee in NI category A, the 2026/27 main employee Class 1 rate is 8% on earnings between the applicable primary threshold and upper earnings limit. Under the regular-pay assumptions used here, the annualised calculation is:
(£23,000 − £12,570) × 8% = £834.40 employee NI.
This is approximately £69.53 per month. To calculate £23,000 after tax and NI, subtract both £2,086 Income Tax and £834.40 employee National Insurance:
£23,000 − £2,086 − £834.40 = £20,079.60 net per year.
An employee’s NI may differ from this annualised estimate because NI is generally assessed each earnings period; directors and some other categories have special rules. For official thresholds see HMRC’s 2026/27 employer rates.
£23,000 After Tax in Scotland, Wales and Northern Ireland
23000 after tax Scotland is not always the same as the figure for England. Scotland has separate Income Tax bands for non-savings, non-dividend income, including employment earnings. Wales and Northern Ireland use the same 20% basic rate as England for the standard salary example here. Employee NI rates generally apply UK-wide.
For a Scottish resident with the full Personal Allowance in 2026/27, the first £3,967 of taxable pay is charged at 19% and the remaining £6,463 at 20%. Scottish Income Tax is therefore £2,046.33; employee NI in the same illustrative category A scenario is £834.40.
| Region | Income Tax | Employee NI | Estimated annual net | Estimated monthly net |
|---|---|---|---|---|
| England | £2,086.00 | £834.40 | £20,079.60 | £1,673.30 |
| Wales | £2,086.00 | £834.40 | £20,079.60 | £1,673.30 |
| Northern Ireland | £2,086.00 | £834.40 | £20,079.60 | £1,673.30 |
| Scotland | £2,046.33 | £834.40 | £20,119.27 | £1,676.61 |
The difference is approximately £39.67 per year in favour of the Scottish illustration at this salary. Actual tax residence, tax code, payroll frequency and other income can change the result. See the official Scottish Income Tax rates.
£23,000 After Tax With Pension Contributions
A search for 23000 after tax and pension needs more than one number. Workplace pension deductions depend on scheme rules, qualifying earnings, whether contributions use net pay, relief at source or salary sacrifice, and whether the employee has opted in or out. Pension contributions reduce money paid into your bank account but can increase long-term retirement savings; tax treatment varies.
Illustrative calculation only: a pension scheme using 5% of the full £23,000 salary would calculate £1,150 a year as a gross contribution. That does not necessarily mean £1,150 is deducted from take-home pay: under relief at source, basic-rate tax relief can change the employee’s direct payment; under a net-pay arrangement, tax relief operates through payroll; salary sacrifice changes the contractual pay arrangement. Other schemes use qualifying earnings rather than full salary. Check the scheme basis and payslip before estimating net pay.
| Pension situation | What changes | What to check |
|---|---|---|
| No employee pension deduction | Baseline estimated net £20,079.60 | Eligibility and whether you have opted out |
| Relief-at-source pension | Net pay reduced by employee contribution; pension provider claims basic-rate relief where applicable | Payslip deduction and provider statement |
| Net-pay arrangement | Pension contributions generally reduce taxable pay through payroll | Taxable pay and pension line |
| Salary sacrifice | Contractual gross salary is reduced in exchange for employer pension contribution; tax/NI outcome may change | Employer agreement, minimum-wage compliance and pensionable pay |
Do not assume that ordinary employee pension contributions always reduce National Insurance. A salary-sacrifice arrangement is different and must also comply with minimum-wage rules. For scheme-specific deductions and tax treatment, review the scheme documents and payslip before estimating 23k after tax and pension.
£23,000 After Tax With a Student Loan
For the 2026/27 tax year, the annual repayment thresholds for standard UK payroll deductions are £26,900 (Plan 1), £29,385 (Plan 2), £33,795 (Plan 4) and £25,000 (Plan 5). On a steady £23,000 salary, you would normally be below all four thresholds, so those undergraduate loan plans would not reduce the baseline take-home figure.
A Postgraduate Loan has a lower annual threshold of £21,000 and a 6% repayment rate above it. With even monthly earnings, a simple annualised example is (£23,000 − £21,000) × 6% = £120 a year, or approximately £10 per month, subject to payroll rounding and actual pay-period calculations.
| Loan type | 2026/27 annual threshold | Standard £23k salary illustration |
|---|---|---|
| Plan 1 | £26,900 | No deduction on steady pay |
| Plan 2 | £29,385 | No deduction on steady pay |
| Plan 4 | £33,795 | No deduction on steady pay |
| Plan 5 | £25,000 | No deduction on steady pay |
| Postgraduate Loan | £21,000 | Approximately £120 a year |
A bonus or unusually high pay period can trigger a loan deduction even if annual earnings ultimately total £23,000. Repayments depend on the plan recorded by payroll, earnings-period thresholds and any other relevant loans. Check the official 2026/27 student and postgraduate loan deduction tables.
Why Your £23k Payslip May Show a Different Net Amount
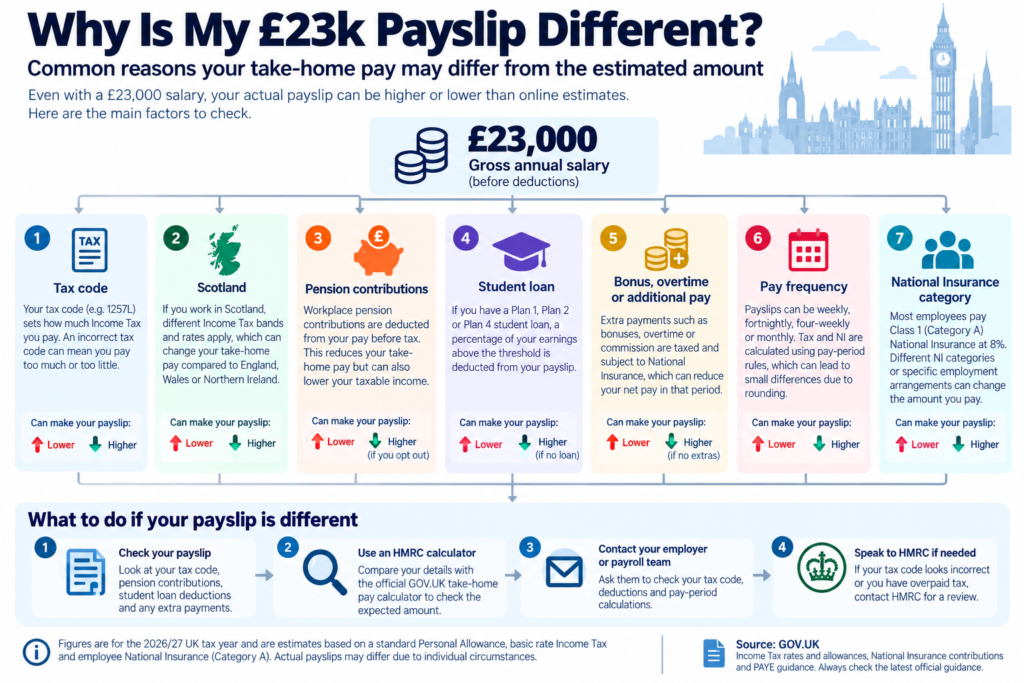
If your payslip does not show £1,673.30 monthly take-home pay, it does not automatically mean your employer has made an error. The online estimate is based on a full tax year with evenly distributed salary and no additional deductions.
| Possible reason | What it means | Practical check |
|---|---|---|
| Different tax code | Personal Allowance may be adjusted or tax calculated on an emergency basis | Compare code with HMRC record |
| Pension contributions | Your pension reduces bank-account pay | Identify pension scheme and contribution basis |
| Student or postgraduate loan | Payroll deducts according to loan type and pay period | Check plan and payroll notification |
| Bonus or overtime | Taxable earnings differ for the period | Compare gross pay and year-to-date figures |
| Started or left job mid-year | PAYE cumulative tax can adjust | Check P45, starter details and tax code |
| Benefits or other deductions | Taxable benefits, salary sacrifice or authorised deductions affect pay | Read each payslip line |
| Scottish tax status | Different Income Tax bands apply | Check Scottish tax code and residence |
| NI category or irregular pay | NI may not equal annual figure divided by 12 | Check category letter and pay frequency |
Emergency Tax and the 1257L Tax Code
A common standard tax code is 1257L for a person receiving the standard Personal Allowance, but not everyone should have that code. Emergency versions such as 1257L W1, 1257L M1 or 1257L X may calculate Income Tax using a non-cumulative basis. If you recently changed jobs, provided a P45 late or started employment without complete payroll details, the first payslip can differ materially from an annualised estimate.
Check your tax code using GOV.UK’s tax-code guidance. Do not assume that an unexpected code is wrong; HMRC may have adjusted it for another job, benefits or previous underpayments.
Overtime, Bonuses and Two Jobs
Overtime and bonuses can increase Income Tax, NI and student-loan deductions in the period paid. Two jobs can use different tax codes and NI may be calculated separately for each employment, subject to specific exceptions. A £23k annual salary is not enough information to determine the correct deductions if you also have other earnings.
For example, a £500 bonus in one month does not mean the entire annual salary is taxed at a higher rate. Instead, payroll calculates deductions according to the relevant rules and tax code, while final annual Income Tax depends on your total taxable income and allowances. If you suspect an error, compare year-to-date gross pay, tax and NI rather than looking only at one month’s net pay. Where the issue involves wider tax-account administration rather than routine payroll, ACG offers tax account management.
Is £23k a Good Salary in the UK?
 If you are wondering is £23k a good salary in the UK, the answer depends on location, household size, housing costs, working hours, benefits and personal circumstances. A salary of £23,000 might suit some entry-level, part-time or lower-cost living situations, but the same income may leave limited room for rent and savings elsewhere. There is no single nationally correct judgement.
When assessing £23k a year after tax in the UK, start with the £1,673.30 estimated monthly take-home pay and list essential expenses: rent or mortgage, council tax, utilities, food, transport, childcare, debt repayments and savings. Check whether the job offer is full-time or pro rata, and whether pension deductions or student loans affect net pay. Compare offers using both gross annual salary and contracted hours, not the headline salary alone.
For wider salary context rather than another £23k calculation, see ACG’s Average Wage After Tax UK guide.
£23,000 PAYE Salary vs £23,000 Self-Employed Profit
Calculating £23,000 after tax if you are self-employed requires a different approach from PAYE. A sole trader’s £23,000 taxable profit is turnover minus allowable business expenses, not an employment salary. Self-employed Income Tax may use the same standard Personal Allowance and basic rate in England, but Class 4 National Insurance rules, business expenses, other income and Self Assessment obligations must be considered. A PAYE salary calculator should not be used as a sole trader’s final tax return. If you have trading income, ACG’s self-employed deductions and allowances page explains a related service, while self-employed registration covers the registration process.
If you invoice £23,000 but spend £5,000 on allowable business costs, your potential taxable profit is £18,000, not £23,000. Conversely, if your profit is £23,000, it may generate a different NI calculation from a £23,000 employee salary. These examples illustrate the difference between revenue, profit and wages; they are not a full sole-trader tax computation.
How to Check Your £23,000 Take-Home Pay
You can use this checklist before questioning your payroll calculation:
- Confirm whether £23,000 is gross annual salary, net annual income, or a pro-rata full-time equivalent.
- Confirm the tax year and whether you are paid monthly, weekly or every four weeks.
- Check the tax code, including any Scottish prefix or emergency suffix.
- Compare taxable pay and Income Tax year-to-date against the standard £12,570 Personal Allowance assumption.
- Check employee NI category, pay period and NI deduction separately from Income Tax.
- Identify workplace pension contributions, salary sacrifice and student/postgraduate loans.
- Check any bonus, overtime, taxable benefits or second job.
- Use official HMRC information or ask payroll to explain individual line items before concluding that a refund is due.
A salary calculator is a useful starting point, but the authoritative records for your employment are your payslips, tax code, P60 and HMRC tax account. If a discrepancy persists, seek an explanation of the precise deduction rather than assuming that the net annual estimate must be paid in twelve identical instalments. Employers looking for assistance with payroll administration can see ACG’s payroll services; for PAYE reporting responsibilities, see PAYE filing support.
Frequently Asked Questions About £23,000 After Tax
 What is £23,000 after tax in the UK in 2026/27?
 What is £23,000 after tax in the UK in 2026/27?
For a standard PAYE employee in England, Wales or Northern Ireland, £23,000 gross is approximately £20,079.60 net per year after £2,086 Income Tax and £834.40 employee NI, before pension or other deductions.
How much is 23k after tax monthly?
Approximately £1,673.30 per month on an annualised basis, assuming a £23,000 gross annual salary and standard PAYE circumstances.
How much is £23,000 after tax per week?
Approximately £386.15 per week when the annual net estimate is divided by 52. Actual weekly payroll calculations may differ.
How much tax do I pay on a £23,000 salary?
In England, Wales or Northern Ireland, the standard annual Income Tax estimate is £2,086. Employee NI adds approximately £834.40 in the stated category A scenario.
Is 23k after tax the same in Scotland?
No. For 2026/27 the Scottish illustrative net is approximately £20,119.27 a year, or £1,676.61 a month, under the same assumptions. Scottish employment Income Tax bands differ.
What is the take-home pay on a £23,000 salary in the UK?
With the standard assumptions in this guide, take-home pay on a £23,000 salary is about £20,079.60 annually, £1,673.30 monthly or £386.15 weekly. The calculation is based on gross pay before pension contributions or other personal deductions.
Is £23k a year before or after tax?
Job adverts normally quote £23k a year before tax unless they explicitly say otherwise. If your offer states a £23,000 annual salary, check whether it is gross pay, a pro-rata full-time equivalent or a guaranteed net amount.
Does £23,000 after tax include National Insurance?
Yes, the headline net figure in this guide deducts both Income Tax and employee National Insurance. It does not deduct pensions, student loans or other payroll adjustments.
Does a student loan reduce my take-home pay on £23k?
On steady earnings of £23,000, standard undergraduate Plans 1, 2, 4 and 5 are below their 2026/27 repayment thresholds. A Postgraduate Loan may result in repayments because its threshold is lower.
What is £23,000 after tax and pension?
It depends on your workplace pension scheme, pensionable earnings and whether contributions are made through relief at source, net pay or salary sacrifice. Check your payslip and scheme documentation; there is no universal figure.
Is £23,000 a year a good salary?
It depends on household expenses, location, working hours and other income. Compare the estimated monthly take-home pay with your actual essential costs rather than relying on a single UK-wide judgement.
What is £23,000 after tax per hour?
For a 37.5-hour week the effective net equivalent is approximately £10.30 an hour; for a 40-hour week it is approximately £9.65. These are arithmetic equivalents, not statutory minimum-wage determinations.
Why is my net pay less than £1,673 per month?
Common reasons include pension contributions, postgraduate-loan deductions, an adjusted tax code, salary sacrifice, taxable benefits, irregular pay or emergency PAYE treatment.
Does 1257L mean I will receive exactly £1,673.30 monthly?
No. It commonly reflects the standard Personal Allowance, but NI, pension contributions, loans and payroll timing can still alter take-home pay.
Is £23,000 gross the same as £23,000 net?
No. Gross is salary before deductions; net is the amount remaining after relevant deductions. A £23,000 net annual income would require a higher gross salary under the standard assumptions.
How much is £23,000 a year after tax if I work part-time?
If £23,000 is your actual annual gross pay, the standard calculation can apply regardless of part-time status. If £23,000 is a full-time equivalent salary and your actual contracted pay is pro rata, calculate deductions using your lower actual gross pay instead.
Official Sources and Last Reviewed
Content prepared for review: 16 October 2026. This is an illustrative 2026/27 PAYE guide, not personalised tax advice. Relevant official sources:
- HMRC — Income Tax rates and allowances
- GOV.UK — National Insurance: how much you pay
- HMRC — Rates and thresholds for employers 2026/27
- GOV.UK — Scottish Income Tax
- HMRC — Student and postgraduate loan deduction tables 2026/27
- GOV.UK — Tax codes
Editorial review: Prepared for technical review on 16 October 2026. The named reviewer and approval date must be confirmed by Audit Consulting Group before publication.
When to Seek Professional Tax Help
Most people with a straightforward £23,000 PAYE salary can check their net pay using their payslip and official HMRC guidance. Professional support may be appropriate if you have multiple sources of income, an unresolved tax-code issue, self-employment alongside a job or a tax-return obligation. Audit Consulting Group provides UK personal-tax support; see the relevant Personal Tax and Self Assessment services.